Intrepid Potash Must Prove Margin Gains Can Outrun A Sharply Smaller Third-Quarter Top Line
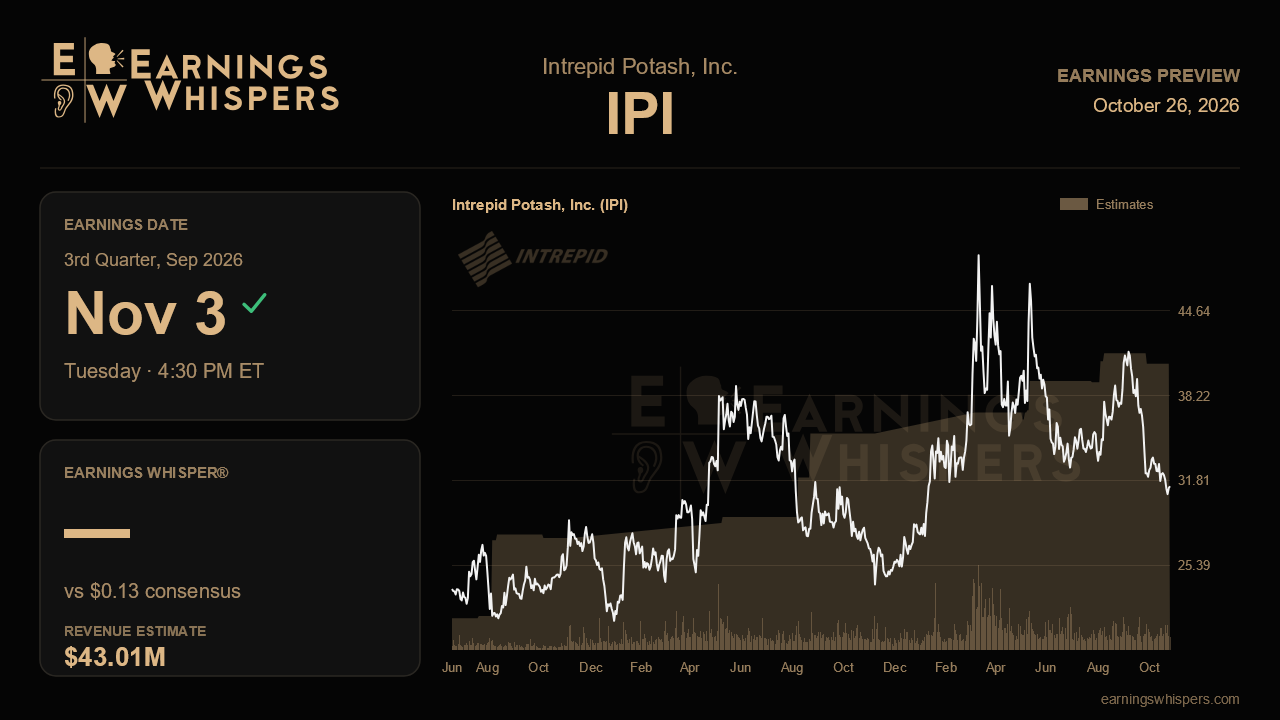
Intrepid Potash heads into its third-quarter report with an awkward mismatch. Management closed the last call sounding more confident than it had in a long time, raising production targets for both potash and Trio and finally launching a $50 million buyback. The stock has since fallen 13%, trailing the S&P 500 by nearly 11 percentage points. That gap sets up the central question for November 3: is the market pricing in a demand problem the company has not yet admitted, or has it overreacted to a seasonal lull?
The numbers themselves frame the tension. Analysts expect earnings of $0.13 a share on revenue of about $43.0 million. That implies EPS growth of roughly 18% from the $0.11 earned a year ago, even as sales fall about 19% from $53.2 million. The third quarter is usually a softer stretch for fertilizer shipments, but a decline of that size cannot be blamed on seasonality alone, because it is measured against the same quarter last year. In effect, the Street is betting that cost control and pricing will carry earnings while volumes or revenue sources shrink. No updated formal guidance accompanies the setup, so the raised production targets from last quarter remain the main benchmark.
Those targets are where this report becomes a real test. Management lifted full-year potash production to 290,000 to 300,000 tons and Trio to 295,000 to 305,000 tons. It attributed the gains to lasting improvements in recovery and throughput rather than tons pulled forward. If that is true, third-quarter production should keep pace with the higher run rate, and unit costs should stay near the second quarter's levels. That quarter delivered Trio cost per ton at its lowest since late 2019. Evidence that those efficiencies held through the summer would support the margin story. A rebound in per-ton costs would suggest last quarter's improvement was partly a one-off.
Pricing and demand are the other swing factors. Potash realized about $391 a ton last quarter, up 8% from a year earlier, and Trio pricing rose 6%. Management pointed to Belarusian production cuts tightening potash markets and to sulfur supply disruptions lifting the value of sulfate products like Trio. It also acknowledged a late-quarter slowdown in summer potash demand and some softness in Trio orders in late May and early June, describing both as normal seasonality. Commentary on fall application season order books and whether price gains are holding will matter as much as the quarter's numbers. With top-line growth absent, pricing is doing most of the work.
Capital allocation adds a fresh layer. This is the first quarter in which repurchases were expected to begin under the new authorization and the framework set out by new CFO Jason Tremblay. With roughly $185 million in cash after the South Ranch proceeds, investors should look for how aggressively the company bought back stock, especially with shares sliding. Updates on the roughly $40 million capex plan, the Pecos water rights matter that already required a $5 million accrual, and the Wendover lithium project's progress toward a feasibility study round out the agenda.
Sentiment offers little sign of a shift. Bullish readings sit near 41%, essentially unchanged from before the last report. Technically, the stock trades at $31.23, well below its 200-day moving average of $36.53 and within about 3% of its post-earnings low of $30.36, a far cry from the $48 peak of the prior quarter. That positioning lowers the bar somewhat, but it also signals real skepticism. Ultimately, the narrative stays intact only if Intrepid shows that its higher production and lower costs are durable enough to grow profits while revenue contracts, and that fall demand will restore volume momentum. Anything less would suggest last quarter's optimism got ahead of the market.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Oct-13 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 | |
| Aug-28 | |
| Aug-27 | |
| Aug-18 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-09 |
