Oportun's Four-Year-Low Charge-Off Target Faces Its Test As Shares Press Record Range
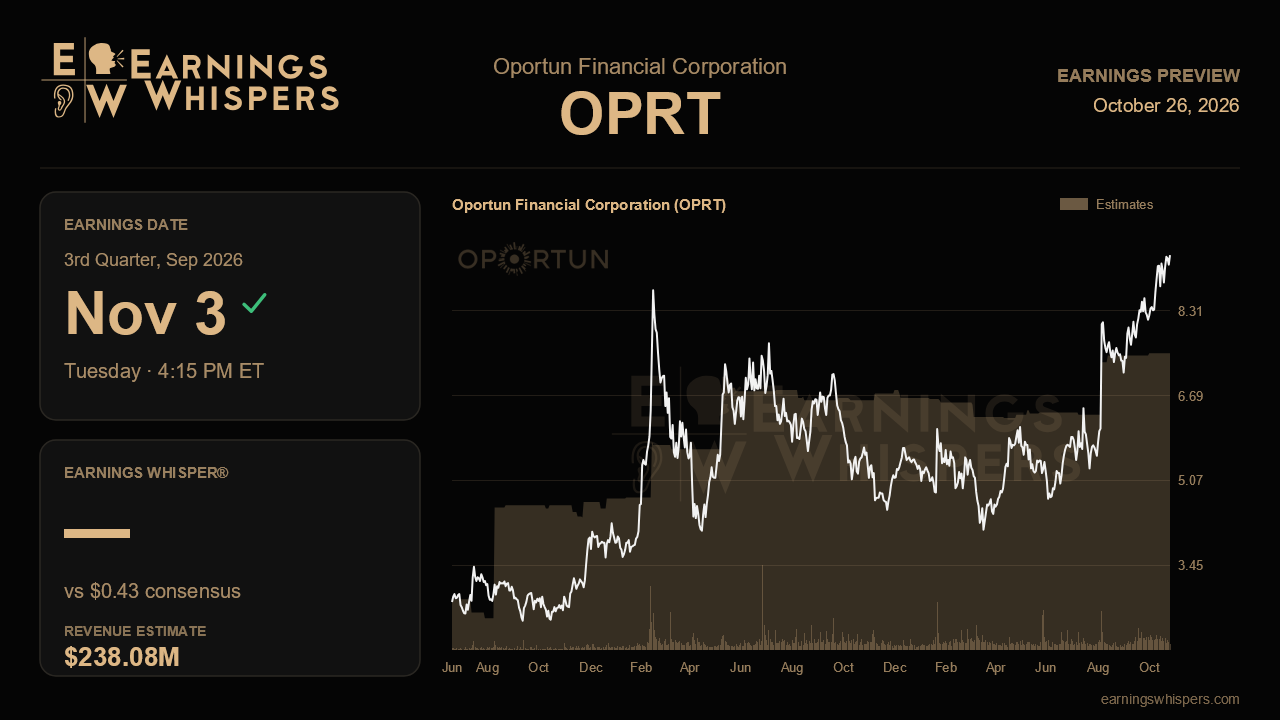
Oportun enters its third-quarter report with a promise to keep. Last quarter, new CEO Doug Bland guided third-quarter net charge-offs to about 11%, give or take 15 basis points. That would be the lowest loss rate in four years and roughly a full point better than the second quarter. The stock has rallied 39% since then while the S&P 500 slipped, so the market has largely accepted the credit turnaround. This report has to show that the turnaround is real and that it can carry earnings even though revenue is not growing.
The Street expects adjusted earnings of $0.43 a share, up about 23% from $0.35 a year ago, on revenue of $238.1 million. That revenue figure is essentially flat year over year and sits in the upper half of management's $235 million to $240 million range. The contrast is the story. Oportun is not growing its top line. It is growing profits by losing less money to bad loans and paying less to fund the book. For the full year, consensus of $1.53 sits near the bottom of the reaffirmed $1.50 to $1.65 range. That leaves room for an upside surprise, but it also reflects real caution.
The caution has a specific source. Management raised its adjusted EBITDA outlook to a $168 million midpoint and now expects interest expense to fall at least 15% this year. Even so, it held net income and EPS guidance steady, because rate-driven fair-value marks were eating into the funding savings. Second-quarter interest expense also included about $7 million of non-recurring, non-cash benefit, and only around $3 million more is expected across the back half. Consensus asks Oportun to earn more this quarter than its $0.38 last quarter without that cushion. The improvement therefore has to come mainly from credit. A charge-off rate at or below 11%, along with 30-plus-day delinquencies holding near the 4.0% multi-year low, would support the case. A miss on the charge-off guide would undercut the main reason the stock has re-rated.
Growth is the second question. Originations returned to a 1% year-over-year gain in the second quarter after falling 11% in the first. Returning members made up 82% of volume, and secured personal loans rose 15%. Sustained, modest origination growth with returning customers still dominant would suggest Oportun can expand without loosening its deliberately tight underwriting. The newer catalysts are earlier-stage but worth tracking. The Column bank partnership, signed in July, allows testing of risk-based pricing above 36%. The V13 credit model went live for new members in June. Early commentary on pricing tests, approval rates and V13 loss performance would hint at whether revenue can finally inflect in 2027.
The shares sit at $9.37, comfortably above the 200-day average of $6.12 and within a hair of the post-earnings high of $9.45. In effect, they are testing a breakout from a range well above last quarter's $4.65 to $6.46 band. Sentiment remains slightly bearish but has edged less negative than before the prior report. Doubters persist, yet the price action tells a more optimistic story than the mood readings, and that raises the bar.
In the end, this quarter turns on whether credit performance can do the heavy lifting the interest-expense windfall did last time. If Oportun hits its 11% charge-off target, keeps delinquencies near lows and shows a pulse in originations, it has a credible argument for nudging EPS guidance off the floor. If losses run hot or fair-value marks bite harder, a stock priced for a clean turnaround has little margin for error.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-22 | |
| Sep-21 | |
| Sep-11 | |
| Sep-08 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Jul-27 | |
| Jul-24 | |
| Jul-22 | |
| Jul-09 | |
| Jun-23 | |
| Jun-16 |
