Primoris Must Show Its Renewables Damage Is Contained After Three Guidance Cuts
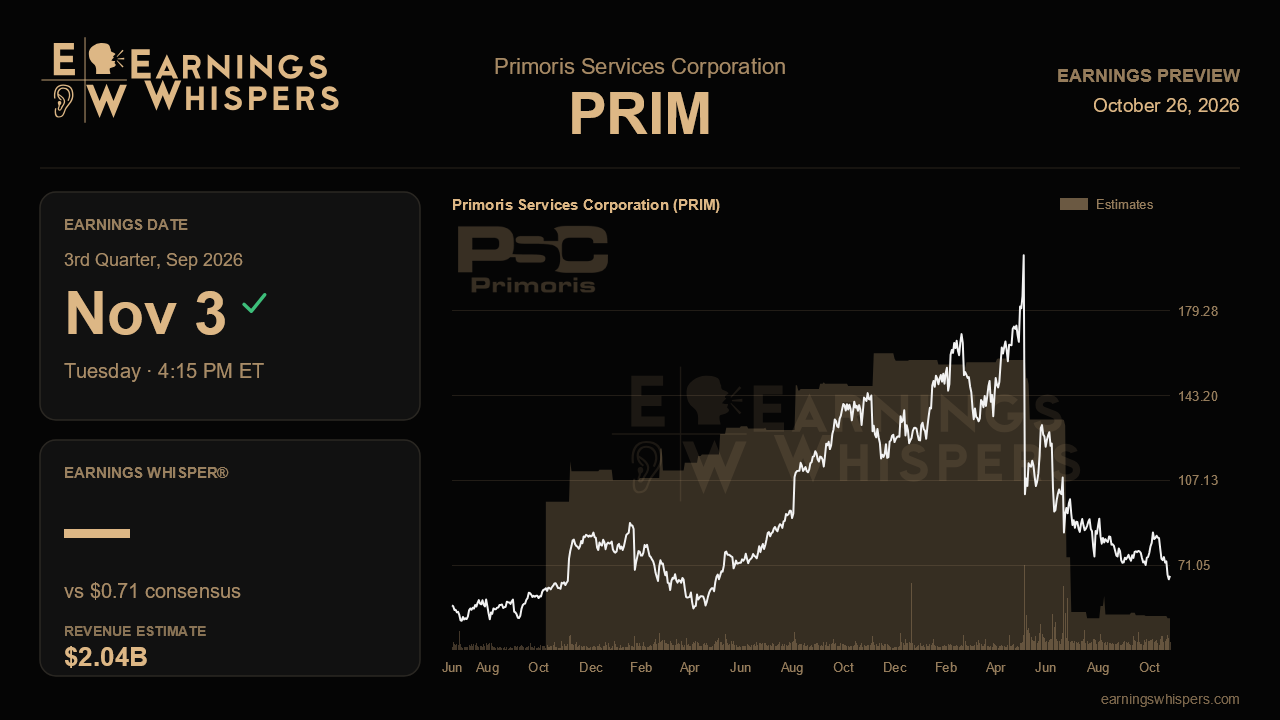
Primoris enters its third-quarter report with two very different businesses under one ticker. One holds a record $13.9 billion backlog, a natural gas generation pipeline that keeps growing and a power delivery franchise adding work. The other is a renewables operation that wiped out the energy segment's gross margin last quarter and forced management to cut full-year profit guidance roughly in half. The November 3 release, due after the close, is the first real test of new CEO Vadlamudi's claim that the second quarter marked the bottom.
The Street is braced for a sharply weaker year-over-year print. Consensus calls for earnings of $0.71 a share on revenue of $2.04 billion, which would be down about 61% and 6%, respectively, from the $1.83 and $2.18 billion posted a year ago. That is a contraction quarter by any measure, but it is also a large sequential step up from the $0.30 loss and $1.69 billion in revenue reported last time. Management reaffirmed its full-year adjusted EPS outlook of $2.05 to $2.60, and the $2.33 consensus sits almost exactly at the midpoint. In other words, analysts have accepted the reset without pushing below it. The more specific yardstick is the company's guide for third-quarter adjusted EBITDA of $90 million to $110 million, followed by $100 million to $120 million in the fourth quarter. A result near or above the top of that Q3 band would lend credibility to the full-year range. Anything below it would raise the uncomfortable question of whether a fourth cut is coming, after guidance slid from $5.80 to $6.00 at the start of the year to $4.80 to $5.00 and then to today's level.
The operational heart of the report is the energy segment. Management cut its full-year energy gross margin target to 6% to 8% after the segment went slightly negative in the second quarter, blaming six troubled renewables projects hit by difficult soil and rock, weather and labor problems in unfamiliar regions. Getting to that annual range from a negative Q2 requires a meaningful second-half rebound, so third-quarter segment margins need to move decisively back into positive mid-single digits at minimum. Commentary that the problem projects are on schedule to wrap by year-end, with no new charges or additions to the list, would validate the trough narrative. Fresh cost overruns would undercut it badly.
Cash is the second pressure point. Operations consumed cash in both the first and second quarters, free cash flow guidance was halved to roughly $150 million to $200 million, and leverage was expected to climb toward 2 times EBITDA this quarter after the company sat in a net cash position at the end of last year. A return to positive operating cash flow would go a long way toward easing balance sheet concerns.
The bullish case rests on the growth engines. Natural gas generation booked $1.4 billion last quarter, its funnel rose to $8.7 billion, and management sees revenue in that business climbing from around $500 million to $600 million this year toward $800 million to $1 billion or more in 2027. Pipeline is recovering with a funnel above $7 billion, and the Paynecrest acquisition, with its data center exposure, was running ahead of plan. Continued bookings strength and stable or growing backlog would show that demand is not the issue; execution is.
The market has delivered its verdict on execution so far. Shares have fallen about 27% since the last report while the S&P 500 slipped roughly 1%, and at $66.51 the stock trades near the bottom of its post-earnings range of $62.41 to $92.25 and far below its 200-day average of about $115. Sentiment has flipped from mildly bullish to mildly bearish. That pessimism lowers the bar somewhat, but it also signals little patience. The report ultimately comes down to whether energy margins and cash flow show the renewables bleeding has stopped, because a record backlog is only worth what Primoris can earn on it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-28 | |
| Sep-11 | |
| Aug-31 | |
| Aug-26 | |
| Aug-19 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
