Procore's Margin Surge Faces Its Next Test As Guidance Implies Slower Revenue Growth
Procore Technologies enters its third-quarter report with an unusual tension baked into the numbers. Management has raised its full-year outlook twice in a row, delivered its first GAAP operating profit, and promised a 25% non-GAAP operating margin for 2027. Yet the company's own third-quarter revenue guidance implies growth cooling to roughly 13% from nearly 16% last quarter. When Procore reports after the close on November 3, the question is whether that guide is genuine deceleration or simply the conservative starting line from a team that has learned to clear its own bar.
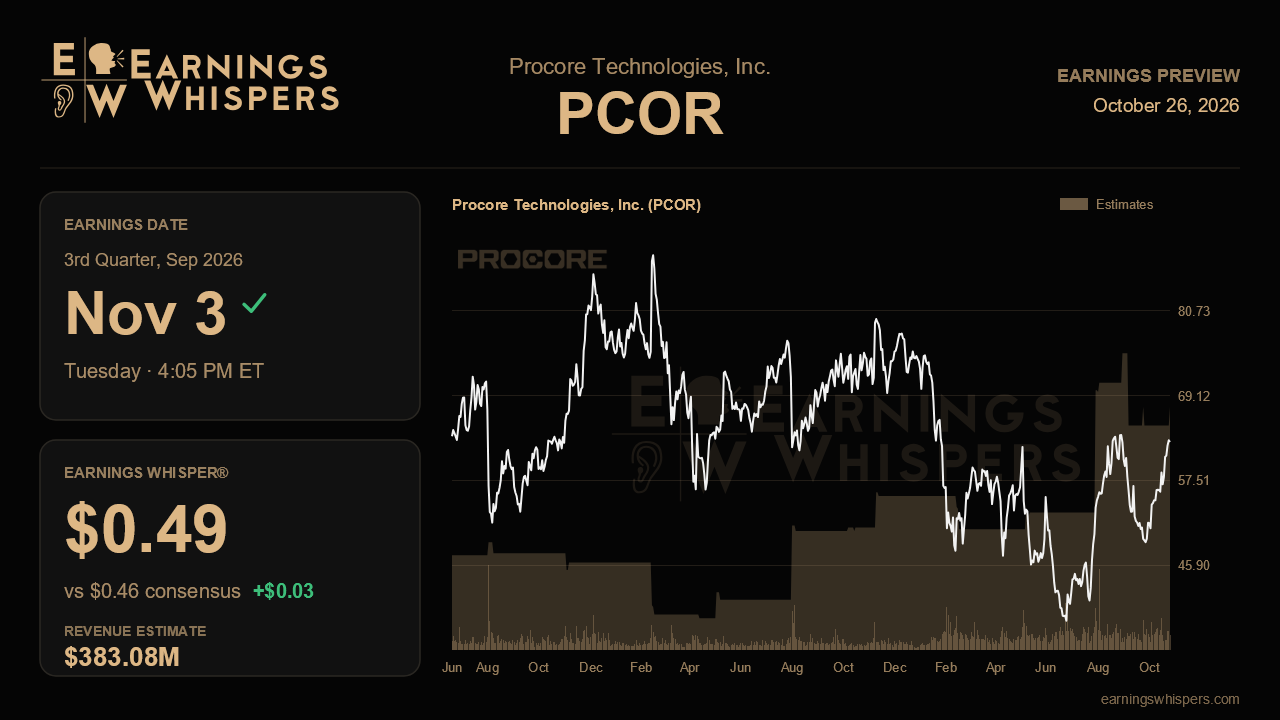
Wall Street expects non-GAAP earnings of $0.46 per share on revenue of $383.1 million, up about 13.1% from $338.9 million a year ago. That revenue figure sits squarely in the middle of management's $382 million to $384 million range, so the Street is not leaning out ahead of the company. The Earnings Whisper of $0.49 sits a few cents above consensus. That is a modest gap, but it tells you the more engaged crowd expects another profitability beat. Last quarter Procore topped the high end of its revenue guidance by about 2.5%. A repeat would put revenue near $392 million and growth back in the mid-teens, which would make the apparent slowdown look like guidance math rather than a fading business.
The second-quarter call gave this report several specific things to prove. The most important is bookings quality. Current remaining performance obligations accelerated by 100 basis points, and management credited underlying bookings rather than the longer contract durations that had flattered the metric in earlier quarters. Continued CRPO strength driven by new business would validate the idea that demand is improving on its own merits. A slide back toward duration-driven growth would weaken it. The same goes for Procore AI, which reached general availability with 20 agents and moved from a small overlay team to the full sales force. This is the first full quarter to show whether broader distribution produces real deal activity, and data center work, which management called unprecedented, is the obvious place to look for it.
Margins are the other pillar. The full-year non-GAAP operating margin target of 18.5% to 19% looks modest next to the 21.5% posted last quarter. Another quarter near that level would strengthen confidence in the 2027 target, which management tied to cost discipline rather than revenue upside. The complication is DroneDeploy, the $845 million acquisition that brings drone-based visual intelligence and about 600 shared customers. Management flagged a near-term gross margin headwind and bridge financing whose long-term effect on earnings is still unsettled. Any update on timing, integration, or permanent financing will matter, especially with two acquisitions in under nine months. Clear evidence that the deal is not eroding the margin path would be reassuring.
The backdrop is mixed. Management called the construction market uneven, with manufacturing soft and core U.S. residential and multifamily activity turning negative. Commentary on whether that weakness is spreading or stabilizing will shape how much credit the market gives the full-year raise. Sentiment has also cooled. Bearish readings rose to 55.7% from 43.9% before the last report, even as the stock gained 12.1% since then, outpacing the S&P 500 by about 8 points. At $62.77, shares sit well above the 200-day moving average of $53.68 and about 3% below the post-earnings high of $64.79. That puts the stock near the top of its range, which raises the stakes for any stumble.
Ultimately, this report hinges on whether Procore can again pair upside revenue with expanding margins while absorbing DroneDeploy. A beat, a third straight guidance raise, and bookings-driven CRPO growth would confirm that the confident execution story is real. A revenue print stuck at the midpoint, or signs that the uneven end market is reaching Procore's pipeline, would suggest the 13% guide was a warning rather than a cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Sep-28 | |
| Sep-18 | |
| Aug-14 | |
| Aug-06 | |
| Aug-04 | |
| Aug-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
