Redwood Trust's Book Value Test Looms As Stock Trades Near Half Of Reported Equity
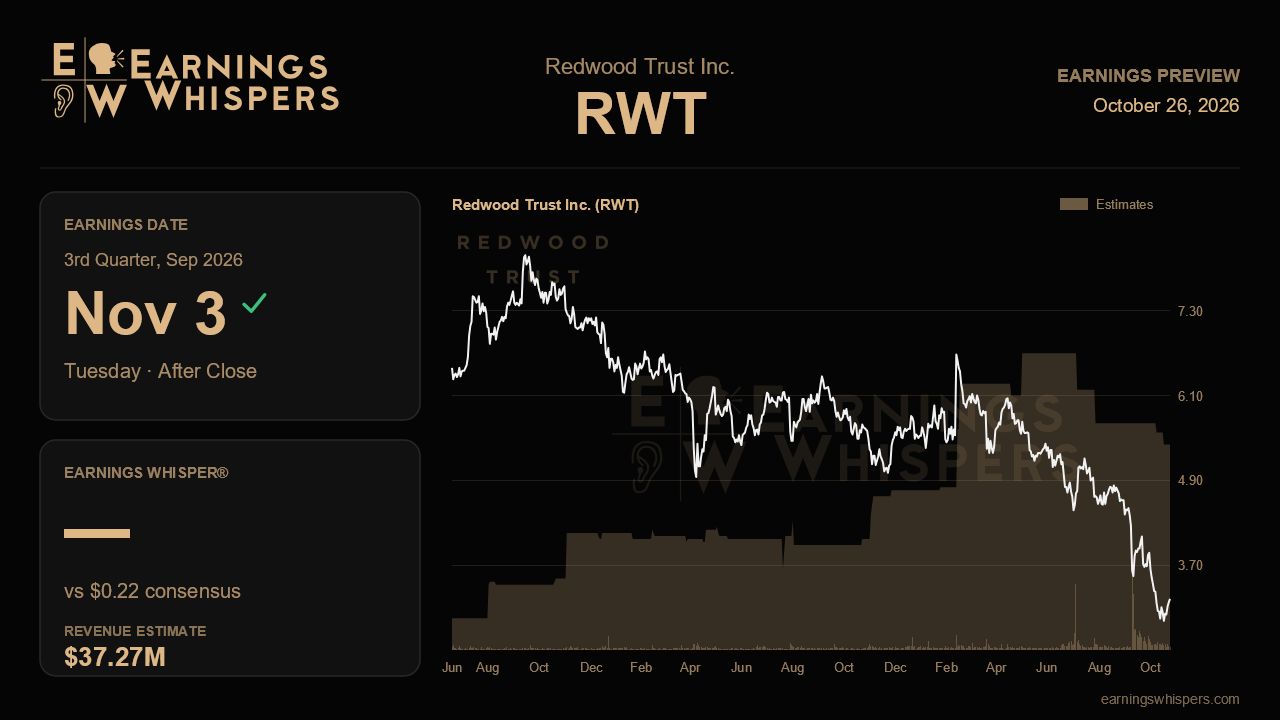
Redwood Trust heads into its third-quarter report with an awkward contradiction to resolve. Management spent the last call describing a leaner, more focused mortgage banking machine, with legacy capital shrinking faster than planned, costs falling and a dedicated joint venture now backing every platform. The market has answered with a 32.6% drop in the shares since that report, a 36-point gap against the S&P 500. At $3.23, the stock trades at less than half of the $6.90 book value reported at the end of June. That discount says the market doubts either the earnings story or the balance sheet, and possibly both.
The Street expects earnings of $0.22 a share on revenue of about $37.3 million. That would be roughly 10% above the year-ago $0.20 but a step down from the $0.25 posted last quarter, so the consensus already builds in some sequential cooling. That seems reasonable. Total mortgage banking volume slipped about 6% in the second quarter from a first-quarter record, refinancing activity was trending lower, and management described a more cautious posture as mortgage rates sat near one-year highs. No formal guidance accompanies the number, which leaves the call itself as the main benchmark.
The biggest operating question is whether Sequoia, the jumbo loan platform, can hold its ground against the banks. Its gain-on-sale margin compressed to 92 basis points from 96 in the first quarter and 127 at the end of 2025, as money-center and regional lenders leaned back into mortgages at thinner spreads. Management pointed to Basel III endgame finalization as a reason banks are returning, which suggests the pressure is structural rather than seasonal. Stable margins with recovering volume, helped by the first full quarter of the Castle Lake joint venture that came online in late June, would validate the idea that dedicated capital partners let Redwood compete without chasing price. Another leg down in margins would challenge it.
Aspire, the non-agency expanded-credit platform, carries the growth narrative. It posted record locks of $2.1 billion and a gain-on-sale margin that jumped to 101 basis points from 73, and management extended its market share goal to 10% by year-end. The new Crayhill partnership, with up to $8 billion of purchasing power, should support volume, but the jump in margins was large enough that some giveback would not be alarming. What would matter is evidence that share gains are continuing. At CoreVest, the business-purpose lender, the passage of housing legislation carving out build-to-rent revived term-sheet activity by about 40% from the spring trough. This quarter should show whether that pipeline is converting into funded loans and whether the jump in net cost to originate, to 96 basis points from 79, reverses.
The cost story looks the most durable. General and administrative expense fell to $38 million from $49 million, first-half direct expenses ran at 64 basis points of volume versus 88 for 2025, and AI-related time savings were scaling quickly. Holding those gains through a softer volume quarter would demonstrate genuine operating leverage rather than a one-quarter cleanup. Meanwhile, legacy capital was already below 10% early in the third quarter against a year-end target under 5%, and management has said each $100 million redeployed adds roughly 200 to 400 basis points to consolidated return on equity.
Sentiment has warmed noticeably, moving to essentially neutral from a clearly bearish reading before the last report, even as the stock sank toward the bottom of its post-earnings range between $2.88 and $4.88 and well below its 200-day average near $5.06. That mix suggests the shares may already reflect a lot of pessimism. Ultimately, the report hinges on book value. Management flagged a roughly 1% gain quarter to date when it last spoke, after several quarters of erosion and continued negative marks on retained bridge and SFR loans. If book value stabilized and the GAAP loss narrowed further or flipped to a profit, the efficiency narrative would gain credibility. Another decline would keep the market focused on the balance sheet rather than the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-13 | |
| Sep-23 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jul-07 | |
| Jul-02 | |
| Jun-11 | |
| May-19 | |
| Apr-30 |
