Revolve's Sales Are Accelerating, But Margin Comps And Heavier Spending Test Q3 Profits
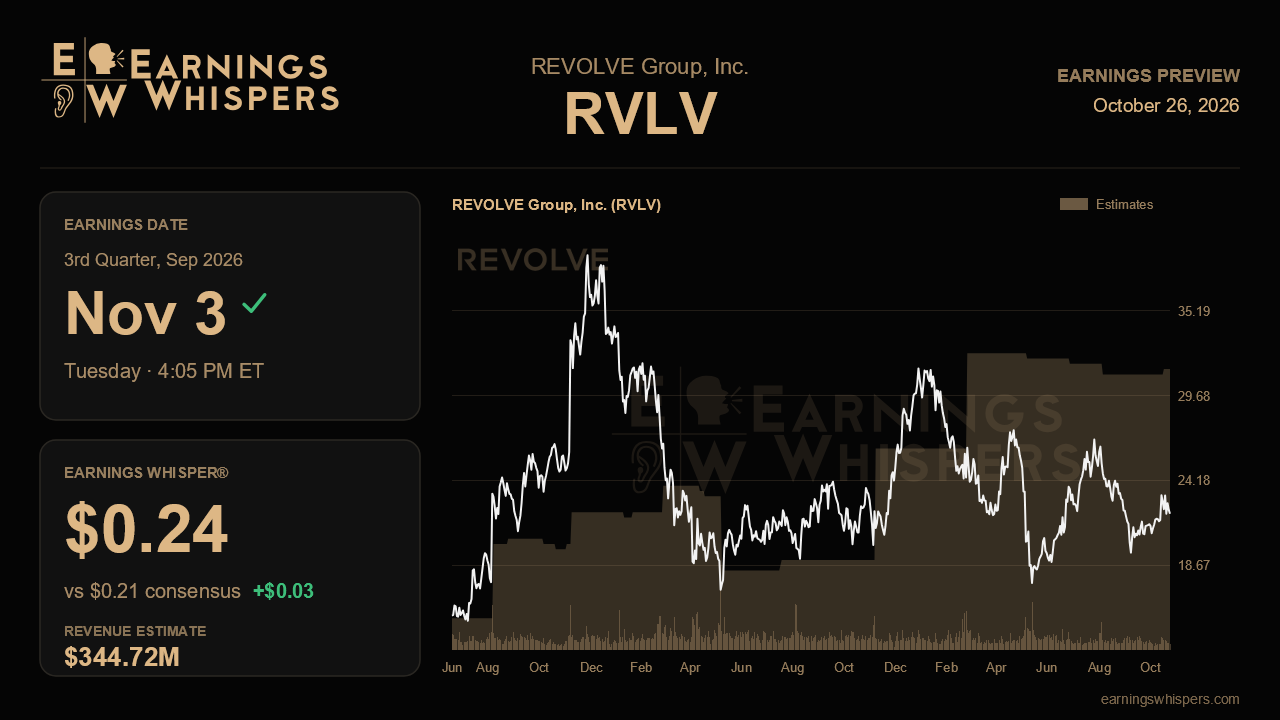
Revolve heads into its third-quarter report with a split personality. Sales and customer growth are running at their best pace in years, yet Wall Street expects earnings to shrink. That gap between top-line acceleration and bottom-line pressure is the story, and the stock's slide since the last report suggests investors are paying more attention to the second half of that equation.
Analysts are looking for earnings of $0.21 a share, down 12.5% from $0.24 a year ago, on revenue of about $344.7 million, up 16.6%. That revenue figure would be the strongest growth rate in recent memory, following gains of 10%, 16% and 12% over the past three quarters and a sluggish 4% in the year-ago period. The Earnings Whisper of $0.24 sits a few cents above consensus, implying that the more engaged crowd expects profits to roughly match last year rather than decline. That is a meaningful nudge higher in the bar for a company with earnings in the low twenties of cents.
The revenue target looks reasonable in light of what management shared last quarter. July sales were tracking up 18%, a six-point step-up from the second quarter, and active customers grew 11% to surpass 3 million on the biggest quarterly addition in four years. Consensus essentially assumes that July pace held with only modest fading through August and September. Validation would mean growth in the high teens, continued active-customer gains near or above 11%, international share holding near its record 23% of sales, and a return rate still falling year over year. A print in the low teens would suggest July was a hot month rather than a new run rate, which would undercut the accelerating-momentum narrative management built last quarter.
The profit side is where the forecast decline comes from, and much of it was telegraphed. Management guided gross margin to 53.5% to 54.0%, roughly 88 basis points below last year, because the year-ago quarter benefited from a markdown-algorithm recalibration that added about 347 basis points. On top of that, the company raised its full-year marketing guide to 15.8% to 16.0% of sales and lifted G&A to $170 million to $172 million, with roughly two points of adjusted EBITDA margin earmarked for new initiatives. Selling and distribution costs also ran hot on international fuel and logistics surcharges. The key question is whether gross margin lands inside the guided range despite heavier markdowns and firmer synthetic-fabric costs, and whether logistics expenses have eased. A miss on gross margin would raise doubts about the full-year outlook, which already relies on a tariff-refund benefit to reach the high end.
Inventory is the other tell. It was up 25% at midyear, running a bit heavy, and second-quarter free cash flow was negative $11 million. Strong fall sell-through should bring that back in line; continued bloat would point to more markdowns ahead. Early reads on the new bets also matter, including Grow Good Beauty's larger fall receipts and repeat rates, the Revolve Los Angeles label, and the Aventura store opening on schedule.
The market has not given management much credit. Shares are down about 15% since the last report against a roughly flat S&P 500, trading near $22, below the 200-day moving average of $23.57 and closer to the bottom of the post-earnings range than the top. Sentiment has improved only slightly, edging up from barely positive to modestly bullish. That leaves a setup where demand proof is partly priced in but margin fears are fully on display. If Revolve delivers high-teens growth while holding gross margin inside its range and showing that the extra spending is buying durable customers, the investment-year story stays intact. If costs outrun the sales gains, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-16 | |
| Oct-13 | |
| Sep-29 | |
| Sep-28 | |
| Sep-21 | |
| Sep-21 | |
| Sep-10 | |
| Sep-08 | |
| Aug-27 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 |
