QuidelOrtho Must Prove Its Slashed 2026 Outlook Has Found A Floor Amid China Pressure
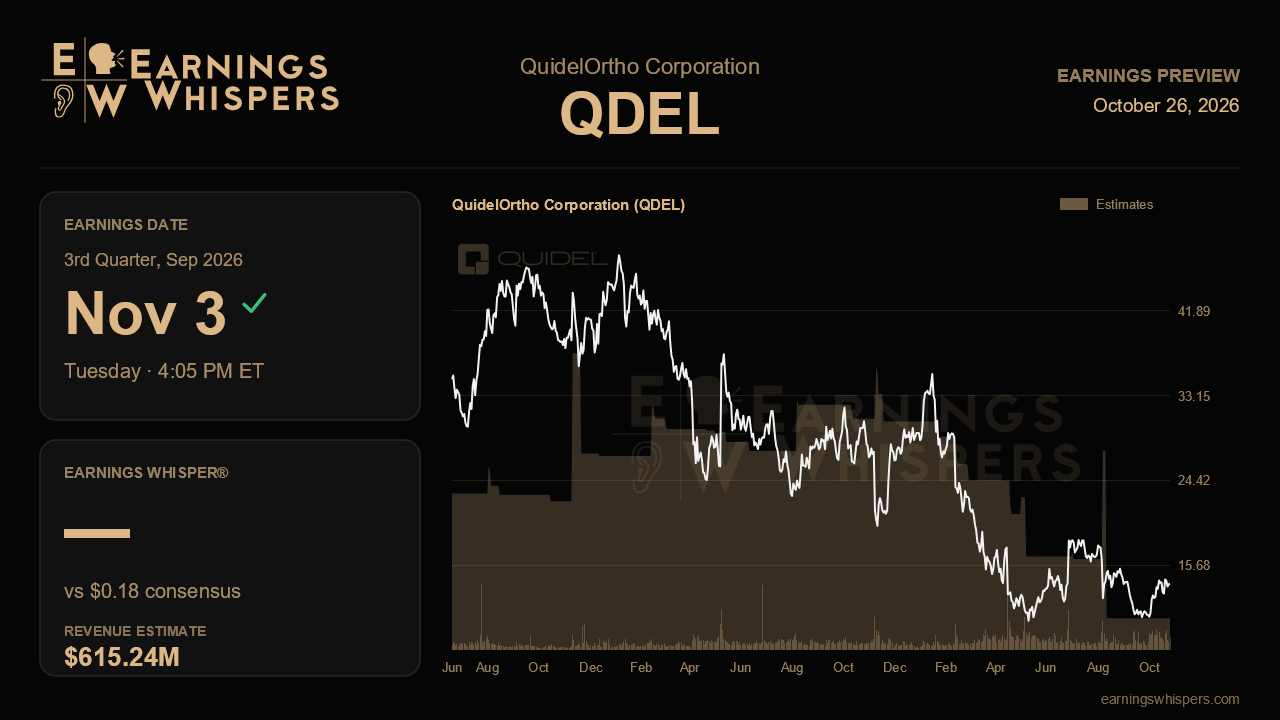
Three months ago QuidelOrtho roughly halved its 2026 earnings outlook, withdrew its free cash flow target and conceded that China pricing reform and a soft respiratory season had overwhelmed a healthy core business. The stock has since risen. That makes the third-quarter report, due after the close on November 3, less a test of whether the news is bad and more a test of whether the bad news is finally fully counted.
Wall Street expects adjusted earnings of $0.45 per share on revenue of about $615.2 million. That revenue figure would be a 12.1% decline from the $699.9 million posted a year ago, when the company earned $0.80 per share. It would also be slightly below the $630.9 million reported last quarter, when EPS came in at just $0.13. Management now guides to full-year adjusted EPS of $0.65 to $0.90 on revenue of $2.52 billion to $2.60 billion, down from $1.80 to $2.00 and $2.70 billion to $2.75 billion a quarter earlier. The published full-year consensus of $1.87 on $2.68 billion still sits well above the new range, which looks like stale estimates rather than genuine optimism. The quarterly numbers are the better guide to where expectations really are.
China is the swing factor. Revenue there fell 23% in the second quarter, a sharp reversal from the low-single-digit growth built into the original plan. Management warned that the second draft of China's diagnostic pricing guidelines was harsher than the first, with broader product scope, no differentiation by testing method and a pilot expanded from three provinces to six. Customers were also destocking faster than expected. A quarter in which China declines roughly in line with that pace, and management can describe the destocking as largely behind it, would support the idea that the guidance reset was adequate. Another leg down, or a final pricing framework worse than the June draft, would suggest the cut was not deep enough.
The other half of the story is the business that was supposed to carry the company. Excluding China, revenue grew 6% last quarter, with Labs up 9%, immunohematology up 5% and Triage up 9%. Adjusted EBITDA rose 21% and margin expanded about 310 basis points even as gross margin slipped to 44.4% on China mix. Management expects core Labs and immunohematology ex-China to grow about 3% to 5% in the second half, and the savings program of about $140 million should keep supporting margins. Respiratory testing is the wild card. The company now models a season at the low end of history, so any early strength in third-quarter shipments would be a genuine upside lever rather than something already in the plan.
Cash is where credibility will be rebuilt or lost. Operating cash flow was negative $111 million last quarter, free cash flow was negative $136 million and net leverage stood at 4.3 times. A new CFO has made cash conversion and deleveraging his focus. Signs of positive working-capital progress, or a reinstated cash flow target, would carry real weight. Questions will also linger about a press report of a possible point-of-care sale, which management declined to address.
Sentiment has improved, with bearish readings easing from 53.3% to 28.2%. The stock has gained 8.7% since the last report while the S&P 500 slipped 0.7%. At $13.77 it trades well above its post-earnings low of $9.93 but still below its 200-day average of $16.74 and short of the $15.52 high. The market has moved from capitulation to cautious repair. Holding that gain requires evidence that China's decline is stabilizing, the ex-China engine is still running at mid-single digits and cash burn is reversing. Without all three, the reduced outlook may still prove too generous.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Sep-24 | |
| Aug-27 | |
| Aug-06 | |
| Aug-06 | |
| Jul-24 | |
| Jul-23 | |
| Jul-15 | |
| Jul-01 | |
| Jun-29 | |
| Jun-23 |
