SM Energy's Rally Raises The Bar As Investors Await Proof The Civitas Flywheel Keeps Turning
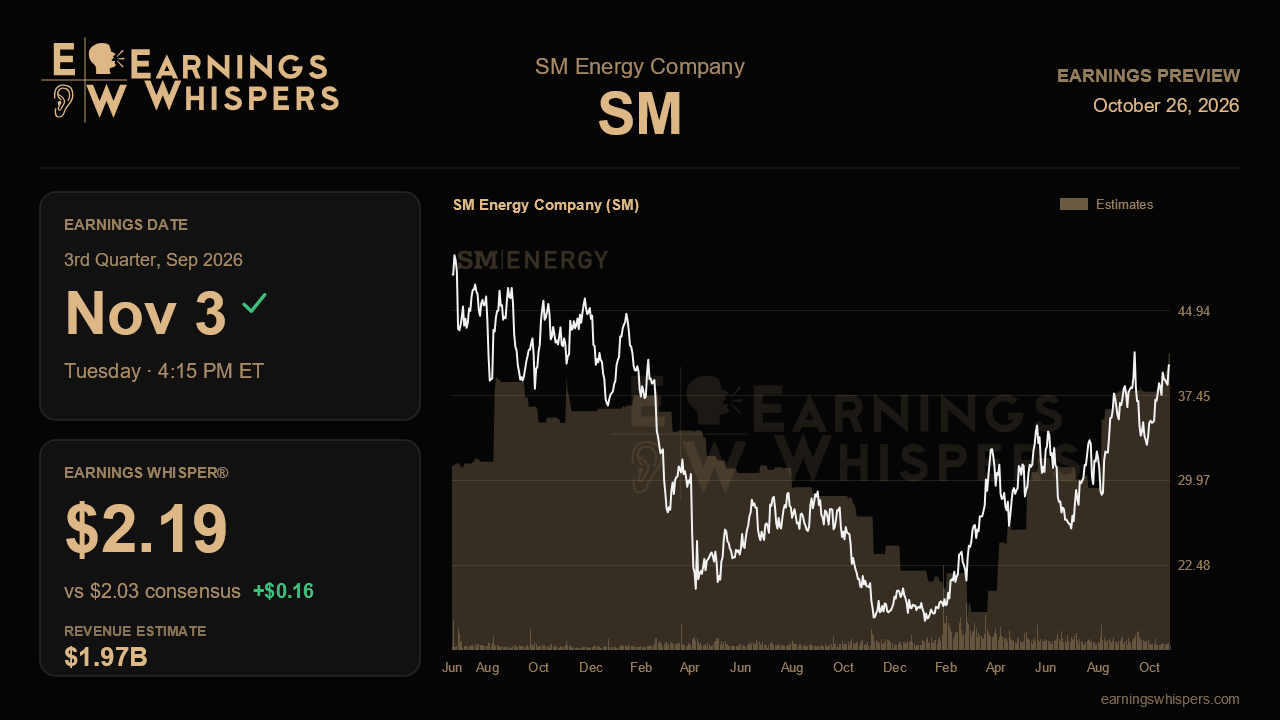
SM Energy enters its third-quarter report with the stock up more than 31% since its last update, while the broader market has gone essentially nowhere. That rally leaves one question hanging over the November 3 release, due after the close: can a company that has spent three straight quarters raising targets on the Civitas integration keep supplying fresh evidence, or has the easy part of the story already been priced in?
The Street is looking for earnings of $2.03 a share on revenue of about $1.97 billion. Against the year-ago quarter, which predates the combined SM/Civitas platform, those figures imply EPS growth of roughly 53% and revenue growth of about 143%, numbers that mostly reflect the merger rather than organic acceleration. The more telling comparison is sequential. Consensus sits below last quarter's $2.19 in EPS and well below its $2.50 billion in revenue, a step down that should partly reflect the absence of the divested Galvan assets in South Texas. The Earnings Whisper of $2.19 is meaningfully above consensus and matches last quarter's result, which suggests the more engaged crowd expects SM to hold its earnings level rather than slip.
Production is the cleanest test. Management raised its second-half outlook to 435 to 440 MBoe/d, with about 238 Mbo/d of oil, after earlier framing roughly 430 and originally 420 to 430. Second-quarter output already ran near 440, so a third quarter at or above the top of that range would confirm that the raise was conservative, especially with the Miracle pad in the Uinta coming online in September. Because management has said the second-half average is now the cleaner modeling baseline, any print near the bottom of the range would invite questions about whether the Galvan sale removed more volume than expected. Equally important is the Uinta efficiency story: completion speeds above 2,600 feet a day and more than $1 million per well in drilling and completion savings should begin showing up in capital efficiency, not just in slide decks.
Costs are the second pillar. With about $355 million of the $375 million synergy target already actioned, the remaining upside is modest, so the focus shifts to whether those savings and the roughly $50 million reduction in recurring G&A appear in reported unit costs. Management described the G&A cut as durable; a quarter that confirms that would support the argument that SM's improvement is structural rather than a byproduct of commodity prices.
Capital allocation is where the narrative could gain a new chapter. Net debt fell about $1.1 billion last quarter to roughly $6.25 billion, the 2026 notes were redeemed and the 2027 notes called, leaving nothing in senior maturities until mid-2028. Buybacks of $84 million marked a start, but they remain capped at the 20% minimum until leverage reaches the low 1x range at mid-cycle pricing. Management has also acknowledged recent pricing ran above mid-cycle, so investors should look for continued debt reduction and any signal on how close that leverage trigger is. Early color on the still-unquantified 2027 plan would also help, given that activity has been held flat by design.
Sentiment is mildly bearish and essentially unchanged from last quarter, an odd backdrop for a stock trading about 35% above its 200-day moving average and only a few percent below its post-earnings high of $41.56. That combination suggests skepticism has not caught up with the price, but it also means the shares lack much of a cushion. The report ultimately needs to show that SM's gains are coming from execution it controls, namely volumes at the top of guidance, costs that stay down and a balance sheet nearing the point where buybacks can accelerate. If it delivers that, the flywheel story holds; if results lean on price alone, the rally will look ahead of itself.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-05 | |
| Aug-24 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-23 | |
| Jul-08 | |
| Jul-08 | |
| Jun-02 | |
| Jun-01 | |
| May-28 | |
| May-26 |
