LendingTree's SMB Slump Faces A Key Test As Shares Sit Near Post-Earnings Lows
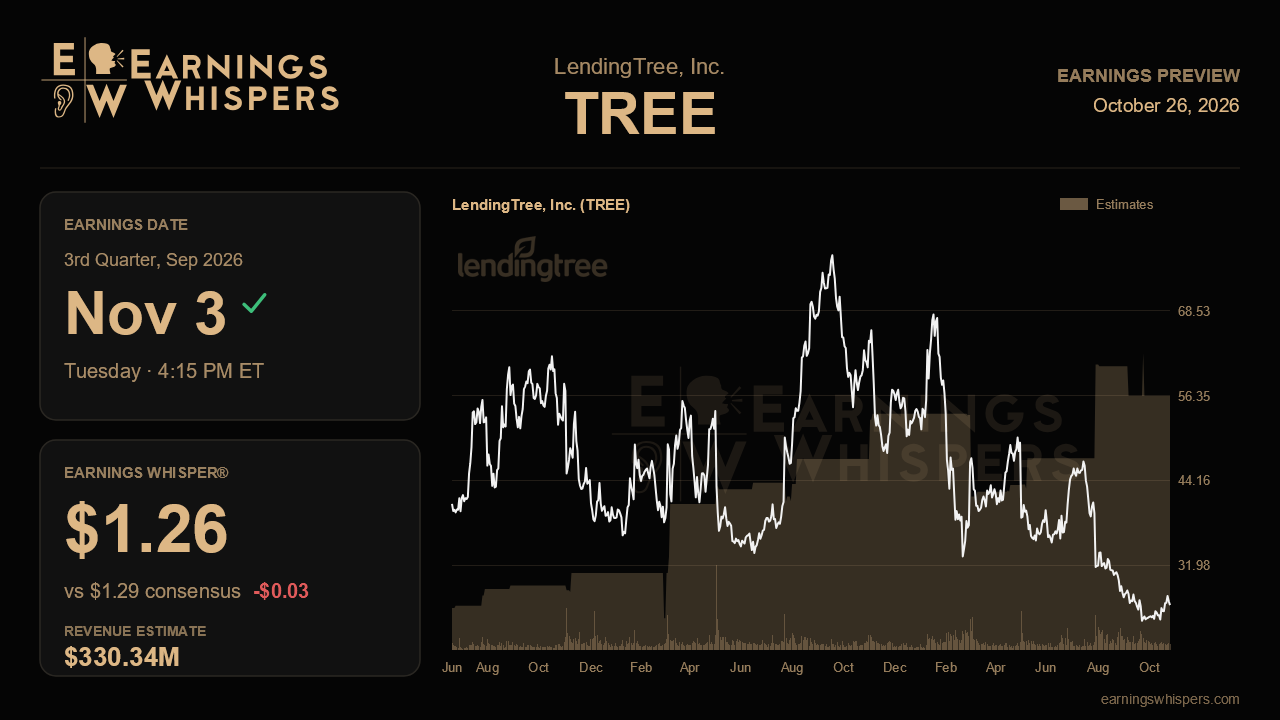
LendingTree heads into its third-quarter report with a straightforward question hanging over the stock: was last quarter's stumble in small business lending a temporary macro hiccup, as management insisted, or the start of a longer slowdown in what had been its fastest-growing profit engine? The market has clearly leaned toward the second view. Shares have fallen 15.3% since the July report while the S&P 500 gained 4%, and at $26.25 the stock sits much closer to the $23.50 low of its post-earnings range than the $34.17 high, well below a 200-day moving average near $38.89. That entire range sits beneath the prior quarter's $34.50 floor, which tells you how sharply sentiment reset.
The Street is looking for non-GAAP earnings of $1.29 per share on revenue of $330.3 million when the company reports after the close on November 3. The revenue figure lands squarely at the midpoint of management's $325 million to $335 million guidance, and it has slipped from earlier estimates near $337 million, so analysts have already walked their numbers back toward the company's own outlook. The whisper number of $1.26 sits a touch below consensus, a small gap but one consistent with a crowd that is not expecting heroics. Expected revenue growth of 7.3% is modest, and it marks a notable cooling from the roughly 25% top-line growth posted in the second quarter. Earnings are also expected to come in slightly below the $1.34 reported a year ago.
The guidance context matters here. Management narrowed its full-year revenue range to $1.30 billion to $1.32 billion from $1.30 billion to $1.35 billion, effectively lopping off the top. Executives acknowledged that the company would have been tracking toward the high end of the old range had small business lending hit its budget. Small business had beaten plan by about 15% in the first quarter before lender appetite and merchant demand both pulled back, with smaller loan sizes, lower close rates and lighter volume. The revised outlook assumed lenders return but merchants do not. Management pointed to July as the best sales month since the first quarter, so this report should show whether that rebound held through August and September. Stabilizing consumer segment profit, or any sign of merchant demand recovering, would validate the temporary framing. Another sequential decline would undercut it and raise doubts about the fourth-quarter math.
Insurance is the other half of the story. Revenue there jumped 42% in the second quarter, but variable marketing margin compressed to the mid-20s percent range as Google traffic costs rose and carriers competed aggressively for advertising. Growth is getting harder against the strong insurance recovery that began a year ago, so the more telling signal may be whether margins hold or erode further. Home lending improved modestly last quarter, yet management built no upside into guidance given elevated mortgage rates, which leaves room for a pleasant surprise rather than a likely source of disappointment.
There are offsetting positives that could support the stock if the core numbers cooperate. Net leverage fell to 1.9 times, opening the door to buybacks and acquisitions for the first time, and free cash flow runs around $80 million a year. Any detail on capital returns would carry extra weight with shares this depressed. Early reads on the ChatGPT mortgage tool, six new products and the homepage redesign, which lifted sessions 11% and form starts 18%, will help show whether the product push is translating into revenue. The Google antitrust arbitration is a long-dated wildcard rather than a quarterly driver.
Sentiment remains bearish, though less so than heading into the last report, suggesting some of the pessimism has already been absorbed. Ultimately, the verdict rests on small business. If merchant demand shows signs of life and the full-year range holds, the July selloff may look overdone. If management leans toward the low end again or pushes the recovery further out, the market's skepticism will have been justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours |
Some U.S. Industries Saw Wages Jump Nearly 17%. But Their Industries Have Been Shedding Jobs.
TREE
International Business Times
|
| Oct-26 | |
| Oct-24 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Sep-16 | |
| Sep-16 | |
| Sep-08 | |
| Sep-04 | |
| Aug-28 | |
| Aug-25 | |
| Aug-14 | |
| Aug-08 |
