Triple Flag's Q3 Tests Whether Top-Half GEO Guidance Survives Cerro Lindo Step-Down
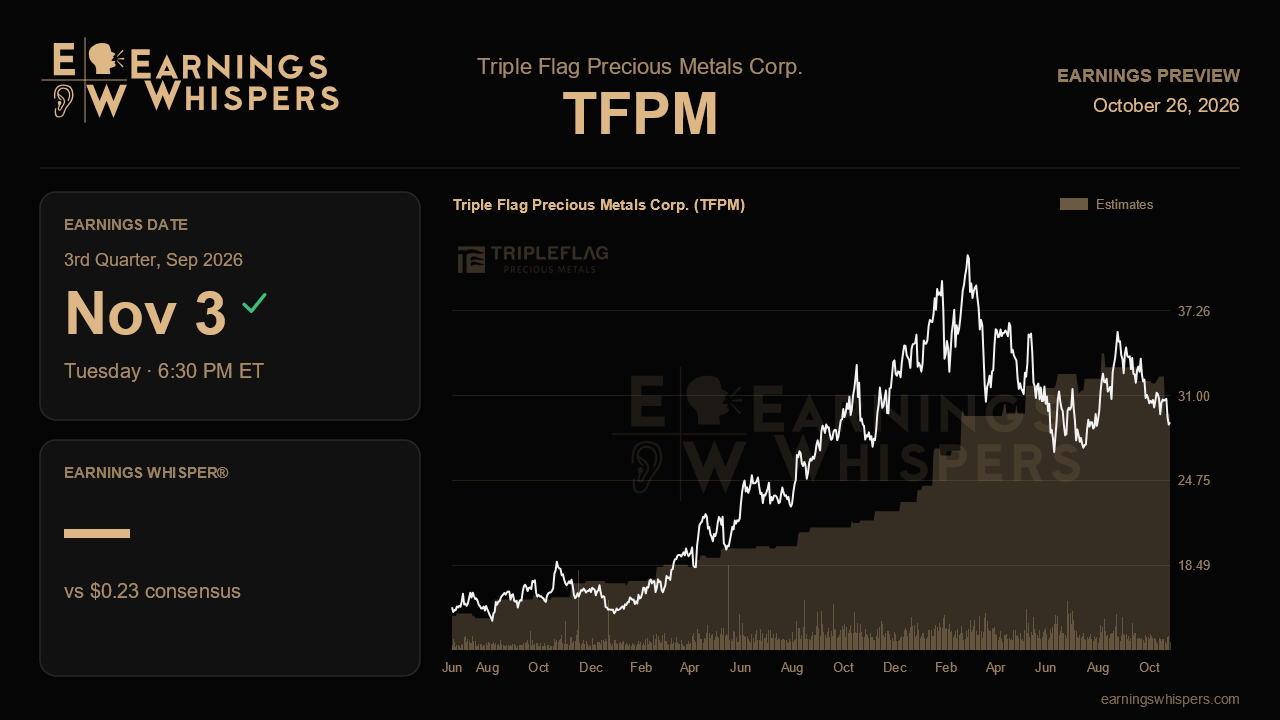
Triple Flag Precious Metals heads into its third-quarter report with an odd disconnect between its narrative and its scorecard. Three months ago, management told investors that 2026 gold equivalent ounces were tracking to the top half of an already raised range, bought back stock aggressively and lifted the dividend again. Yet Wall Street is modeling a quarter that looks flat to slightly down from a year ago, and the shares have slid since the last update. The report, due after the close on November 3, needs to show which of those two stories is closer to the truth.
Consensus calls for earnings of $0.23 a share, roughly 4% below the $0.24 earned in the same quarter last year and well below the $0.39 posted last quarter on revenue of $129.2 million. That sequential drop is the number to understand. Part of it is mechanical: the Cerro Lindo stream stepped down to a lower delivery rate in the second half after hitting its 19.5 million ounce silver threshold, a change management had flagged for some time. North Parks mine sequencing is also a known drag on 2026 relative to the record 113,000 GEOs delivered in 2025. The Street appears to be baking those headwinds in fully, which leaves room for upside if new contributors fill more of the gap than expected.
The main candidate for filling that gap is Ravenswood, which management folded into its full-year outlook as a second-half contributor. Guidance began the year at 95,000 to 105,000 GEOs, moved up to 100,000 to 110,000, and was then steered toward the upper half of that band. Having raised the bar twice, the company now has to deliver against it. Third-quarter volumes that keep the full year on pace for at least 105,000 GEOs would validate the August tone; anything that implies a heavy fourth-quarter catch-up would invite skepticism. Smaller but useful signals include whether Impala builds on its $10.5 million contribution as Steeldrift begins to lift volumes, and any update on Tereska phase 2, where an expansion could double or triple a nameplate of roughly 20,000 tonnes a year.
Capital allocation is the second test. Cash fell from $144 million at the end of the first quarter to management's $10 million to $15 million working floor after a $20 million buyback and Prieska-related spending. The company is debt-free with access to its credit facility, so this is a choice rather than a strain, but it changes the math. With the deal pipeline described as the most robust in the company's history, including some transactions above the usual $100 million to $500 million size, investors will want to know how new deals would be funded, whether buybacks continue, and how management is thinking about its right, but not obligation, to fund the Prieska deeps stream, which holds more than 95% of that asset's economics. Glencore's financing of the upper zone helps de-risk the eventual decision. The ATO/Step Gold litigation remains outside guidance and is a lower-order issue.
The market has not been generous. The stock is down about 7% since the last report against a 1.4% dip for the S&P 500, and at $29.04 it sits below its 200-day moving average of $32.92 and near the bottom of its post-earnings range of $28.45 to $35.93. Sentiment remains bearish, though slightly less so than heading into the last report. That combination of improving operating commentary and a sagging share price sets a relatively low emotional bar.
Ultimately, this quarter comes down to whether Ravenswood and the rest of the portfolio can absorb the Cerro Lindo step-down well enough to keep the top-half GEO target credible. If they do, the recent selloff looks like an overreaction to known headwinds. If volumes lag and the funding plan for a busier deal slate stays vague, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-07 | |
| Sep-09 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-21 | |
| Jul-09 | |
| Jun-15 | |
| Jun-12 | |
| Jun-12 | |
| Jun-11 | |
| May-25 | |
| May-12 |
