SSR Mining's Cash Pile Is Settled; Now Costs And Free Cash Flow Face The Test
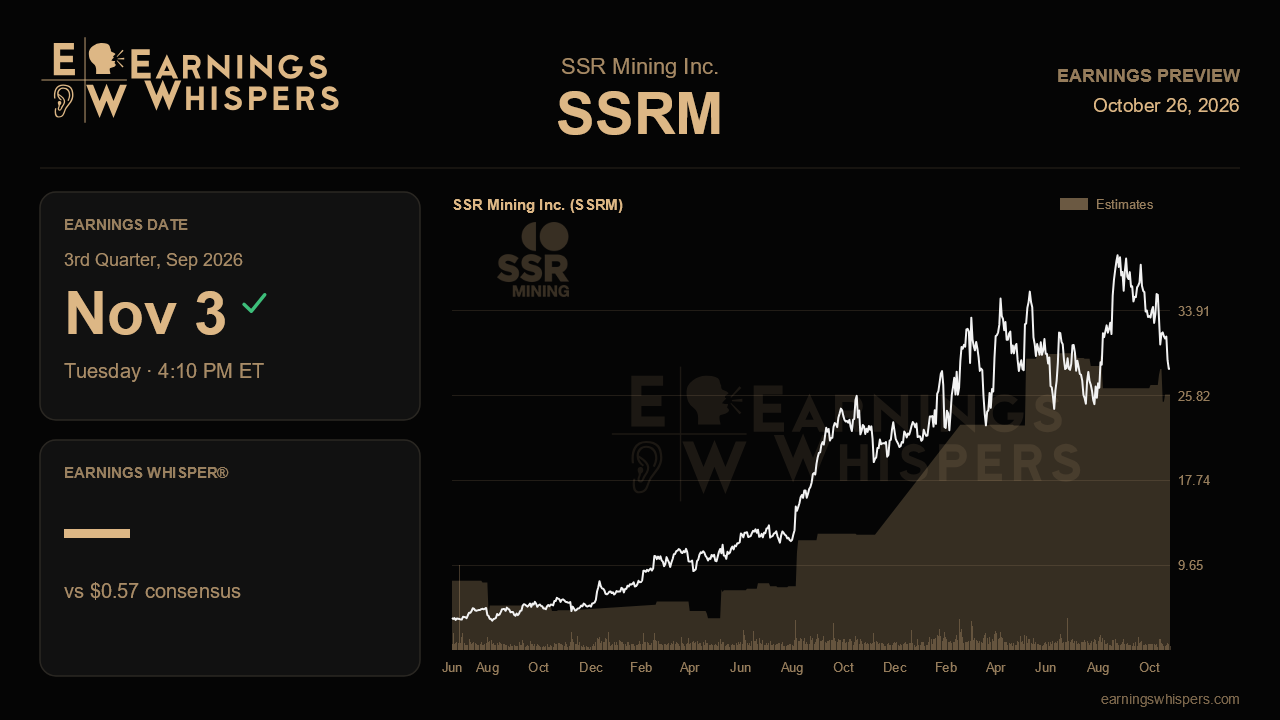
SSR Mining enters its third-quarter report as a very different company from a year ago. The Turkish exit is complete, roughly $1.8 billion in cash sits on a debt-free balance sheet, and shareholders are receiving a reinstated dividend alongside a $500 million buyback. The strategic story is largely finished. What remains open is whether the slimmed-down Americas portfolio can turn high metal prices into clean, repeatable cash flow while unit costs creep toward the top of guidance. The November 3 release, due after the close, is the first full quarter to answer that question.
The Street expects earnings of $0.57 a share, up about 78% from $0.32 a year earlier. That is strong annual growth, but it also implies a step down from the $0.66 earned last quarter. The sequential dip matters. Analysts appear to be pricing in the same pressures management flagged in the summer: higher realized fuel costs, Argentine inflation at Puna, and heavier sustaining capital spending, which the company lifted by roughly $25 million to $35 million to about $230 million to $235 million for the year. A result near consensus would suggest those headwinds are behaving as advertised rather than getting worse.
Costs are the main swing factor. Last quarter management moved full-year all-in sustaining cost guidance to the upper end of its range, with Marigold, CC&V, Seabee and Puna all trending toward the top. That was a notable shift from the prior quarter, when the company described itself as on track. Second-quarter unit costs climbed roughly 8% from the first quarter as production slipped from about 110,000 to 102,000 ounces. A third quarter that shows volumes recovering and costs stabilizing would support the view that the drift was a temporary blip. Another sequential rise, or any hint that costs could exceed the range, would challenge it. Seabee merits particular attention, since it was already tracking the low end of production guidance, and a further shortfall there would weigh on both output and unit costs.
Free cash flow is the second test. Continuing operations generated only about $50 million last quarter, held down by more than $120 million in cash taxes and an inventory build, compared with $211 million in the first quarter. If those items were largely timing effects, the third quarter should show a meaningful rebound. That rebound matters because the capital return program and the accelerated growth spending at Marigold, where growth capital rose from $48 million to $65 million, and Seabee's Porky West, raised from $15 million to $35 million, both lean on cash generation rather than only the divestment proceeds. Updates on buyback pace, the Phenom Resources stake and the Marigold technical report, now promised by year-end, will round out the picture. Any commentary on 2027 fuel exposure, as diesel hedges roll off and cost sensitivity roughly doubles, could shape the outlook more than the quarter itself.
The market's stance is mixed. Sentiment remains slightly bearish but has improved from the prior quarter. The shares are up about 4% since the last report, beating a slightly lower S&P 500 by roughly five points, yet that headline gain hides a sharp fade. After reaching $39.44, the stock has fallen to $28.38, below its 200-day moving average and only about 4% above its post-earnings low of $27.30. Much of the post-Turkey enthusiasm has evaporated, which lowers the bar somewhat but also signals investor doubts about the cost story.
The balance sheet no longer needs proving. The open question is whether the operating business can earn its keep. If SSR shows production recovering, costs holding at the top of the range rather than breaking above it, and free cash flow rebounding, the transformation narrative stays intact. If costs keep rising and cash generation stays muted, the stock's recent slide may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-06 | |
| Sep-24 | |
| Sep-23 | |
| Sep-16 | |
| Sep-16 | |
| Sep-14 | |
| Sep-10 | |
| Aug-26 | |
| Aug-26 |
