Varonis Must Show Slipped Deals And AI Products Can Carry Its Raised SaaS Outlook
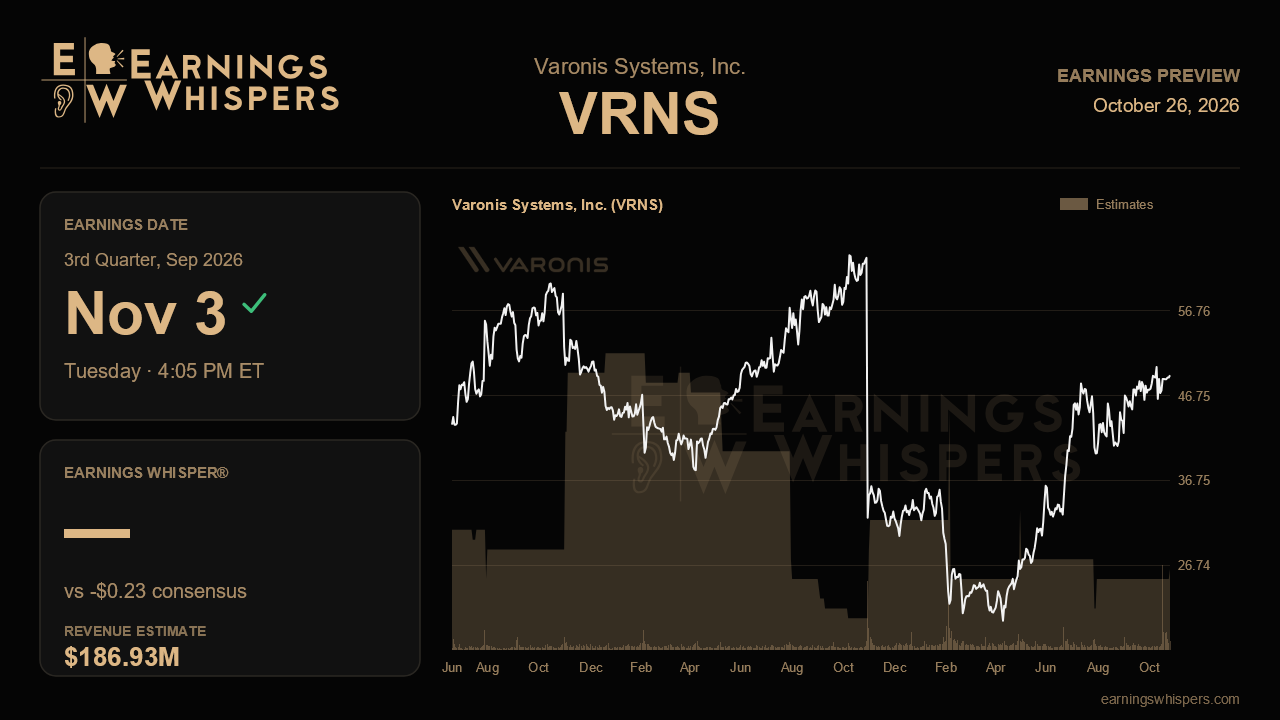
Varonis heads into its third-quarter report with a story that has quietly flipped from repair to offense. A year ago the company was absorbing an on-premises renewal shock and cutting guidance. Now the end-of-life transition is largely priced in, management has raised its SaaS targets for a second straight quarter, and the stock has run to the top of its recent range. The question for Tuesday's report is whether the operating evidence can keep pace with that improved mood, particularly after several large deals slipped out of the second quarter amid media chatter about a possible transaction.
Wall Street expects revenue of about $186.9 million, up roughly 15.7% from a year ago, and a GAAP loss of $0.24 a share, slightly narrower than last quarter's $0.26 loss but wider than the $0.20 loss of the year-ago period. That revenue figure sits just above the midpoint of management's $185 million to $188 million forecast, so the Street is asking for a solid, not heroic, result. On an adjusted basis, management guided to earnings of $0.02 to $0.03 a share, and the full-year outlook was lifted to $735 million to $739 million in revenue and $0.14 to $0.15 in adjusted earnings. The widening GAAP loss compared with last year reflects the margin cost of moving customers to SaaS: gross margin slipped to 77.7% last quarter from 80.6% a year earlier, and ARR contribution margin fell to 13.3%. Management framed both declines as planned, so stability here would be reassuring, while further erosion would raise questions about how long the transition tax lasts.
The more important numbers sit beneath the income statement. Management raised its full-year target for SaaS ARR excluding conversions to $769 million to $775 million, implying about 21% growth, up from an initial 18% to 20% range. Each raise lifts the bar, and this quarter should show whether that trajectory holds. Some of the deals that slipped in late June, including a seven-figure contract, closed in July, which should give the quarter a tailwind. A strong print would partly reflect that timing, so the cleaner signal will be whether new-logo growth stays above the 20% pace reported last quarter and whether management sounds confident that transaction speculation is no longer stalling large buyers.
Conversions are the other swing factor. The company is tracking toward the low end of its $50 million to $75 million conversion range, having moved only about half of what it expected in the first half. Reaching the midpoint would require converting roughly two-thirds of the remaining target in the back half, a demanding pace. Visible progress would support the total SaaS ARR guide of $819 million to $850 million; another shortfall would point toward the bottom of that range even if new business stays healthy. Free cash flow, guided to $105 million to $110 million against $69.1 million year to date, offers a further check on second-half execution.
The newer products are where the growth story has to prove itself. Atlas, acquired with Altru, had only a few months in market last quarter but already beat internal hopes, and management expects a larger second-half contribution. Database activity monitoring is pitched as a displacement play against Imperva and IBM Guardium, and Interceptor email security is meant to attach to the managed detection base. Concrete customer counts or pipeline conversion would turn AI-security enthusiasm into something measurable. Federal remains excluded from the outlook, so any upside there would be a bonus.
Expectations are mixed. The shares have gained about 15% since the last report, beating the S&P 500 by nearly 12 points, and at $49.15 trade well above the 200-day average and within about 2% of the post-earnings high of $50.31, effectively testing a breakout. Yet sentiment has cooled sharply, falling to about 10% bullish from 45% heading into the prior report. That gap suggests a rally fueled partly by transaction talk rather than conviction in the fundamentals. The report will be judged on one thing: whether SaaS ARR growth, helped by July closings and early Atlas and DAM traction, is strong enough to justify yet another raise while conversions catch up.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Sep-21 | |
| Sep-15 | |
| Sep-15 | |
| Sep-11 | |
| Sep-11 | |
| Sep-11 | |
| Sep-02 |
