Unum's Third Quarter Tests Whether Life And Colonial Strength Can Keep Covering Disability And UK Leaks
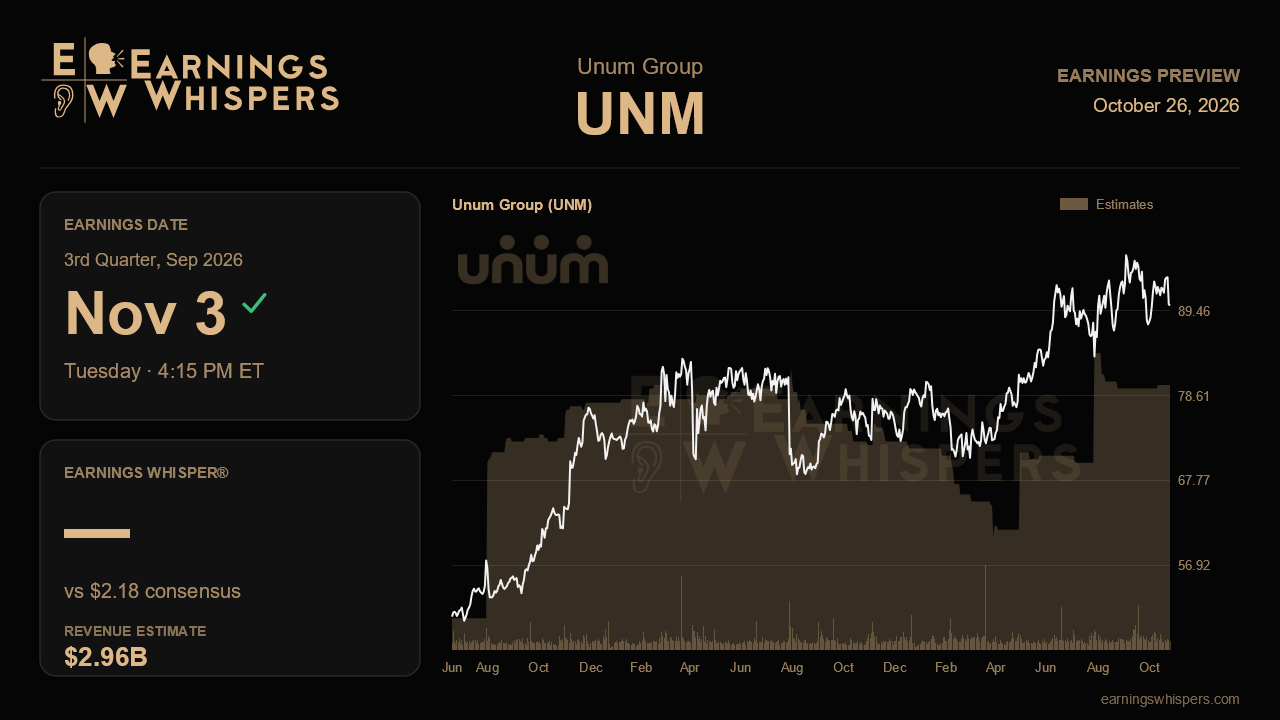
Unum Group heads into its third-quarter report with a balancing act that has become the whole story. Last quarter, a booming sales engine, record Colonial Life profits and unusually benign group life mortality did just enough to offset two genuine trouble spots: rising short-term disability claims in newer paid family and medical leave states, and a sharp deterioration in UK group income protection. Management held its full-year outlook steady, but it also warned that both problems would linger through the back half. This report shows whether the offsets are still winning.
The Street is looking for adjusted earnings of $2.18 a share, up 4.3% from $2.09 a year ago and only a hair above the $2.16 posted last quarter. That is modest growth, consistent with a company grinding forward rather than accelerating. Revenue is pegged at $2.96 billion, a 12.4% drop from the prior year, which looks jarring next to underlying core premium growth that management said was running near 5%. Investors would be wise to focus on premium trends and segment margins rather than the headline revenue figure, which may reflect how estimates are handling the closed-block reinsurance activity. On the full year, consensus of $8.74 sits almost exactly at the midpoint of management's reaffirmed $8.60 to $8.90 range, so the Street is not betting on either a stumble or an upside surprise.
The most important number may be the US group disability benefit ratio. It ran at 65.8% last quarter, above the 62% to 64% expected range and well above the 61.3% of a year earlier, with roughly two points of pressure tied to leave-state claims. Management has said double-digit rate increases will mostly take effect on January 1, 2027, so no repair is expected yet. The real question is containment: a ratio holding in the mid-60s would validate the idea that this is an isolated, priceable issue, while further drift higher would suggest the problem is broadening. The same logic applies to the UK, where the benefit ratio jumped to 82.2% against a 70% to 72% target and international operating income slid to $24.3 million. Pricing fixes there largely arrive in 2027, so another quarter near those levels is tolerable, but a further step down would strain the cushion.
That cushion lives mainly in two places. Group life and AD&D ran at a 66% benefit ratio, and management now expects roughly that level for the rest of the year rather than its historical 68% to 72% band. Colonial Life delivered $131.4 million in operating income with a 46.7% benefit ratio, beating its own guide. Any normalization in either would expose the disability and UK weakness quickly. On the growth side, US sales were up 14.3% year to date and group persistency reached 91.5%; evidence that HR Connect and Total Leave products keep pulling in business would support the longer-term premium story.
Investors will also want an update on the $3.8 billion Fortitude Re long-term care deal, slated to close in the fourth quarter, including how management frames the expected $90 million to $100 million quarterly GAAP drag afterward, and progress toward roughly $1.3 billion of capital deployment for the year after about $750 million through June.
The market has been generous anyway. Shares have climbed 7.9% since the last report, beating the S&P 500 by 4.5 points, and at $90.12 they sit comfortably above the 200-day average of $83.74, though still about 7% below the post-earnings high of $96.77. Sentiment has cooled noticeably, slipping to mildly bullish from a more confident reading before last quarter, suggesting a stock priced for stability rather than excitement. Ultimately, the narrative survives if disability and UK pressures hold flat while life and Colonial stay strong; if the leaks widen faster than the offsets, the midpoint of guidance starts to look less secure.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-15 | |
| Oct-07 | |
| Sep-16 | |
| Aug-27 | |
| Aug-26 | |
| Jul-28 | |
| Jul-28 | |
| Jul-13 | |
| Jul-09 | |
| Jul-06 | |
| Jul-06 | |
| Jul-01 | |
| May-28 | |
| May-21 |
