Transcat's Service Surge Faces Its First Real Test As Bearish Sentiment Builds
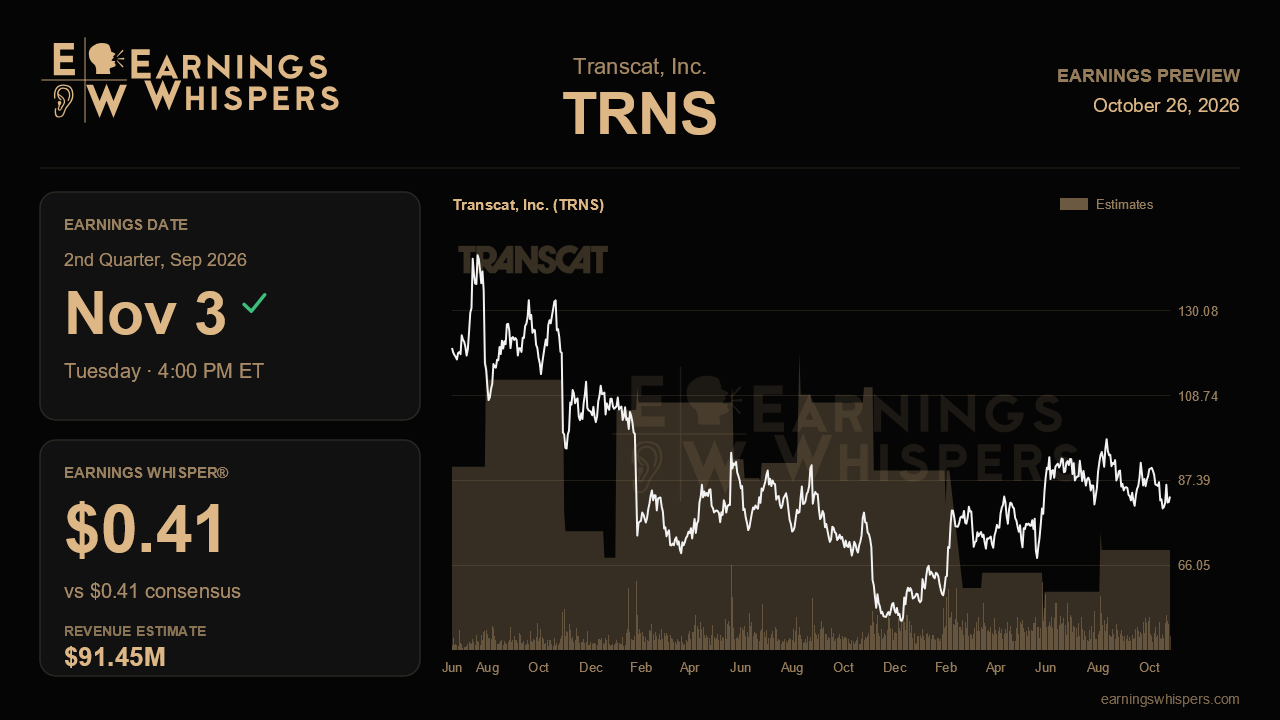
Last quarter Transcat delivered the kind of report that turns skeptics into believers: service organic growth nearly doubled to 13%, service gross margin returned to year-over-year expansion after a long slide, and a new chief executive sounded noticeably more assured about the year ahead. Yet the stock has slipped since then, and sentiment has soured sharply. That gap between improving fundamentals and a cooling market is what makes the fiscal second-quarter report, due after the close on November 3, worth close attention.
The Street is not asking for much on the bottom line. Consensus calls for earnings of $0.41 per share, down about 7% from $0.44 a year ago, on revenue of roughly $91.5 million, up a little more than 11%. The Earnings Whisper sits right at consensus, so there is no hidden bar above the published number. The revenue forecast implies a meaningful slowdown from the 22% consolidated growth posted last quarter and a slight sequential dip from $92.9 million, which likely reflects acquisition contributions lapping and a more normal pace of organic gains. Earnings contracting on double-digit sales growth tells you the market expects margin and below-the-line pressure to persist, from tougher distribution comparisons to heavier amortization, interest and transition costs.
The heart of the report is whether the service engine can hold its new altitude. Management did not raise its formal outlook, but it firmed its language, saying it could confidently deliver high-single-digit service organic growth and service gross margin expansion for the full fiscal year. That shift in tone matters because it set an implicit floor. A second quarter of organic growth in the low double digits would suggest the share gains management described, which it attributed partly to softness at legacy competitors, are durable rather than a one-quarter spike. A drop back to the mid-single digits would not break the full-year promise, but it would make last quarter look like an outlier. Equally important is service gross margin. The 90 basis point improvement came as onboarding costs for new customers normalized and operating leverage kicked in; another quarter of year-over-year expansion would validate the new CEO's operational-excellence agenda built on Lean practices, pricing and mix analytics, and AI-driven productivity.
Distribution is the known soft spot. Gross margin there fell 380 basis points to 31.4% last quarter against unusually rich vendor rebates a year earlier, and segment operating income dropped 12%. Management flagged that comparisons would stay tough through the year, so another decline is not news by itself. What would matter is evidence of demand weakness rather than a rebate hangover, such as rental growth slowing from its high-single to low-double-digit pace. On the GAAP line, the size of lingering CEO-transition expenses and whether the tax rate settles toward the guided 31% to 32% range will shape how clean the quarter looks. Cash flow deserves a glance too, after operating free cash flow improved by $5.8 million last quarter.
The mood heading in is far gloomier than three months ago. Bearish sentiment has climbed to 47% from about 15%, and the stock is down roughly 4% since the last report, trailing the S&P 500 by around three points. At $83.33, shares sit just above the 200-day moving average and near the bottom of a post-earnings range stretching from about $79 to $100, a sign that last quarter's enthusiasm has largely drained away.
That sets up a fairly clear test. If service organic growth stays well above the high-single-digit framing and service margins keep expanding, the quarter would confirm that Transcat's recurring calibration business has genuinely inflected, and the modest earnings bar becomes easy to clear on quality. If service momentum fades back toward its prior pace while distribution margins keep sliding, the market's growing doubts will look justified, regardless of where the headline EPS lands.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Aug-31 | |
| Aug-27 | |
| Aug-05 | |
| Aug-04 | |
| Jul-16 | |
| Jun-22 | |
| May-27 | |
| May-26 | |
| May-18 | |
| Apr-09 | |
| Mar-09 | |
| Feb-12 | |
| Feb-10 |
