Gaia's Cash Runway And Revenue Floor Face A Hard Test After A Bruising Quarter
Three months ago, Gaia told investors that the third quarter would mark the bottom of a revenue slide that few saw coming a year earlier. The upcoming report, due after the close on November 2, is the first real chance to check that claim. It arrives with the company's cash balance thinned to $5.3 million and its profitability promise already scaled back. For a subscription streamer whose story once rested on growth paired with expanding margins, this quarter is less about upside and more about whether the floor holds.
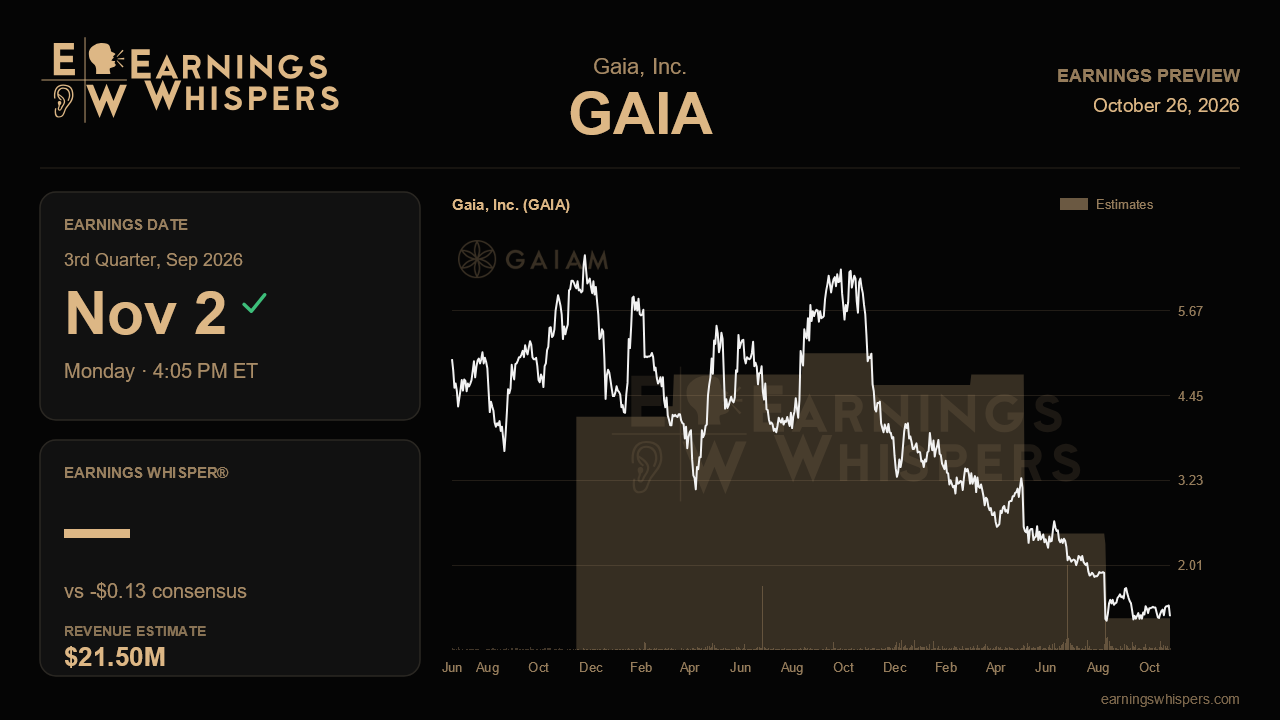
The Street is bracing for a rough print. Consensus calls for a loss of $0.13 per share, worse than the $0.05 loss a year ago and slightly wider than last quarter's $0.12. Revenue is expected at $21.5 million, a contraction of nearly 14% from the $25.0 million reported in the year-ago period. That figure deserves attention. Management characterized the third quarter as roughly similar to the second, when revenue came in at $23.3 million and fell 5% year over year. The consensus estimate implies a meaningful sequential drop and a steeper annual decline than management's framing suggested. Analysts either doubt the bottoming call or are pricing in lingering damage from the customer acquisition problems flagged last quarter. A result closer to the low $23 million range would validate management and beat a skeptical bar. A number at or below consensus would suggest the decline is still gathering speed.
The backdrop explains the caution. Over four calls, Gaia's outlook moved from low double-digit growth, to a flat lull, to an outright decline. Its target of breakeven net income in the fourth quarter has been replaced with a more modest goal of positive free cash flow. Gross margin has slipped each quarter, from 87.6% to 86% to 85.3%, as fixed content costs weigh on shrinking revenue. Another step down would show that cost cuts are not keeping pace with the top line. Stabilization near 85% would hint that the erosion is leveling off.
The operational questions are specific. Management blamed an April and May spike in acquisition costs on an algorithm change at a major advertising partner. That exposed a heavy reliance on a single channel, so evidence that marketing efficiency has normalized matters a great deal. The pullback from Latin America drove much of the international weakness, and investors will want to know whether that drag is fading. On the positive side, the company identified more than $3 million in annualized savings from its late-February cost review. Those savings should start showing up clearly in operating expenses. Management also said its churn and revenue-per-member improvement framework remains on track. Its newer engagement tools, including AI-driven tarot and horoscope features, short-form discovery clips, and a community circle product slated for a fourth-quarter launch, need to begin translating into retention data rather than anecdotes. The Jim Curtis series debuted in October, so commentary on early viewership could shape fourth-quarter expectations.
Cash may be the single most important line. The drop from $13.1 million to $5.3 million in one quarter, along with talk of a $10 million credit line as a backstop, changed the risk profile. A further large draw would make the fourth-quarter free cash flow goal look shaky and raise financing concerns.
The market has already rendered a harsh verdict. Shares have fallen about 20% since the last report while the S&P 500 was roughly flat. At $1.28, the stock trades far below its 200-day average of $2.38 and near the bottom of its post-earnings range of $1.16 to $1.79. That entire range sits beneath the prior quarter's low of $1.82. Sentiment readings have also turned more bearish than before the last report. Expectations are low, but low expectations only help if the balance sheet stops bleeding. The report will be judged on whether revenue truly stabilizes and cash burn slows enough to make the free cash flow target credible.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Aug-11 | |
| Aug-10 | |
| Aug-06 | |
| Jul-27 | |
| Jun-17 | |
| Jun-16 | |
| Jun-10 | |
| Jun-09 | |
| May-11 | |
| May-04 | |
| Apr-27 | |
| Apr-06 | |
| Mar-20 |
