Alamo Group's Vegetation Recovery Faces Order Test As Shares Slide Toward Lows
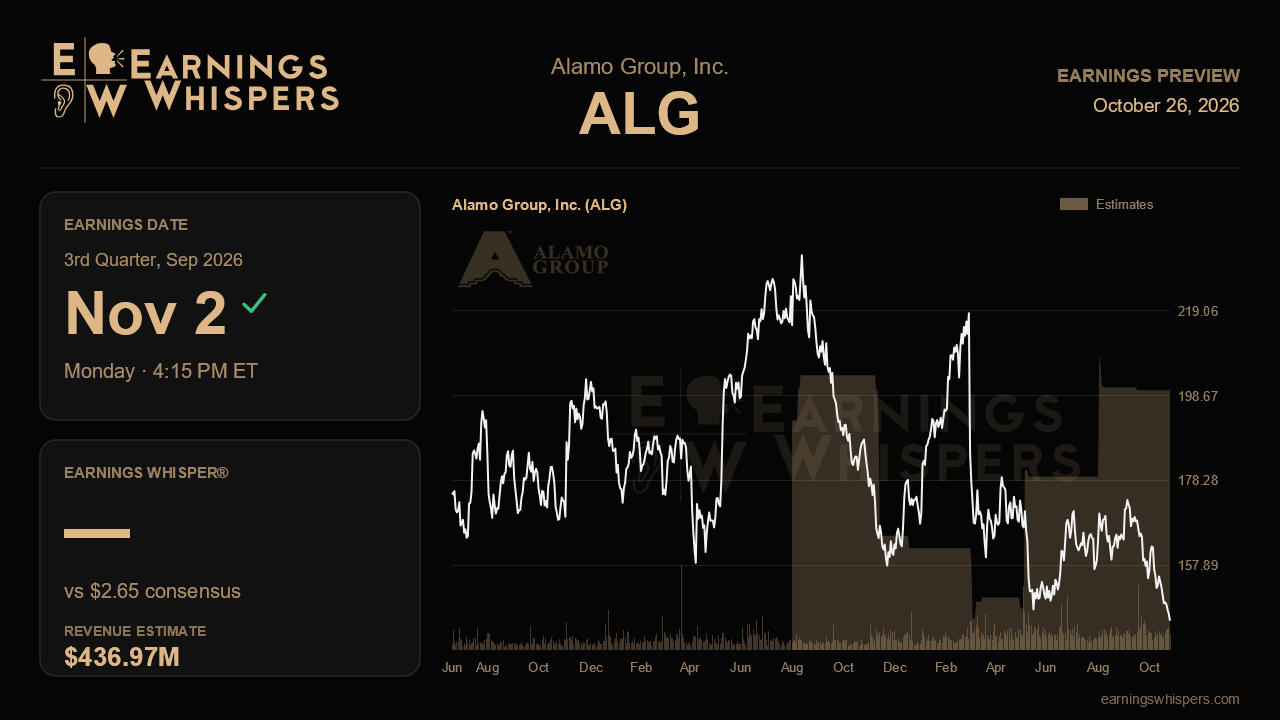
Alamo Group heads into its third-quarter report with an awkward split between what the business has been doing and what the stock has been saying. Operationally, the last two quarters looked like a genuine turn: vegetation management climbed out of a deep trough, earnings rose sequentially, and the Peterson acquisition began contributing richer margins. Yet the shares have fallen 13.6% since the last report, trailing the S&P 500 by more than 14 points. The market appears to be focusing on the softer order books management disclosed, and this report is the first real chance to show whether those were a pause or a warning.
The Street is looking for earnings of $2.65 per share on revenue of about $437 million when results arrive after the close on November 2. That would be 13.3% EPS growth on just 4% revenue growth, a gap that assumes continued margin improvement and some help from Peterson against a year-ago quarter of $2.34 and $420 million. It also implies a sequential step down from the $2.82 and $450.7 million delivered last quarter, which is consistent with the seasonal rhythm and with management's own caution. The company did not offer formal consolidated guidance, so the estimate rests on the qualitative outlook from the last call: vegetation end markets flattish to down mid-single digits in the second half, and industrial markets moderating to roughly flat after years of double-digit growth.
The most important line item is vegetation management profitability. Segment adjusted EBITDA margin recovered to 10.4% from just 2.3% three quarters earlier, and sales posted a second straight year-over-year gain after eight consecutive declines. Holding margins near that level on softer volumes would validate the argument that the recovery reflects cost discipline and better execution rather than a temporary bounce. A meaningful slip back toward single digits would suggest the improvement was more cyclical than structural. Municipal mowing and sweeper orders, which returned to double-digit growth as new budget years began, are the best leading indicator here; continued strength would help offset persistent agricultural weakness tied to farm income, borrowing costs and tariffs.
Orders are the real swing factor. Industrial book-to-bill dropped to 0.85x with orders down 2%, and vegetation book-to-bill slipped to 0.9x with orders down 1%, both weaker than the roughly 1.0x readings a quarter earlier. Excavator and vacuum truck orders were up against a record comparison, which partly excuses the industrial figure, but a second consecutive sub-1.0x quarter in both segments would make the flattish outlook look optimistic. A return toward parity would go a long way toward repairing confidence.
Gross margin deserves equal attention. It has declined about 120 basis points year over year in each of the last two quarters, landing at 24.6%, with mix, growth investments and freight and steel costs to blame. SG&A savings have so far masked the damage, bringing expenses to about 12.5% of sales. Signs of stabilization, Peterson's 23% to 24% EBITDA margins lifting the industrial mix, and any early evidence from the procurement savings program would support the earnings growth embedded in estimates. Commentary on additional portfolio pruning after the Netherlands exit, and on the M&A pipeline backed by a renewed $602.5 million credit facility and sub-1x leverage, could also shape the longer-term story.
Sentiment has soured sharply, with bearish readings roughly doubling from the prior quarter, and the stock at $144.53 sits right on its post-earnings low and well beneath its 200-day average near $170. That lowers the bar somewhat, but it also signals little patience for another round of weak orders. The central question is simple: can Alamo show that its margin recovery is durable while demonstrating that order intake has stopped eroding? If both hold, the gap between fundamentals and the share price looks overdone. If orders slip again, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-01 | |
| Sep-25 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-21 | |
| Jul-01 | |
| May-04 | |
| May-04 | |
| Apr-21 | |
| Apr-01 | |
| Mar-09 |
