Global Industrial's Volume Surge Meets A Margin Test As Shares Press Toward Highs
Global Industrial Company heads into its third-quarter report with a story that has quietly changed character. A year ago, growth leaned heavily on tariff-driven price increases. Last quarter, management described something sturdier: average daily sales up 9.3%, the third straight quarter of high-single-digit gains, with pricing contributing only about four points and volume doing the rest. The question now is whether that volume engine can keep running hard enough to offset a gross margin that management has openly said will not recover anytime soon.
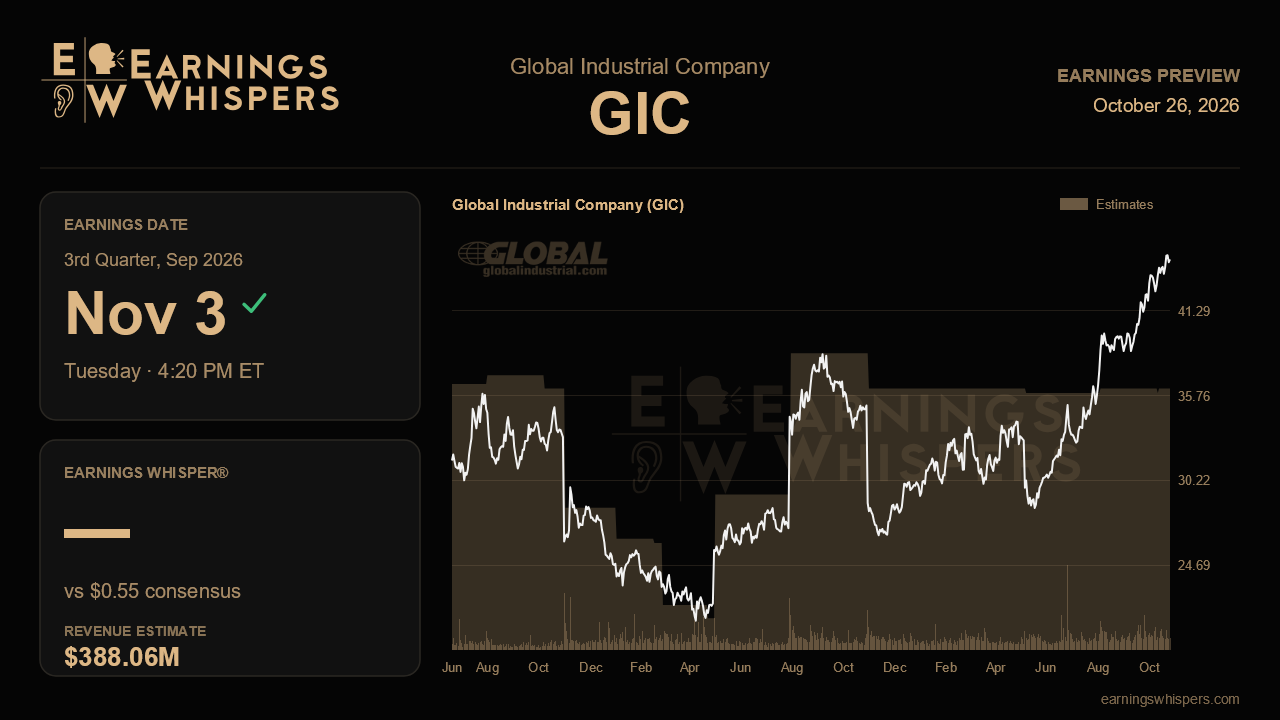
The Street is asking for earnings of $0.55 per share on revenue of $388.1 million. That would mean roughly 15% earnings growth and nearly 10% revenue growth from the year-ago quarter, which is strong for an industrial distributor. Sequentially, though, the bar is modest, barely above the $0.54 and $386.6 million posted last quarter. Management said the 9.3% pace had carried into the current quarter, so the revenue estimate looks consistent with what the company signaled rather than a stretch. The harder math sits below the top line. Management guided gross margin to hold around 34.7%, which compares with 35.6% in the year-ago quarter. Delivering mid-teens profit growth with nearly a point of gross margin compression requires real operating leverage on expenses, and that is where an upside or downside surprise is most likely to come from.
Margin is the swing factor worth scrutinizing. Last quarter's pressure came from fuel surcharges and freight inflation that the company only partially passed through, weaker seasonal cooling sales, and a growing mix of larger orders that carry thinner rates. The first two are cyclical and could ease; the third is structural and, paradoxically, a sign of success, since average order value rose about 10%. A margin print near guidance would confirm the problem is contained. Slippage below it would suggest transportation costs are still outrunning pricing, while any uptick would hint that management was conservative.
The newer growth drivers deserve equal attention. Management framed the group purchasing business as approaching a $100 million annual run rate for the first time, said e-procurement connections topped 1,300 customers, and noted digital channels now handle more than 60% of transactions. Canada, meanwhile, accelerated for four straight quarters to more than 33% local-currency growth. Continued strength in these areas would validate the idea that growth is rooted in deeper customer relationships rather than price. Any update on the national supplier trade show and the M&A pipeline management has begun building would add color on how aggressively the company plans to deploy its improved cash position, which climbed to $86.7 million on a sharp rebound in operating cash flow.
The market has already bought much of this narrative. Shares have gained about 14% since the last report while the S&P 500 slipped, and the stock sits around $44.64, roughly 1% below its post-earnings high of $45.19 and well above its 200-day average near $34.70. The entire trading range has shifted higher from the prior quarter. Sentiment has also turned noticeably less bearish than it was heading into the previous report, though it remains slightly negative, a sign that some skepticism lingers. That combination puts the stock in position to test a breakout, but it also means a merely in-line quarter may not be enough to push it through.
Ultimately, this report hinges on whether volume growth near 9% to 10% can absorb a flat 34.7% gross margin and still produce double-digit earnings growth. If revenue holds its pace, margin stays at guidance and expenses grow slower than sales, the shift from price-led to relationship-led growth looks durable. If freight costs bite deeper or volume cools, the recent rally will have gotten ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-03 | |
| Oct-02 | |
| Sep-15 | |
| Sep-02 | |
| Aug-31 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 | |
| Jul-20 | |
| Jun-08 | |
| May-08 |
