Travere's FSGS Launch Faces Its Durability Test As Stock Slides Toward Post-Earnings Lows
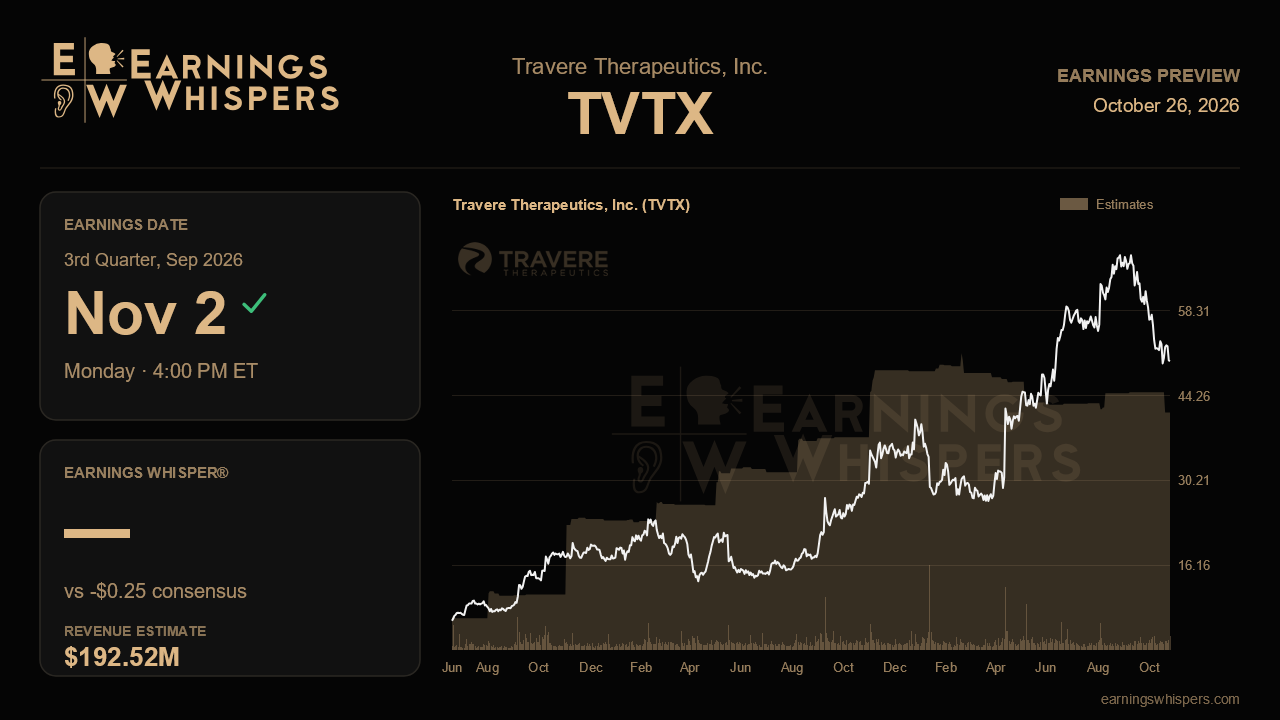
Three months ago Travere Therapeutics delivered the kind of quarter that rewrites a company's identity. Filspari sales nearly doubled from a year earlier to a record $141.1 million, new patient start forms jumped past 2,000 after the drug's April approval in FSGS, and management argued that its peak-sales target of more than $3 billion might prove conservative. The market's response since then has been a shrug turning into a frown: the shares have fallen 19.4% while the S&P 500 slipped just 1.4%. When Travere reports third-quarter results after the close on November 2, the question is simple. Was the second quarter the start of a new trajectory or a launch spike that flattered the trend?
The Street is looking for revenue of $192.5 million, up 16.8% from a year ago, and a loss of $0.25 per share, narrower than last quarter's $0.37 loss. That year-over-year growth rate understates the product story. The year-ago quarter included roughly $50 million of revenue beyond U.S. product sales, so the comparison is muddied. The more telling figure is sequential: consensus implies about $23 million more revenue than the $169.6 million booked last quarter, which effectively asks FSGS to keep compounding rather than plateau. Management has not provided formal guidance, so the bar is set by analysts extrapolating a single extraordinary quarter, precisely the exercise executives warned against.
Those warnings frame the report. Management flagged possible summer seasonality in patient starts and acknowledged that some early FSGS demand came from pre-identified patients who were seen more often, while insisting there was no bolus. The cleanest validation would be new patient start forms holding near or above the 2,000 level, along with evidence that first-pass payer approvals and conversion to paid therapy in FSGS remain ahead of the IgAN launch pace. A meaningful drop in start forms, even if explained by seasonality, would feed the pull-forward narrative that seems to be weighing on the stock.
Pricing mechanics are the second swing factor. Gross-to-net deductions were guided to rise in the back half of the year as FSGS patients, who carry heavier Medicare utilization, become a larger part of the mix, with the full year landing in the mid-20% range versus about 20% in 2025. That means unit demand has to grow faster than revenue to hit the number. A gross-to-net figure tracking worse than that framework would raise doubts about the economics of the FSGS expansion. Investors should also watch IgAN demand, which grew despite new competitors such as Vanrafia; continued sequential growth there would support management's claim of a positive halo from FSGS prescribers, about 70% of whom already had Filspari experience.
The expense line deserves attention too. Operating costs climbed last quarter on pegdibatinase manufacturing, Phase 3 Harmony enrollment and launch spending, and the $112.5 million upfront for the sivorebrutinib deal closed in July. How that payment flows through the income statement could make the GAAP comparison against the loss estimate noisy, so the cleaner read is operating spend relative to the revenue ramp.
Sentiment has soured sharply, moving from essentially neutral before the last report to 38.1% bearish now. The stock, at $49.97, sits barely above its post-earnings low of $49.46 and far below the $68.73 high, though it remains above its 200-day moving average of $46.18. That positioning lowers the emotional bar but not the numerical one. If start forms and gross-to-net show the FSGS launch is sustaining rather than fading, the selloff will look like an overreaction to caution management itself supplied. If demand stalls, the more than $3 billion ambition will start to look like a destination without a road map.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-12 | |
| Oct-02 | |
| Sep-23 | |
| Sep-21 | |
| Sep-17 | |
| Sep-11 | |
| Sep-08 | |
| Aug-24 |
Guardant Health Dives After Losing A Patent Dispute; Judge Orders Royalties
TVTX
Investor's Business Daily
|
| Aug-21 |
IBD Stock Of The Day, Travere Therapeutics, Tests Another Breakout. Can The Stock Get Any 'Sweeter?'
TVTX
Investor's Business Daily
|
| Aug-12 | |
| Aug-05 | |
| Aug-05 |
