Kforce Matches The Whisper As Growth Accelerates, But Cash Flow And Sentiment Complicate The Setup
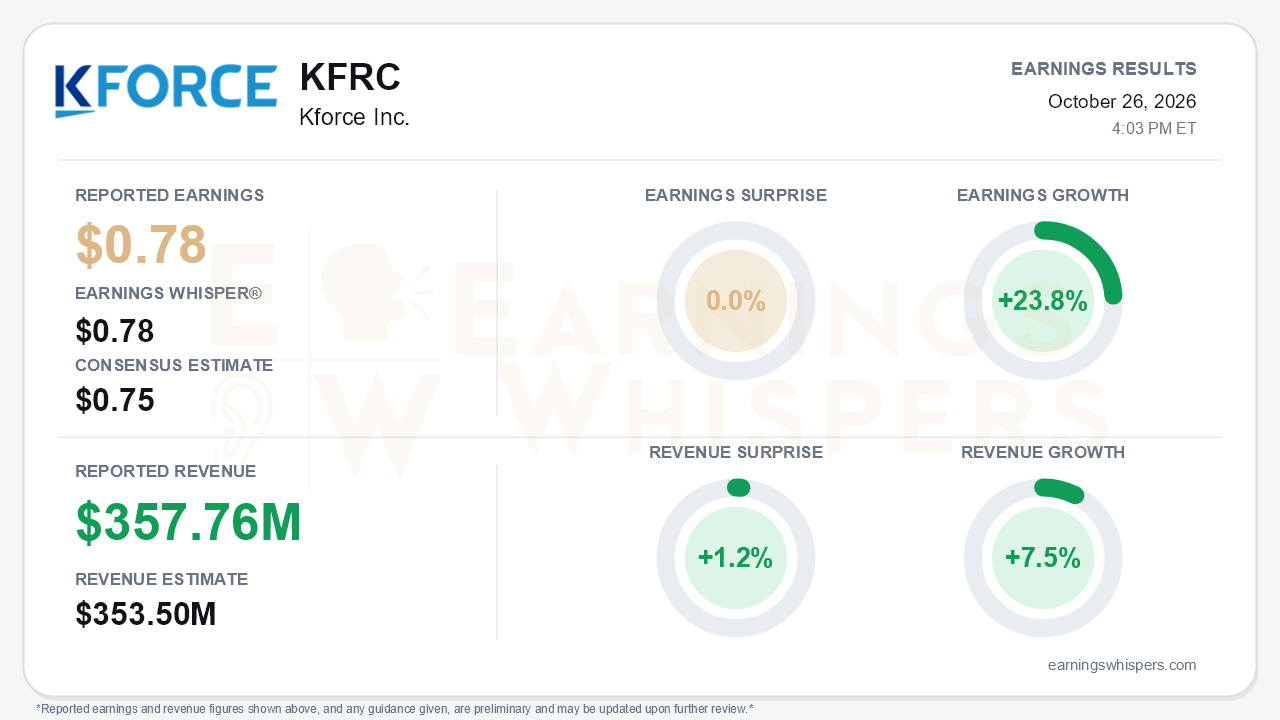
Kforce delivered the kind of quarter recovery bulls have been waiting for, but not an earnings surprise. Excluding a $0.12 gain on company-owned life insurance (COLI), EPS was $0.78. That was $0.03 above the $0.75 consensus and exactly in line with the $0.78 Earnings Whisper number. Revenue of $357.76 million beat consensus by 1.2% and cleared the top of the company's own $349 million to $357 million guidance range. Earnings grew 23.8% year over year and revenue rose 7.5%, a clear step up from 4.5% revenue growth in the second quarter. The top-line story improved again. The bottom line simply met what the most informed expectations already assumed.
The quality of the quarter deserves a closer look. Reported diluted EPS of $0.90 and the 6.3% operating margin both flatter the result, because the COLI gain added 60 basis points to operating margin. Strip it out, and operating margin was roughly 5.7%, still a solid improvement from 4.5% a year ago. Technology Flex revenue, the core of the franchise, grew 7.8% year over year after 4.0% in Q2, 0.2% in Q1 and declines throughout 2025. Management noted that this pace roughly matches Kforce's pre-pandemic compound growth rate. Gross margin of 28.2% was up 50 basis points from a year ago but down 30 basis points sequentially, reflecting lower direct-hire mix and higher healthcare costs. Direct-hire revenue fell to $6.7 million from $7.5 million in Q2, and the average Technology placement fee dropped to about $20,700 from $26,000.
The call explained why management sounds more confident than it has in years. Consulting solutions posted record new contract award value and its best-ever pipeline conversion rate. AI-related pipelines were up about 20%, and platform engineering demand is ramping. The Technology bill rate rose for a second straight quarter to roughly $91 an hour, and management now expects it to hold stable to slightly higher. Management also pointed to healthier labor-market signals:
- rising resignations and replacement demand;
- more counteroffers;
- conversions up 23%;
- assignment attrition better than expected.
Activity reportedly strengthened from August into October, and Kforce is selectively adding sales and recruiting headcount in capacity-constrained markets. The tone has moved from last year's 'cautious optimism' to explicit talk of acceleration. Management also reaffirmed a target of at least 8% operating margin at $1.7 billion in revenue.
The guidance is where the acceleration narrative pauses. Fourth-quarter revenue guidance of $352 million to $360 million implies about 7.2% year-over-year growth at the midpoint, above consensus but essentially flat with Q3's 7.5% against a tougher comparison. Management acknowledged limited visibility into December. EPS guidance of $0.62 to $0.70 compares favorably with $0.43 in the year-ago quarter, though two fewer billing days and a 4.5% to 4.9% operating margin guide show the seasonal step down. Further out, the Workday go-live in early 2027 will lift depreciation and amortization before its benefits arrive in late 2027 and 2028.
Bears have legitimate ammunition on the balance sheet. Third-quarter operating cash flow was only $9.5 million, below plan because a large client delayed a payment. Management says that payment was resolved in October. Still, nine-month operating cash flow was just $2.8 million versus $41.9 million a year earlier, and free cash flow was negative $8.0 million. Over the same period, receivables climbed to $229.7 million, borrowings on the credit facility rose to $107.9 million from $66.4 million, and cash dwindled to $250,000. Buybacks were halted in Q3 to hold debt flat. Leverage improved to 1.3x from 1.4x, but year-to-date dividends and repurchases exceeded operating cash flow. Growth is consuming working capital, and that limits capital-return flexibility until collections catch up.
The market setup is more complicated than the in-line print implies. Investor sentiment swung from a modestly positive 0.21 after the prior report to -0.17, a meaningful shift into negative territory. Meanwhile, the shares have gained only 3.3% since the post-July open, to $58.42, yet sit about 34% above the 200-day moving average of $43.50. Much of the recovery appears to have been priced in before this report, which helps explain why a whisper-matching quarter did not inspire more enthusiasm. The Earnings Whispers trend signals lean positive on momentum and AVWAP, while sequential growth is a soft spot, consistent with Q4 guidance holding growth steady rather than extending the acceleration.
The bottom line is that Kforce's operating recovery is real and broadening, with Technology growth back near historical norms, rising bill rates and a stronger consulting pipeline. The quarter, however, met rather than exceeded informed expectations. The headline EPS was flattered by the COLI gain, the fourth-quarter guide implies a plateau in growth, and cash generation has badly lagged earnings. With the stock already well above its long-term average and sentiment turning negative, the next leg likely depends on proving that collections normalize and that 7% to 8% growth can re-accelerate into 2027.
Read our earnings preview for Kforce Inc.: https://www.earningswhispers.com/article/KFRC/20659
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-01 | |
| Sep-23 | |
| Sep-11 | |
| Aug-05 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-07 | |
| May-23 | |
| May-20 | |
| May-05 | |
| Apr-28 |
