Whirlpool Misses Widely And Cuts Guidance For A Third Straight Quarter As Margin Recovery Slips Into 2027
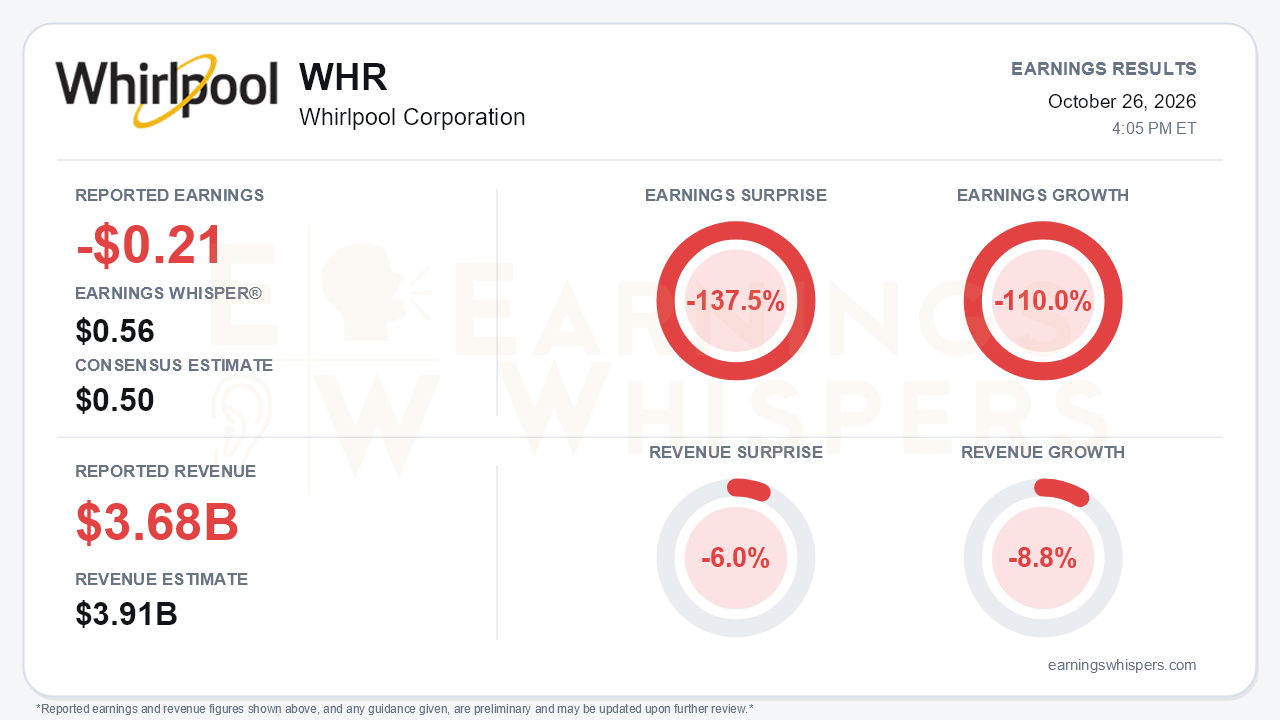
Whirlpool's third quarter was a clear miss on both lines, and the guidance cut matters more than the miss itself. The company reported an ongoing loss of $0.21 per share against a consensus estimate of $0.50 and an Earnings Whisper of $0.56, a 137.5% shortfall. Earnings fell 110.0% from the prior year's $2.09. Revenue of $3.677 billion missed consensus by 6.0% and fell 8.8% year over year, or 5.4% on an organic basis. The central tension is that management can point to a second straight quarter of sequential margin improvement while cutting full-year targets for the third consecutive call. The recovery is happening, but more slowly and from a lower base than investors were promised.
The GAAP picture was harsher, with a loss of $3.80 per share. That figure included a $124 million non-cash impairment of the Whirlpool India stake, a $54 million net charge tied to the bankruptcy reorganization of Brazilian retailer Grupo Casas Bahia, and $35 million of restructuring costs. Excluding those items, ongoing EBIT margin improved to 2.6% from 1.8% in Q2 and 1.3% in Q1. It remains well below last year's 4.5%. Ongoing EPS was flat sequentially at -$0.21 because interest expense jumped to $102 million from $63 million in Q2. The capital structure also looks different from a year ago. Diluted shares rose to 65.5 million from 56.5 million after a common equity raise and an 8.5% mandatory convertible preferred issue. No common dividend was declared in the quarter, compared with $0.90 a year ago.
Beneath the headline, North America is the problem. MDA North America sales fell 8.3% and segment margin slid to 3.0% from 4.9%. Management cited a U.S. industry down 3.3%, while the segment's organic sales fell roughly 8%. That gap is hard to reconcile with management's description of stable market share. Competitors did not follow summer price increases, which forced a pricing course correction. Replacement demand is showing signs of deferral as consumers repair rather than replace, which is pushing mix the wrong way. Latin America grew sales 6.9%, but its margin collapsed to 2.0% from 5.7% as the Casas Bahia fallout distorted mix. Small Domestic Appliances was the bright spot, with an 18.6% margin and U.S. October orders up about 40%, though partly on order timing.
The outlook reset was broad:
- Full-year organic revenue is now expected to decline about 1.5%, versus +1.5% previously and +5% in January.
- Ongoing EBIT margin guidance fell to 2.0-2.2%, from roughly 4% last quarter and 5.5-5.8% at the start of the year.
- Ongoing EPS is now guided to -$1.30, which implies another loss of about $0.35 in Q4.
- The price/mix contribution was cut to +25 basis points.
- Net cost swung to a 125-basis-point headwind as steel rose about 50% and Section 232 tariffs and logistics costs absorbed the cost takeout.
The tone shifted from Q2's confident talk of a Q3 step-up to an admission that the quarter 'did not deliver the margin step up we had expected.' Management is now only 'cautiously optimistic' about 2027.
The bull case now rests almost entirely on 2027. Supporting points include:
- A further ~7% North America price increase (Canada November 1, U.S. December 3) and up to 10% in Latin America.
- $290 million of structural footprint and logistics savings, mostly landing next year.
- Two of three long-term steel contracts renewed at what management called fair prices.
- An expected ~$100 million Q4 insurance recovery on the Casas Bahia receivable.
The lower net debt target of below $4.5 billion, an undrawn revolver and no major maturities until 2028 ease near-term balance-sheet anxiety. Part of that improvement, however, was funded by dilutive equity. Bears have legitimate ammunition. The pricing strategy has already failed once when competitors didn't follow. Free cash flow guidance was trimmed again, to about $300 million, after a nine-month outflow of $1.08 billion. Hitting it depends heavily on fourth-quarter working capital.
The market had been bracing for trouble. Shares fell 35.1% from the $40.78 open after the August report to $26.45 and sit roughly 47% below the 200-day moving average of $49.84. Investor sentiment deteriorated meaningfully, from -0.18 to -0.48. The Earnings Whisper trend signals are mostly negative on price and AVWAP, with only the sequential growth reading positive. That split mirrors the fundamentals: margins are inching up from a trough while the trajectory of expectations keeps falling.
The bottom line is that Whirlpool delivered sequential progress without credibility. A third straight guidance cut, a widening gap between North American sales and industry demand, and a recovery now pushed into 2027 overshadow the margin uptick. Until the Q4 price increases stick and the cost savings show up in reported margins, the stock's steep discount reflects a story investors have stopped taking on faith.
Read our earnings preview for Whirlpool Corporation: https://www.earningswhispers.com/article/WHR/20814
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 8 hours | |
| 12 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
Whirlpool Heading for Full-Year Loss as Costs Mount and Sales Fall
WHR -5.91%
The Wall Street Journal
|
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
