Repligen Beats And Raises Again, But BioLife Does The Heavy Lifting On Guidance While Filtration Weakens
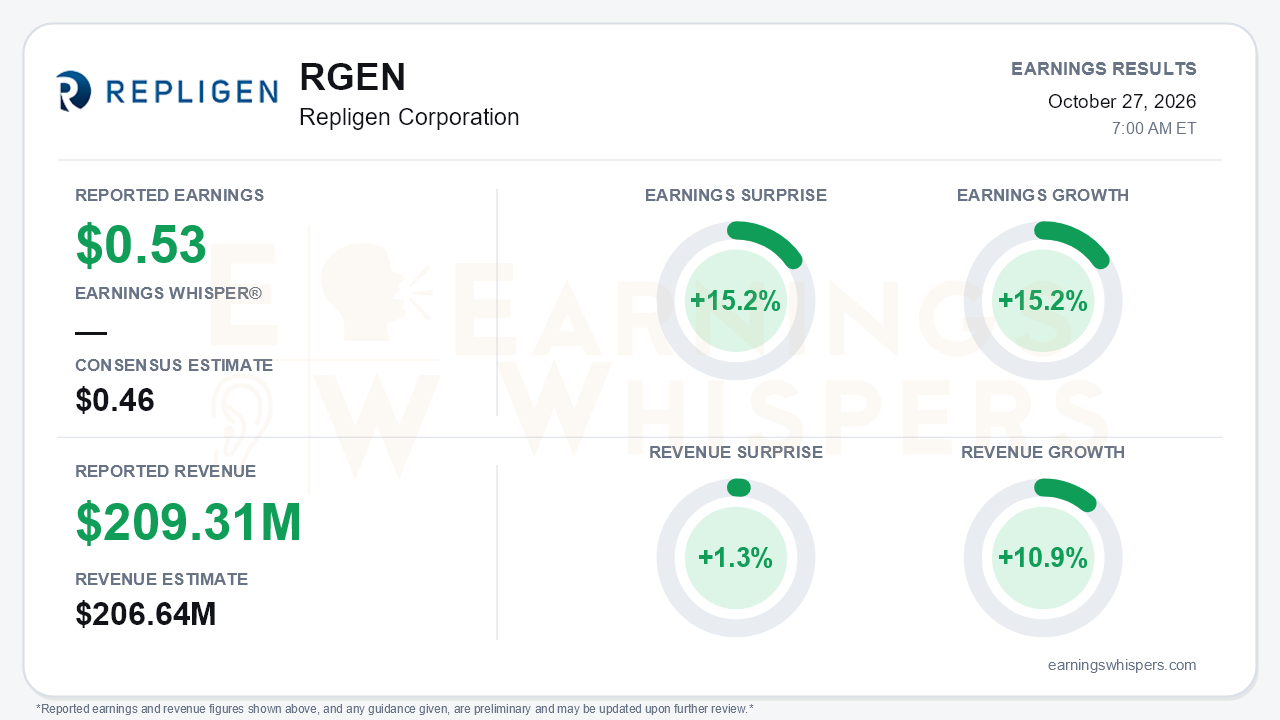
Repligen delivered a clean beat on the numbers that matter most to the Street. Adjusted EPS of $0.53 topped the $0.46 consensus by 15.2% and rose 15.2% year over year. Revenue of $209.31 million beat expectations by 1.3% and grew 10.9%, or 12.5% organically. It was a record quarter, finally surpassing the company's 2022 peak, and it came with the third consecutive full-year guidance raise, the close of the BioLife Solutions acquisition, and a new framework calling for revenue above $1 billion in 2027. The central tension is that the headline momentum is real, but organic growth is steady rather than accelerating, and the largest part of the revenue guidance increase is acquired.
The quality of the beat holds up better on the operating line than on the gross line. Adjusted operating margin expanded 170 basis points to 15.9%, and adjusted EBITDA margin reached 20.9%, helped by operating leverage. Adjusted gross margin, however, slipped to 53.0% from 53.3%. That is a notable reversal after gains of roughly 280 basis points in Q2 and 180 basis points in Q1, and management pointed to inflation and mix pressure. On a GAAP basis, the quarter swung to a loss of $0.68 per share from a profit of $0.26. The main driver was a $41.2 million intangible impairment on an IP license, along with a heavier tax provision. These charges are non-cash and are excluded from adjusted results, but investors should not ignore an impairment of that size. Year-to-date operating cash flow improved to $104 million, and the company held $863 million in cash and securities before funding BioLife.
The call showed a business whose strength is concentrated in specific franchises. Consumables and services each grew about 20% or more, proteins rose 40%, and China grew more than 40%. Management raised its full-year chromatography and analytics outlooks to growth above 30%. Capital equipment orders rose mid-teens year over year, the best in five years, which was a clear step up from the vaguer "sequential step-up" language in Q2. ATF wins year to date already match all of 2025. Filtration is the clear exception. It fell 11%, slightly worse than management expected, and the full-year outlook was cut to flat to slightly down. That outlook started the year at low double-digit growth and stood at mid-single digits as recently as last quarter. Equipment revenue also continues to decline despite the stronger orders. Management described customer decision-making as only "5-10% open," and onshoring RFPs are running nine to twelve months behind its expectations. As a result, the order strength largely builds a 2027 backlog rather than lifting 2026 results.
The guidance details reinforce that reading. Full-year revenue moved to $844-$852 million from $813-$834 million. Most of that increase reflects BioLife's roughly $24 million fourth-quarter contribution, while the organic midpoint rose only 50 basis points, half the size of last quarter's raise. The adjusted EPS midpoint rose just a penny to $2.05-$2.09. Management flagged a fourth-quarter opex step-up and said BioLife will be slightly dilutive in the quarter. Its foreign-exchange assumption also moved from a tailwind to neutral. The longer-dated catalysts are more compelling. Management reaffirmed at least $0.05 of BioLife accretion in 2027, said more than half of year-one opex synergies are already actioned, and outlined a faster path to a 30% EBITDA margin. It also guided to 2027 reported growth of at least 25%.
The market had largely anticipated an improving story. Shares have climbed 29.0% since the open after the July report. They now trade about 24.7% above the 200-day moving average and roughly 31% above the inter-earnings low set on that same day. Still, the stock entered the report 9.4% below the 52-week high of $198.87 reached in late September, so some of the quarter's enthusiasm had already been given back. The Earnings Whispers trend signals are uniformly positive. Investor sentiment, by contrast, was essentially unchanged and mildly negative at about -0.18, suggesting the rally has outrun conviction among individual investors.
That gap matters. A stock up nearly 30% in a quarter needs more than an acquisition-assisted guidance raise to extend its run. Bears have legitimate points to make: slipping gross margin, a deteriorating filtration franchise, and equipment conversion pushed into next year. Bulls can point to record revenue, broadening order momentum, and a credible path to $1 billion.
The bottom line is that Repligen delivered a genuine beat-and-raise, and the call preserved a credible multi-year growth story built on chromatography, analytics, consumables and BioLife. The near-term picture is less impressive than the headline suggests. Organic growth is holding near 12-13% rather than accelerating, filtration and capital equipment remain drags, and the revenue raise leans on acquired sales. With shares well above trend but off their highs and sentiment flat, the next leg depends on order momentum turning into revenue and gross margin resuming its expansion.
Read our earnings preview for Repligen Corporation: https://www.earningswhispers.com/article/RGEN/20722
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 10 hours | |
| Oct-13 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-29 | |
| Aug-26 | |
| Aug-19 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-22 |
