INNIO's First $1 Billion Quarter Brings A Margin Inflection And A Guidance Raise, Challenging A Stock Priced For Disappointment
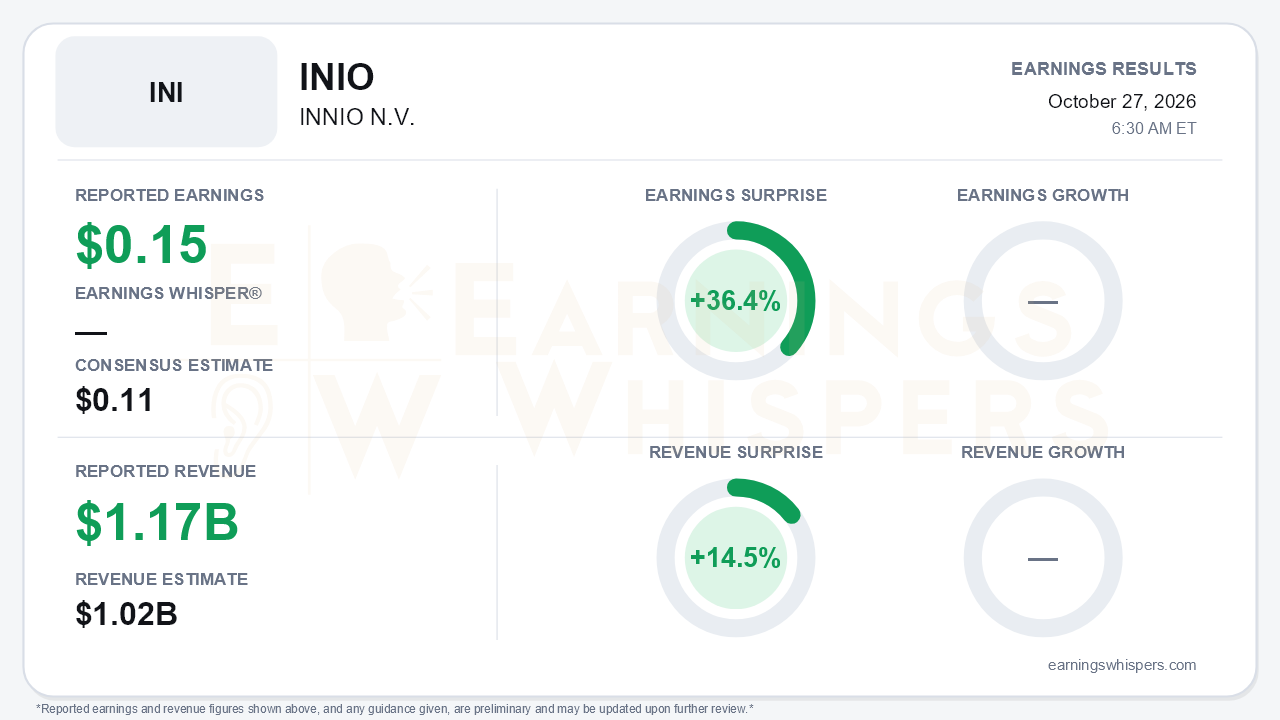
INNIO N.V. (NASDAQ: INIO) reported third-quarter earnings of $0.15 per share, beating the $0.11 consensus by 36.4%. Revenue of $1.168 billion topped the $1.02 billion estimate by 14.5% and marked the company's first billion-dollar quarter. The company said revenue grew 57% year-over-year, up from 42% growth in the second quarter. Management also raised full-year revenue guidance to $3.9-$4.0 billion and adjusted EBITDA guidance to $780-$800 million, only one quarter after first issuing the outlook. That is the central tension. The data center power story looks stronger on almost every operating measure, yet the stock entered the report down 34.6% since the open after the July release and only days removed from a 52-week low.
The beat came mostly from operations, not adjustments. GAAP diluted EPS and adjusted EPS were both $0.15. Net income rose to $109.2 million from $39.5 million. Adjusted EBITDA increased 70% to $245.4 million, and the margin widened to 21.0% from 19.4%. That is a sharp reversal from the second quarter, when EBITDA grew only 20% and margins compressed year-over-year.
The Equipment segment drove the improvement:
- Revenue rose 86% to $777.6 million.
- Segment EBITDA more than doubled to $132.8 million.
- Segment margin reached 17.1%, up from 14% in Q2 and 7.1% in Q1.
- Equipment EBITDA per gigawatt delivered rose from $33 million in Q1 to $106 million.
- SG&A fell from 19% of revenue in Q1 to 11%.
Together, these figures show real operating leverage as backlog converts to deliveries. Services added a 20% revenue gain and a 31.7% segment margin.
The nine-month figures need context. Year-to-date GAAP net income still trails last year because of $93.6 million in IPO and public-market readiness costs and higher financing expense. Cash generation looks strong, with $741.5 million of operating cash flow, but the composition matters. Contract liabilities, essentially customer prepayments, contributed $797 million. Inventory consumed $484.6 million as the company built for deliveries. Customers are funding much of the capacity build, which is a sign of demand but not the same as steady-state free cash flow.
The call made demand look deep and durable. Backlog reached $8.0 billion, up from $6.6 billion in Q2 and 142% higher year-over-year. Including slot reservations, booked capacity totals roughly 19 GW, compared with more than 15 GW a quarter earlier. New agreements during the quarter included:
- a 620 MW follow-on data center order, paired with a lifecycle service agreement covering the first 500 MW;
- a 450 MW behind-the-meter order from Liberty Energy for 2028 delivery;
- an Aggreko partnership extended through 2031, with at least 450 MW to be ordered by the end of 2027.
Management also disclosed service intensity above $50,000 per MW per year for newly added fleet, versus about $30,000 for the existing base. It set an ambition to quadruple adjusted service EBITDA by the mid-2030s. Exposure to the largest customer is expected to fall to about 21% from 41% in 2025, and net leverage dropped to 2.1x from 3.6x at year-end.
Bears still have legitimate ammunition:
- **Orders:** Equipment orders of $2.2 billion slipped from Q2's $2.3 billion record, and power solutions orders fell to $265 million from $546 million.
- **Services growth:** Management guided services growth to high single digits in coming years, well below 2026's roughly 20% pace.
- **Q4 earnings:** The raised guidance implies fourth-quarter EBITDA roughly flat with Q3 despite higher deliveries.
- **Services margin:** The Q3 services margin benefited from a favorable parts mix that may not repeat.
- **Customer credit and permitting:** Analysts pressed on data center developer credit and state permitting. Management said it has no meaningful neocloud exposure, no cancellations, and only one project delayed by a week.
The market setup is more complicated than the surprise implies. As of October 26, shares sat at $16.63. That is about 35% below the $25.57 200-day moving average and 43% below the August 12 inter-earnings high of $29.34. The stock was only 14% above the October 22 low of $14.58. The AVWAP trend signal remains negative, consistent with sustained selling since the last report. Investor sentiment swung sharply from a negative reading of -0.48 after the prior report to a strongly positive reading. That latest figure (2.15) falls outside the stated -1 to +1 scale, so its exact magnitude should be treated cautiously. The direction, however, is clearly a shift from skepticism toward optimism heading into the print.
The bottom line is that INNIO delivered the margin inflection and guidance raise that skeptics had not priced in. Accelerating growth, record backlog and a credible long-tail services opportunity all strengthened the fundamental case. The open questions are narrower: whether orders keep pace, whether Q4's flat implied earnings is conservatism or a plateau, and whether data center customer credit concerns fade. With the stock still deeply below its long-term average, the report gives investors a clearer gap between operating momentum and share-price performance than they have had all year.
Read our earnings preview for INNIO N.V.: https://www.earningswhispers.com/article/INIO/20704
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 5 hours | |
| Oct-22 | |
| Oct-14 | |
| Oct-08 | |
| Sep-30 | |
| Sep-22 | |
| Sep-17 | |
| Sep-02 | |
| Aug-20 |
Innio to add 500 jobs, spend $300 million at Waukesha engine plant
INIO -8.80%
Milwaukee Journal Sentinel
|
| Aug-19 | |
| Jul-30 | |
| Jul-28 | |
| Jul-28 |
