Dorman Beats On EPS, But A Third Straight Sales-Guidance Cut Overshadows Improving Volume
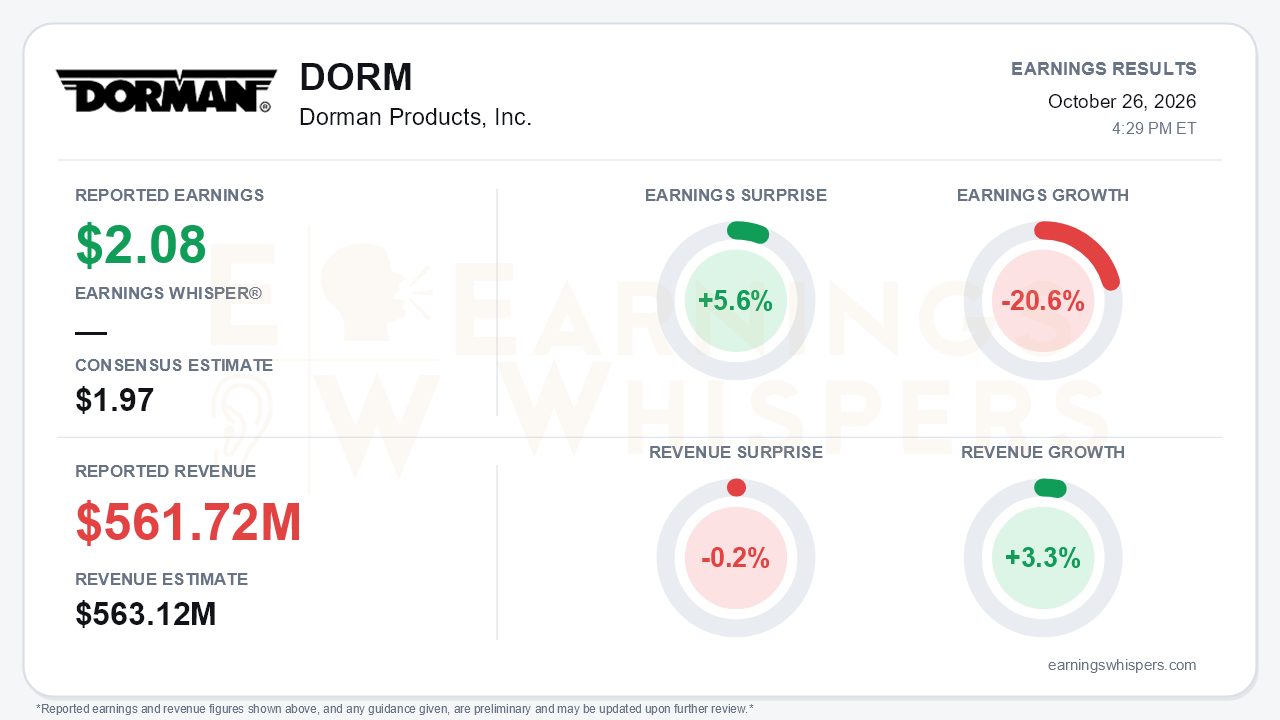
Dorman Products (NASDAQ: DORM) cleared the earnings bar in the third quarter, but the more important number is the guidance. Adjusted EPS of $2.08 topped the $1.97 consensus by 5.6%, while revenue of $561.72 million came in 0.2% shy of the $563.12 million estimate. Earnings fell 20.6% year over year even as revenue grew 3.3%. Management then trimmed its full-year net sales growth outlook to 2% to 3%, the third consecutive reduction. The forecast began the year at 7% to 9% and stood at 3% to 5% after the second quarter. That is the central tension: the operating story is improving at the volume line, yet the top-line ceiling for 2026 keeps coming down.
The quality of the beat deserves a closer look. Gross margin fell to 39.4% from 44.4%, which management attributed to tariff-related pricing that inflated the year-ago quarter. That explanation is credible, since Dorman had already flagged roughly 40% as the go-forward gross margin level. The damage showed up unevenly across segments. Light Duty segment margin dropped 520 basis points to 18.5%, and Heavy Duty fell to break-even from 4.5%. Specialty Vehicle edged up 30 basis points to 13.1%. Adjusted SG&A leverage improved slightly, to 23.6% of sales from 23.9%. A smaller diluted share count, about 29.9 million versus 30.8 million a year ago, also cushioned per-share results. GAAP EPS of $1.98 included a $1.5 million bargain purchase gain that management excluded from adjusted figures, so the non-GAAP number was not flattered by that item.
The call preserved a credible near-term growth story. Revenue accelerated from Q2's roughly 1% growth to a record $562 million, and all three segments expanded:
- Light Duty grew 3% after being flat in Q2.
- Heavy Duty grew 5%.
- Specialty Vehicle grew 3%, reversing a decline.
Management had promised volume gains from new business wins on the prior call, and they arrived. However, the demand signals underneath turned softer. Light-duty point-of-sale growth slowed from mid-single digits to roughly 3%, essentially in line with sales, and do-it-yourself softness persisted. Management also flagged new macro headwinds:
- Diesel prices up about 40% sequentially.
- Fuel costs weighing on recreational specialty-vehicle use.
- Fed rate increases lifting SOFR-based factoring costs.
The tone shifted noticeably toward caution, with references to "short-term noise" replacing last quarter's emphasis on tariff stabilization.
The guidance package was more nuanced than the sales cut alone suggests. The adjusted EPS range narrowed to $8.50 to $8.70 from $8.50 to $8.80, trimming only the top end. Adjusted operating margin guidance was tightened to the upper half of the prior range, at 16.0% to 16.5%. The low end of GAAP EPS guidance actually rose slightly. In other words, Dorman is protecting profitability while conceding revenue. The forward risk is that management expects additional tariff-related price reductions in the fourth quarter that will carry into early 2027. That makes pricing a headwind just as volume finally improved. Heavy Duty is a mixed picture: freight indicators are stabilizing, but the segment ran at break-even on tariff and shipping timing.
The balance sheet and cash flow are the clearest positives. Operating cash flow reached $64.6 million in the quarter, versus $12.2 million a year ago, and $260.9 million year to date, versus $72.0 million. Much of that came from inventory falling to $787 million from $959 million at year-end. Leverage dropped to 0.65x, liquidity rose to $966 million, and year-to-date buybacks hit a record $112 million. Management did signal that repurchases could slow if acquisition activity picks up, which matters given how much the shrinking share count has supported EPS.
The market has not been rewarding the story. Shares have fallen 12.2% since the open following the August report, to $124.74, and sit just 1.1% above the 200-day moving average of $123.35. Investor sentiment slipped from essentially neutral to modestly negative, a measurable but not dramatic deterioration. The Earnings Whispers price and AVWAP trend readings are negative, while sequential growth remains positive. That split mirrors the tension between improving quarterly volume and a deteriorating full-year outlook.
The bottom line is that Dorman delivered a respectable quarter: accelerating sales, an EPS beat, and strong cash generation. But it again lowered the revenue bar and introduced fresh pricing and macro headwinds that extend into 2027. Bears have legitimate ammunition in the repeated guidance cuts and slowing point-of-sale trends. Bulls can point to stabilizing margins near 40%, firmer operating-margin guidance, and a fortified balance sheet. With shares hovering just above their long-term average, the next test is whether volume gains can outrun the coming price-downs.
Read our earnings preview for Dorman Products, Inc.: https://www.earningswhispers.com/article/DORM/20650
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-13 | |
| Jun-02 | |
| Jun-02 | |
| May-04 | |
| May-04 | |
| Apr-13 | |
| Apr-02 | |
| Mar-06 |
