CenterPoint Energy Beats And Extends Its Growth Runway To 2030, But Investors Must Fund It With More Equity
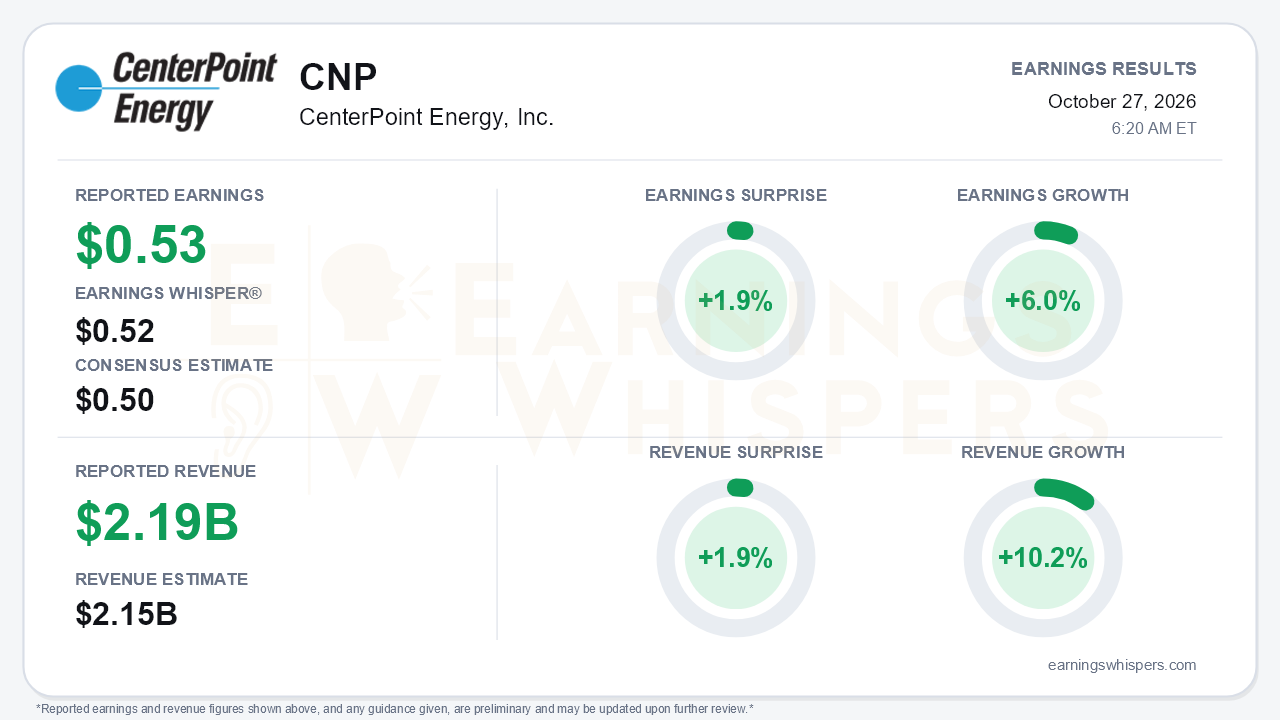
CenterPoint Energy (NYSE: CNP) delivered a modest third-quarter beat. The more important news was a substantial expansion of its long-term growth plan. Non-GAAP EPS of $0.53 topped the $0.50 consensus and the $0.52 Earnings Whisper number, a 1.9% surprise. Revenue of $2.191 billion beat the $2.15 billion estimate by 1.9% and grew 10.2% year over year. Earnings rose 6.0%, and GAAP EPS improved to $0.50 from $0.45. The quarter itself was secondary to the guidance package. Management raised 2026 non-GAAP EPS guidance to $1.90-$1.92, initiated 2027 guidance of $2.07-$2.09 (about 9% growth at the midpoint), and extended mid-to-high-end 7%-9% annual EPS growth through 2030. The central tension is that the larger plan comes with a larger equity bill.
The quality of the beat holds up reasonably well, with one caveat. Growth and rate recovery added $0.09 per share versus last year, and O&M was flat. Those are the core regulated-utility drivers. However, $0.03 came from favorable weather and usage, which investors should not extrapolate. On the other side, higher financing costs from new debt and equity dilution subtracted $0.04. Another $0.05 of unfavorable variance came mostly from the absence of a one-time tax benefit in last year's quarter. The 6.0% headline growth therefore understates the underlying trajectory, which is closer to the roughly 9% growth implied by full-year guidance. Sequentially, EPS of $0.53 compared with $0.40 in Q2 and $0.56 in Q1. Year-to-date results stand at about 80% of the new guidance midpoint. The dilution drag is notable because it previews the trade-off now embedded in the plan.
The call marked CenterPoint's most significant upgrade of the year. The 10-year capital plan rose by $4.0 billion to $70.7 billion, driven by newly identified 345 kV and 138 kV transmission projects that are about 85% brownfield. Another $1.5 billion was pulled forward into 2026-2030. Since Investor Day, the plan has grown cumulatively by about $5.7 billion. Enterprise rate base growth is now framed at more than 14% annually through 2030, up from more than 11% at the start of the year.
Demand indicators support the upgrade. Distribution-level load requests roughly doubled to about 1 GW from 500 MW last quarter, and Houston industrial and commercial leasing is up more than 30%. Management also said early Batch 1 interconnection requests are already trending above Batch 0, and the current transmission plan covers only about half of that need. Management's language escalated from describing a "tangible and executable" plan to calling the growth "explosive" and "unprecedented."
Bears still have legitimate ammunition:
- **Equity needs:** Unlike Q2's capex raise, which required no new equity, this one adds $1.6 billion to the equity guide, bringing it to $4.5 billion. That includes $500-$700 million of common equity in 2027. Management noted this funds only about 40% of the increase, below a 47% rule of thumb, but it still means more dilution.
- **Studied load:** Batch Zero studied load fell to about 2 GW from about 4 GW as customers withdrew.
- **Capex timing:** 2026 capex will land modestly below the $6.8 billion target because of project timing.
- **Financing and regulatory pressure:** Management acknowledged higher interest rates as a sector headwind. A growing share of long-cycle transmission spending raises the stakes for interim recovery, especially amid affordability and landowner scrutiny in Texas and Indiana.
The balance-sheet picture partly offsets these concerns. Moody's FFO/debt improved to 13.7%, with roughly 110 basis points of additional pro forma benefit from the closed $1.4 billion Ohio gas sale and a filed minimum-tax refund. Moody's outlook moved to stable.
The market setup entering the report was more cautious than the fundamentals. Shares closed at $41.20 the day before the call, 5.4% below the open after the July report. The stock touched a 52-week high of $45.26 on July 28, then slid to a 52-week low of $36.37 on September 29. It had since recovered 13.3% from that low but remained 9.0% below the high and slightly under its 200-day moving average of $41.48. Investor sentiment improved from roughly neutral (-0.017) to mildly positive (+0.092). That is a constructive shift, but not an enthusiastic one. Earnings Whispers trend readings on sequential growth, momentum, and AVWAP are positive, while the price trend remains negative. That split fits a stock still repairing a sharp mid-quarter drawdown.
The bottom line is that CenterPoint turned a small beat into a materially longer and steeper growth story. It now has a raised 2026 outlook, 9% growth guidance for 2027, and a high-end growth target stretching to 2030, all backed by Houston load demand that appears to be outrunning the current plan. The cost is real. More equity, a halved Batch Zero studied load, and greater reliance on long-cycle transmission recovery mean execution and financing discipline will determine how much of that growth reaches shareholders.
Read our earnings preview for CenterPoint Energy, Inc.: https://www.earningswhispers.com/article/CNP/20688
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| 14 hours | |
| 17 hours | |
| 17 hours | |
| Oct-22 | |
| Oct-14 | |
| Oct-10 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-22 |
