Celestica Beats And Unveils $40 Billion 2027 Outlook, But Cash Burn And Share Weakness Complicate The Story
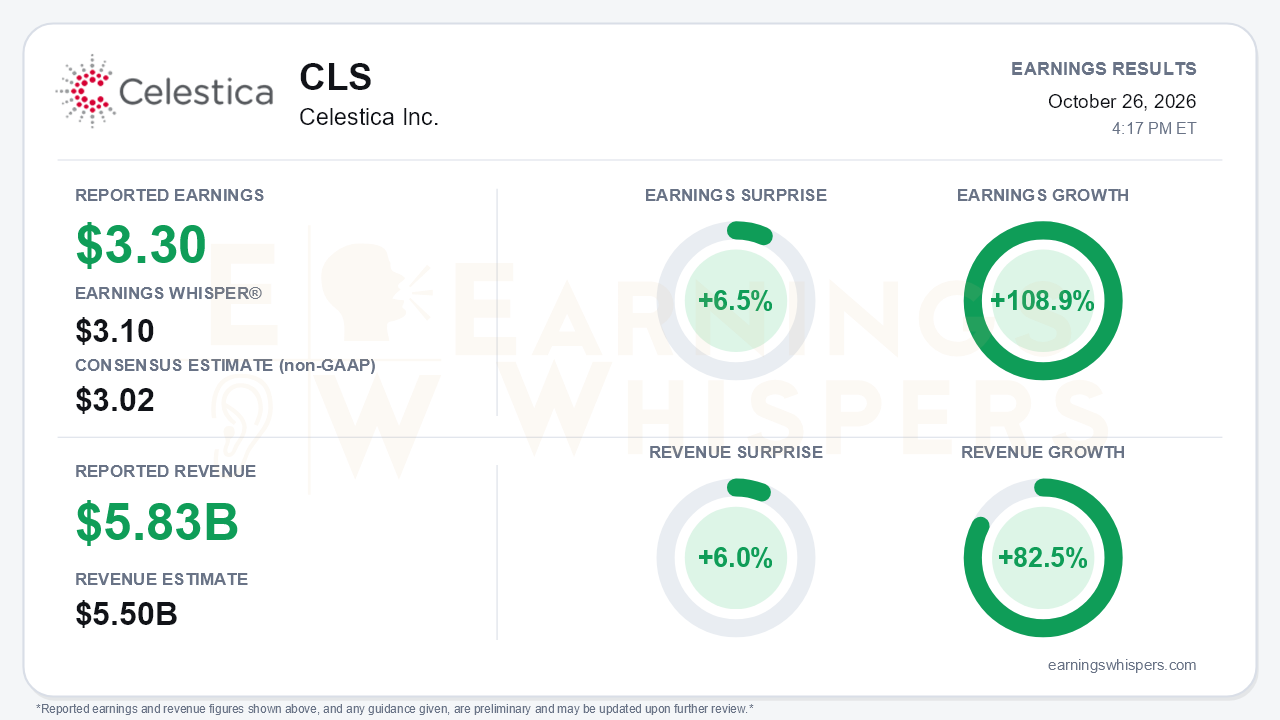
Celestica delivered a beat-and-raise, then a 2027 outlook that resets the scale of the story. Third-quarter adjusted earnings of $3.30 per share topped the $3.02 consensus by 6.5% and cleared the $3.10 Earnings Whisper number. Revenue of $5.83 billion beat the $5.50 billion consensus by 6.0%. Earnings grew 108.9% from a year ago and revenue grew 82.5%, and both results landed above the top of management's own guidance ranges. The bigger news was the first explicit 2027 framework: $40.0 billion in revenue, up 90%, a record 9.0% adjusted operating margin and $21.50 in adjusted EPS. The central tension is that this growth is becoming much more capital-intensive just as the stock has lost roughly a quarter of its value since the last report.
The quality of the beat largely holds up. Revenue growth accelerated for a third straight quarter, from 53% in Q1 to 62% in Q2 and 83% in Q3. The adjusted operating margin rose to a record 8.5%, up from 8.2% in Q2 and 7.6% a year ago. Connectivity & Cloud Solutions revenue doubled, up 102%, with segment margin improving to 8.9%. Compute & storage grew 242% against a roughly 190% outlook, and networking rose 68% against roughly 60%. A lower-than-planned 18% adjusted tax rate provided modest help, but the beat was primarily operational.
Two details deserve scrutiny:
- Adjusted gross margin slipped to 11.2%, from 11.5% in Q2 and 11.7% a year ago, as mix shifted toward lower-margin CCS programs. The record operating margin came from SG&A leverage rather than richer pricing.
- GAAP operating margin fell to 7.9% from 10.2%. That decline reflects last year's large total-return-swap gain rather than operating deterioration, but GAAP and adjusted earnings are now nearly identical at $3.26 and $3.30.
Management's tone on the call was unambiguously stronger. The 2026 revenue outlook was raised for the fourth time this year, from $17 billion originally to $21.0 billion. Adjusted EPS guidance has moved from $8.75 to $11.55. Management said customer demand forecasts for 2028, based on awarded programs alone, are already "meaningfully higher" than the 2027 outlook. Named drivers include:
- 1.6T networking revenue overtaking 800G in 2027, with CCS guided to grow about 110%;
- the AMD Helios ramp by year-end;
- the OpenAI "Jalapeno" rack system entering production in 2027;
- a functional co-packaged optics switch tied to a hyperscaler program ramping late 2027;
- additional hyperscaler and frontier-lab customers.
The smaller ATS segment also contributed. It grew 23%, its full-year growth outlook rose to about 13%, and it is expected to grow roughly 10% in 2027.
Bears have legitimate ammunition on cash and concentration. Free cash flow guidance for 2026 was cut to $460 million from $600 million, now below the original $500 million target, and management guided to net cash usage in 2027. Inventory jumped $1.1 billion in a single quarter to $4.5 billion. 2027 capital spending is set at $1.5 billion to $2.0 billion, above the earlier $1.5 billion placeholder. The $3.45 billion equity raise leaves $3.2 billion of net cash but lifted the share count to about 127 million. The top customer now accounts for 35% of revenue, up from 32% in Q2. Management also said ramps remain gated by component supply, and that 2027 is back-half weighted. Fourth-quarter guidance of $3.37 to $3.57 in EPS on $6.275 billion to $6.575 billion in revenue came in below estimates and implies growth of about 76%, a step down from Q3's pace. The CFO role is also changing hands.
The market had grown skeptical well before this report. Shares are down 24.8% since opening at $328.00 after the July report and, at $246.65, sit about 26% below the 200-day moving average of $332.70. Investor sentiment remained positive but weakened, falling from 0.28 to 0.11 heading into the release. The Earnings Whispers trend signals are split. Sequential growth and momentum readings are positive, while price and AVWAP trends remain negative. That split mirrors the gap between accelerating fundamentals and deteriorating price action.
The bottom line is that Celestica produced a high-quality operating beat and a 2027 outlook that turnaround-style skeptics of the AI build-out were not positioned for. Growth is accelerating, margins are expanding and the demand visibility extends into 2028. The cost of that growth is rising: thinner gross margins, heavier inventory and capex, lower free cash flow, dilution and deeper reliance on a single customer. With the stock well below its long-term trend and sentiment cooled, investors must now weigh whether the scale of the 2027 opportunity outweighs the cash and concentration risk required to deliver it.
Read our earnings preview for Celestica Inc.: https://www.earningswhispers.com/article/CLS/20647
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-12 |
