Herc Holdings Crushes Q3 Estimates As Rental Inflection Accelerates, But Rising Capex And Thin Cash Flow Keep The Debate Alive
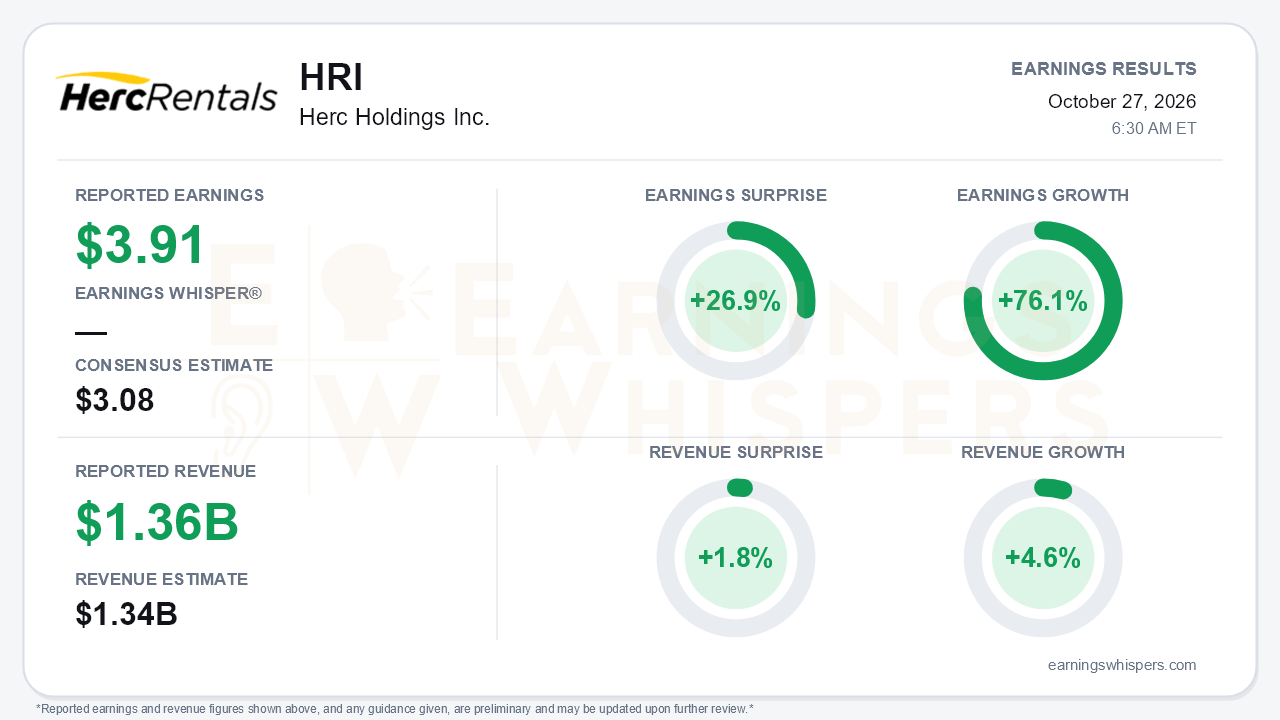
Herc Holdings delivered the quarter that bulls had been waiting for since the H&E acquisition closed. Adjusted earnings of $3.91 per share beat the $3.08 consensus by 26.9% and grew 76.1% year over year. Revenue of $1.364 billion topped the $1.34 billion estimate by 1.8%, though it grew only 4.6%. On a GAAP basis, net income more than tripled to $104 million, or $3.10 per share, from $30 million, or $0.90. The central takeaway is that the rental engine has inflected sharply. The open question is how much of that improvement reaches free cash flow and the balance sheet.
The gap between 4.6% total revenue growth and 12% equipment rental growth matters. Total revenue was held down by a $66 million drop in used-equipment sales, because the prior-year quarter included elevated disposals to rationalize the H&E fleet. Equipment rental revenue reached a record $1,254 million, and it grew on an average fleet that expanded only 1.7%. Dollar utilization jumped to 43.5% from 39.9%, which management called the best third quarter since 2022. That points to genuine fleet productivity rather than balance-sheet-funded growth. Adjusted EBITDA rose 9% to $603 million, and margin expanded 190 basis points to 44.2%. The quality of the beat is also reflected in the nine-month comparison. Year-to-date adjusted EPS of $5.55 is essentially flat with $5.54 a year ago, so the third quarter is where the operating leverage finally showed up.
The call made the trajectory clearer. Pro forma equipment rental revenue went from a 3% decline in the first quarter, to 2% growth in the second, to roughly 12% growth in the third. Mega-project volume and double-digit specialty growth led the improvement. Specialty is back to 20% of fleet OEC from 17% after the acquisition, restoring the pre-deal mix. H&E revenue synergies contributed more, in line with management's second-half weighting. Fuel and freight drag eased to about 100 basis points from 170 in the second quarter on better cost recovery. Not everything improved, however. Rental-specific EBITDA margin fell 70 basis points to 45.2% on cost inflation, incentive compensation and fuel. Direct operating costs rose to 42.4% of rental revenue from 41.6%. Management also conceded that rental rates are not keeping pace with inflation on a one-year view. Local commercial demand was described only as "stable."
Guidance was raised for the second time this year. The equipment rental revenue range is now $4.475 billion to $4.550 billion, and adjusted EBITDA is $2.10 billion to $2.15 billion. Full-year pro forma rental growth is now about 8%, up from roughly 5% in the prior outlook. Management reaffirmed its 20% mega-project share target and pointed to a new wave of semiconductor fab construction as an emerging opportunity. There is a conflict worth noting, though: Earnings Whispers flags the revenue outlook as below estimates, so the raise may not clear every expectation. The cash picture is also less flattering. Net fleet capex guidance climbed again to $1.0 billion to $1.1 billion, from about $650 million in February. That includes roughly $150 million pulled forward from 2027 for mega-project assignments. Free cash flow guidance of $250 million to $350 million was held after being cut from $400 million to $600 million earlier in the year. Nine-month free cash flow of $133 million is down from $202 million at the half, partly because receivables rose by about $160 million this year. Net leverage remains elevated at 3.90x, and 2027 capex has not been guided. The announced CEO transition adds a further variable. Larry Silber becomes executive chairman and Aaron Birnbaum takes over as CEO on January 1.
The market setup is more complicated than the surprise implies. Shares entered the report at $127.13, down 21.8% from the open after the July report. They sat 8.6% below the 200-day moving average and just 5.6% above the inter-earnings low of $120.39 set on October 1, after peaking at $176 in mid-August. Investor sentiment was barely positive and slipped slightly, from 0.034 to 0.021, so expectations were muted rather than euphoric. Earnings Whispers trend readings are mixed: momentum is positive, while price and AVWAP trends remain negative.
The bottom line is that Herc proved its post-acquisition fleet can generate substantially more revenue per dollar of equipment, and the accelerating mega-project pipeline gives the growth story real credibility. Bears still have legitimate ammunition. Rental rates trail inflation, rental-specific margins slipped, capex keeps rising while free cash flow guidance stays depressed, and leverage near 3.9x leaves little room for error under a new CEO. For a stock trading near its quarterly lows, this quarter shifts the burden of proof. Herc now needs to show that the utilization gains can turn into cash.
Read our earnings preview for Herc Holdings Inc.: https://www.earningswhispers.com/article/HRI/20700
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-13 | |
| Sep-11 | |
| Sep-04 | |
| Aug-20 | |
| Aug-19 | |
| Aug-19 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 |
