Commvault Beats And Raises Across The Board, But Slowing ARR Growth And A Cautious Second Half Temper A Stock Priced For Momentum
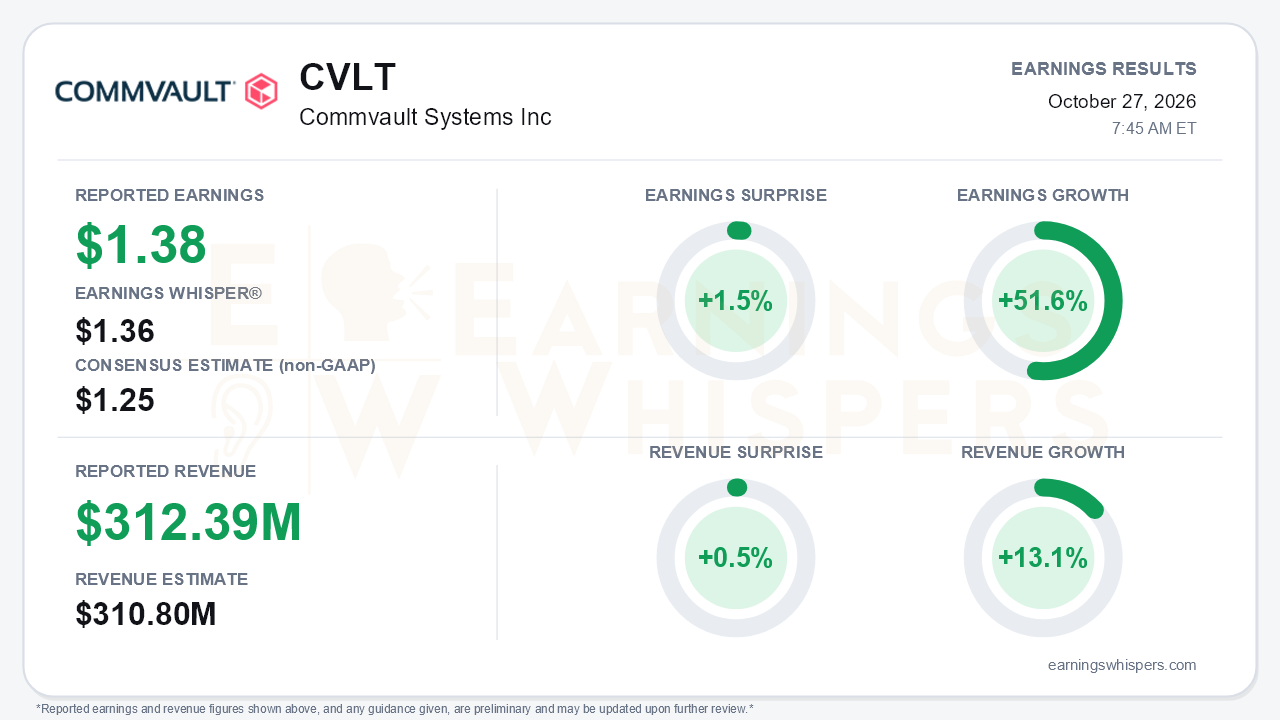
Commvault (NASDAQ: CVLT) delivered a clean beat-and-raise for its fiscal second quarter. Non-GAAP earnings of $1.38 per share topped the $1.25 consensus and edged past the $1.36 Earnings Whisper number, a 1.5% surprise. Earnings grew 51.6% year over year. Revenue of $312.39 million beat the $310.8 million consensus by 0.5% and grew 13.1%, a modest acceleration from 11% in the June quarter. Management raised every full-year metric it guides. The central tension is that the headline growth rates the market capitalizes are still decelerating off a larger base, while the stock enters the print within 4% of its high after a 32% run.
The quality of the earnings beat deserves scrutiny. Non-GAAP operating income rose about 33% to $68.3 million, and the non-GAAP operating margin reached 21.9%. That is a strong operating result. The rest of the jump to 51.6% EPS growth came from below the operating line. Interest income nearly tripled to $8.4 million on cash raised through last year's $900 million convertible offering. The diluted share count also fell to 42.2 million from 45.2 million. On a GAAP basis, EPS roughly doubled to $0.69 even though the effective tax rate rose to about 25% from near zero, but the GAAP operating margin was only 9.7%. The gap is largely $35.7 million of stock compensation, worth $0.85 per share. Free cash flow of $71 million was slightly below last year's $74 million, although first-half free cash flow rose 18% to $122 million.
The subscription business showed genuine improvement. Subscription revenue grew 21%, up from 16% in Q1. Term-license revenue rebounded 13% after essentially flat growth the prior quarter. On the call, management said perpetual-to-subscription conversions normalized. Net new subscription ARR rose to $51 million in constant currency, up from $41 million on the same basis in Q1, and term software contributed $21 million after being sequentially flat. SaaS revenue rose 33%, and SaaS gross margin expanded 650 basis points to 70%. Multi-product SaaS adoption climbed to 53% from 49%. Management also cited higher close rates, its largest-ever Active Directory deal, nearly doubled identity ARR, and roughly 50% growth in cloud-centric offerings such as Clumio.
Beneath that, bears have legitimate ammunition. Subscription ARR growth slowed to 20% from 22% in Q1 and 27% in Q4 FY26. SaaS ARR growth eased to 35% from 38% and 42% over the same quarters. Net dollar retention slipped to 113% from 114%, which management attributed to a mix shift toward new logos. About 40% of SaaS customers are now net new, versus roughly 30% a year ago. That is good for breadth but signals less expansion from existing customers. International revenue growth slowed to 9% from 15%, which management called seasonal, and perpetual license revenue fell 40%. Hardware and memory supply constraints are still delaying some on-premises deals. Management also described AI as an indirect, early tailwind with no distinct budget yet.
The guidance carries a similar mix. Full-year subscription revenue guidance rose to $1.127-$1.133 billion. The operating margin target moved up to 21.0%-21.5%, and free cash flow guidance increased to $255-$265 million. The ARR midpoint rose to $1.21 billion, but only by about $5 million. That is smaller than the roughly $10-11 million first-half constant-currency outperformance, which implies a cautious second half. Q3 margin guidance of 20.5%-21.0% sits below first-half levels because of costs for the SHIFT conference and continued go-to-market and AI investment. Q3 subscription revenue guidance of $293-$297 million implies growth back in the mid-teens. Upcoming catalysts include AI recovery launches at SHIFT on November 10-12 and participation in an Anthropic frontier-model project. Buybacks also accelerated sharply, to $109 million in Q2 from $10 million in Q1.
The market setup is more demanding than the surprise implies. Shares closed at $167.73 the day before the report, up 32.1% since the open following the July release. That left the stock 42% above its 200-day moving average and just 3.7% below the inter-earnings high of $174.25, set on the eve of the print. The stock has rallied nearly 48% off its July 31 low. Investor sentiment improved meaningfully, moving from moderately negative (-0.20) to roughly neutral (+0.01). That suggests skepticism has largely cleared without turning into enthusiasm. The Earnings Whispers trend readings are mostly positive, with price, momentum, and AVWAP constructive while sequential growth is neutral.
The bottom line is that Commvault produced a credible quarter. The term-software rebound, accelerating net new ARR, expanding SaaS margins, and an across-the-board raise preserve the growth story. However, the beat over the whisper number was slim, and part of the EPS growth came from buybacks and interest income rather than operations. ARR growth, SaaS ARR growth, and retention are all still drifting lower, and the second-half outlook is conservative. After a 32% rally into the print, investors will need evidence that net new ARR can stay in the $50 million range before the deceleration narrative fades.
Read our earnings preview for Commvault Systems Inc: https://www.earningswhispers.com/article/CVLT/20690
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 9 hours | |
| Oct-15 | |
| Oct-07 | |
| Oct-06 | |
| Sep-30 | |
| Sep-30 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-21 | |
| Sep-15 | |
| Sep-15 | |
| Sep-09 |
