American Tower Edges Past Consensus But Misses Whisper As Data Centers And Buybacks Carry A Third, Smaller Guidance Raise
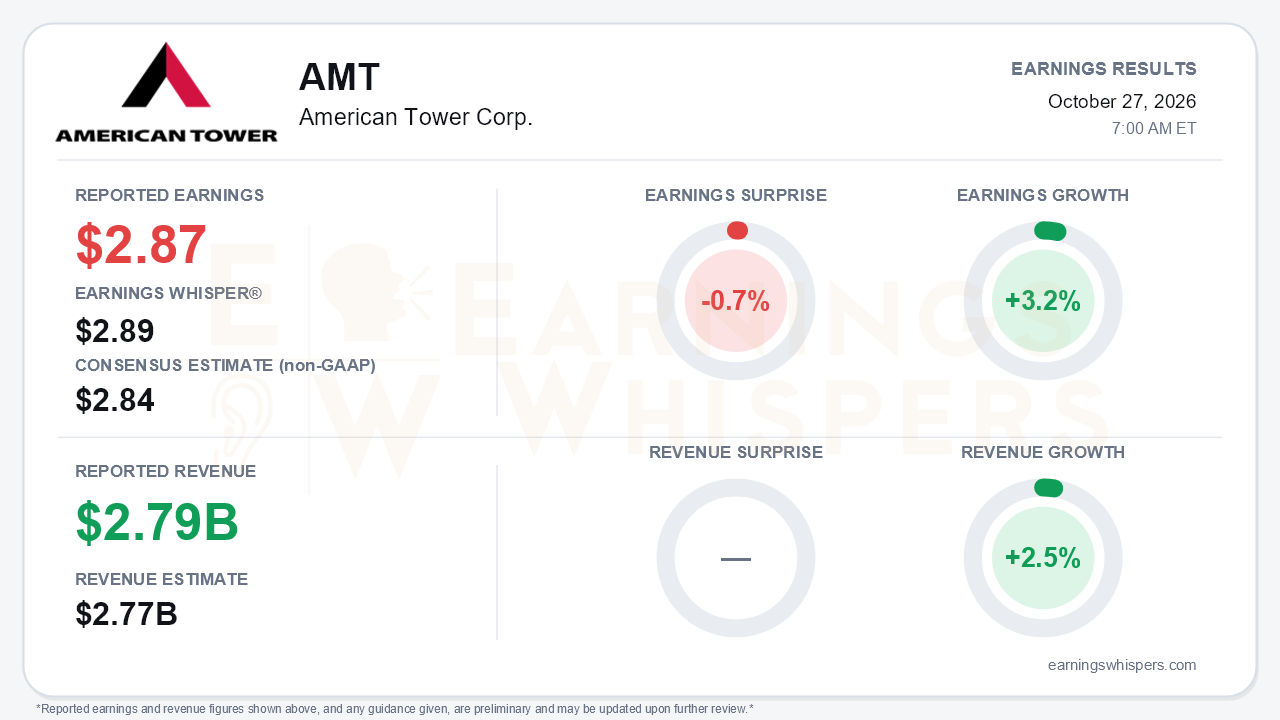
American Tower (NYSE: AMT) reported third-quarter AFFO of $2.87 per share. That topped the $2.84 consensus but fell 0.7% short of the $2.89 Earnings Whisper number. Revenue of $2.785 billion beat the $2.77 billion consensus by 0.6%. Earnings grew 3.2% year over year and revenue grew 2.5%, modest gains for a quarter in which the company raised its full-year outlook for the third straight time. The central tension is the source of that raise. CoreSite and share repurchases are doing the lifting, while the core U.S. tower business sits at a cyclical low and the size of each guidance raise keeps shrinking.
The quality of the quarter deserves scrutiny. Total property revenue rose 4.5%, but Organic Tenant Billings Growth was just 1.1%, down from 5.0% a year ago. Cancellations jumped to $97 million from $43 million, largely reflecting DISH churn. U.S. & Canada property revenue fell 3.3%, and organic billings growth in that segment was flat, or roughly 4% excluding DISH. Latin America organic billings contracted 2.1%. Services revenue was nearly halved, down 49.2%. Adjusted EBITDA grew only 0.9%, and the margin slipped to 65.8%. GAAP results looked worse:
- Diluted EPS fell 9.9% to $1.64.
- Roughly $71.5 million of unrealized equity losses weighed on the result.
- The tax provision was sharply higher.
- A negative swing in straight-line revenue distorted the comparisons.
The AFFO per share gain of 3.2% owed something to a lower share count after more than $950 million of repurchases since late 2025.
The operating story on the call split cleanly in two. Data centers are the engine. Cash revenue grew about 16% versus roughly 12% in the second quarter, and the segment's growth outlook moved to about 16% from 15% last quarter and 13% at the start of the year. Cash mark-to-market renewals were double-digit for a second straight quarter, cross-connects stepped up, and management described demand as "higher than we've ever seen." Towers were the weak side. U.S. new leasing stepped down in the third quarter, and not all carriers were active. Management characterized this as consistent with a front-loaded plan. Cash adjusted EBITDA margin fell about 50 basis points year over year, worse than the 40-basis-point decline in the second quarter.
Guidance reflects the same divergence:
- **Property revenue:** the midpoint rose $55 million, after increases of $110 million and $145 million earlier in the year.
- **AFFO per share:** the outlook moved up just $0.02, to $11.04 to $11.16, attributed primarily to capital allocation.
- **Adjusted EBITDA:** held flat, ending a string of raises. A roughly $10 million data center beat was offset by a $15 million services shortfall tied to a delayed customer build.
- **Discretionary capex:** trimmed by about $40 million.
Earnings Whispers' guidance read is that revenue expectations came in below Street estimates. That sits awkwardly beside the raised property revenue range, and the services cut is the likeliest culprit.
On the catalyst ledger, the Canada tower sale (about $202 million at roughly 26 times 2026 EBITDA) is expected to close this quarter and be immediately accretive to AFFO per share. A new $2 billion buyback authorization lifts remaining capacity to about $3.1 billion. Management now frames Starlink and other satellite players as potential at-scale tenants rather than threats. It also reiterated that 2026 should mark the trough for organic billings and AFFO per share, with an inflection expected in 2027. Bears have legitimate ammunition, though:
- The DISH mediation and AT&T Mexico arbitration remain unresolved, with a Mexico reserve building to about $70 million.
- Net leverage is 4.9x.
- More than $5.3 billion of debt is now classified as current, leaving refinancing costs as a live headwind.
The market had already moved ahead of the report. Investor sentiment swung from -0.23 to +0.19, a meaningful turn from mildly negative to mildly positive. Shares had climbed 11.1% since the open following the July report and sat about 6.3% above the 200-day moving average. The October path was volatile. The stock bounced from a quarterly low of $160.30 on October 5 to a 52-week high of $202.50 on October 23, then gave back about 7% before the release. Earnings Whispers trend readings are uniformly positive, reflecting that recent price strength. Still, a stock that rallied roughly 26% in under three weeks left little cushion for a narrow consensus beat that missed the whisper.
The bottom line is that American Tower delivered a serviceable quarter with a credible data center growth story and shareholder-friendly capital allocation. The headline raise, however, masks a tower business still digesting DISH churn, a stalled EBITDA outlook, and diminishing increments to guidance. With sentiment and price having already re-rated higher, the setup now leans heavily on management's promised 2027 inflection actually showing up in U.S. leasing.
Read our earnings preview for American Tower Corp.: https://www.earningswhispers.com/article/AMT/20677
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 |
