Simply Good Foods Clears A Lowered Q4 Bar, Then Guides FY27 Sales Down As Much As 17% To Rebuild Margins
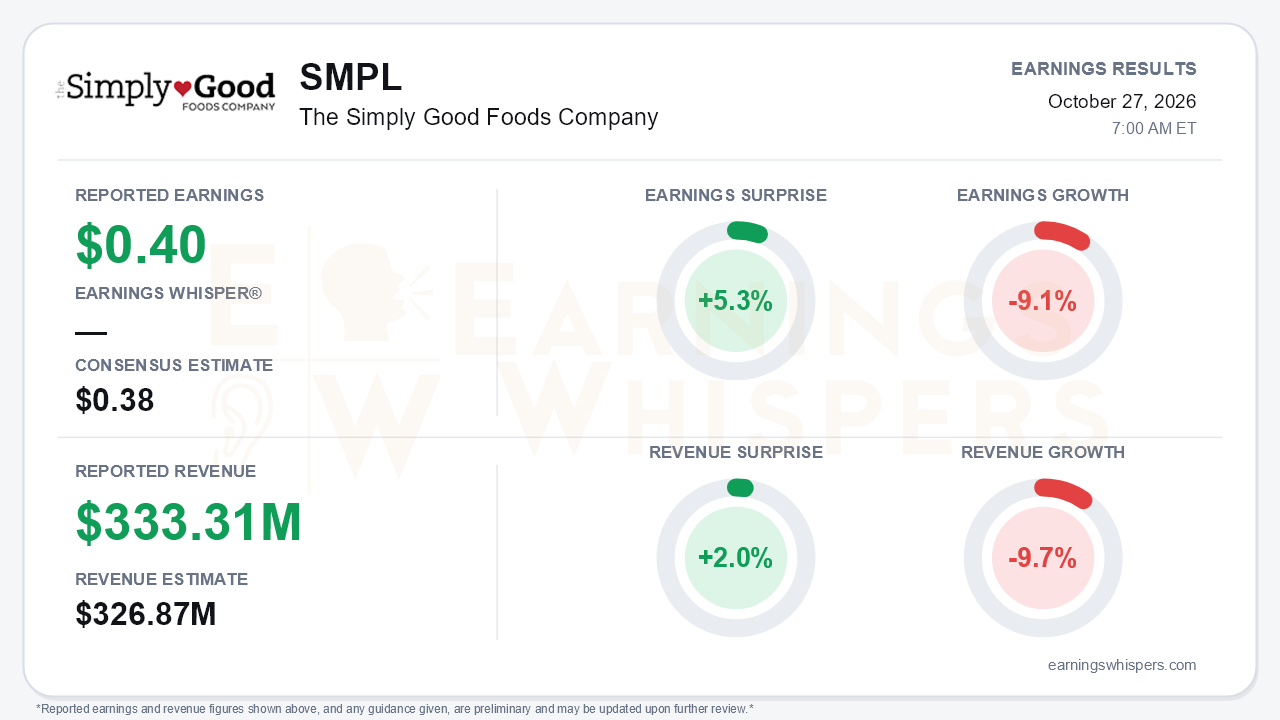
Simply Good Foods (NASDAQ: SMPL) beat a reset set of expectations in its fiscal fourth quarter. The more consequential news was the fiscal 2027 outlook, which deliberately gives up volume to repair margins. Earnings Whispers puts the quarter at $0.40 per share, $0.02 above the $0.38 consensus, a 5.3% surprise. Revenue of $333.31 million beat the $326.87 million consensus by 2.0%. Both lines still shrank: earnings fell 9.1% and revenue fell 9.7% from a year ago. The beat matters less than what management said about next year. FY27 net sales are now guided down 13% to 17%, and the guidance points to revenue below what the Street was looking for. That is the central tension: the quarter showed the reset plan working on paper, while the outlook shows the cost of that plan landing in fiscal 2027.
The quality of the beat deserves scrutiny. The company's own Adjusted Diluted EPS was $0.44 versus $0.46. That differs from the Earnings Whispers figure partly because the company adds back depreciation and amortization. GAAP EPS was $0.34, a swing from a $0.12 loss, but the year-ago loss included a $60.9 million impairment, so the comparison flatters the trend. Per-share results also had help from buybacks. The company spent $213 million on repurchases during the year, and diluted shares fell to 88.5 million from 101.0 million. Without that, the per-share decline would have been steeper than the 13.2% drop in adjusted EBITDA to $57.5 million. Still, there was genuine execution. Sales topped the $322–332 million range given on the Q3 call, and EBITDA landed at the top of its $52–57 million range. Gross margin of 34.0% was the best of the year, up from 32.5% in Q3 and 31.6% in Q2, though still 30 basis points below last year because of input costs.
Beneath the headline, consumption deteriorated. Total retail takeaway worsened to -8.4% from -6.7% in Q3, a sharp reversal from +2% in Q1.
- **Quest:** The brand that held the portfolio together turned negative, with takeaway at -2.1% versus +1.4% in Q3. Bars ran about -6%, and household penetration slipped to 20.2% from 20.5%.
- **OWYN:** Takeaway fell to -7% from -1.3%, and net sales dropped 20.6%. Management expects distribution losses on non-core items over the next six to nine months.
- **Atkins:** Takeaway stabilized at -22.6% versus -23.9%. That is the closest thing to good news, though it is a very low bar.
Quest salty snacks grew 13%, but that growth has slowed from +40% in Q1 and +17% in Q3.
The forward plan is a margin-first reset with real execution risk. A price increase approaching double digits took effect in September, larger than the "high single digit" flagged on the Q3 call. Management is guiding GAAP gross margin up 250–300 basis points in FY27 and pointing toward the brand's roughly 40% historical level. The catch is volume. Management expects price elasticity "well above one," versus a historical range of roughly 1 to 1.2, as products cross key price thresholds, and called it a major unknown. Part of the margin gain is being reinvested, with marketing rising about 90 basis points toward 10% of sales. That comes after a marketing-mix study found past returns ran below consumer-packaged-goods benchmarks. New creative is live across all three brands, including Atkins' Rob Lowe campaign aimed at roughly 23 million lapsed GLP-1 users. The spending is front-loaded, so Q1 FY27 is guided to sales down 19% to 22% and adjusted EBITDA down 28% to 33%. That outlook is well below the Q3 call's suggestion that -6% to -7% consumption was a jumping-off point. The trajectory has now weakened across three consecutive calls.
The balance sheet gives management room to wait. FY26 operating cash flow was about $181 million, slightly above the prior year despite lower sales. Net leverage fell to 0.9x after a $50 million Q4 debt paydown, and cash rose to $138.4 million. About 60% of the roughly $8 million in annualized G&A savings still lies ahead, and capex is guided lower to $15–20 million.
The market had already priced in a great deal of pain. Shares sat at $10.09 ahead of the report, down 32.9% from the $15.03 opening after the July release and 22.9% below the 200-day moving average of $13.10. The stock was just 7.6% above the 52-week low of $9.38 set on September 24. Investor sentiment improved meaningfully but remained negative, moving from -0.36 to -0.14. That suggests expectations were low rather than optimistic. The Earnings Whispers momentum and AVWAP trend readings remain negative.
The bottom line is that Simply Good Foods delivered on its modest Q4 commitments and is executing a coherent margin-rebuild strategy from a position of financial strength. However, consumption is still deteriorating, Quest has lost its growth cushion, and FY27 hinges on pricing elasticity and marketing returns that management itself cannot yet quantify. Bulls can point to gross-margin recovery and depressed expectations. Bears have legitimate ammunition in an outlook that pushes any visible recovery into the back half of fiscal 2027 at the earliest.
Read our earnings preview for The Simply Good Foods Company: https://www.earningswhispers.com/article/SMPL/20725
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Sep-25 | |
| Sep-04 | |
| Sep-04 | |
| Aug-28 | |
| Aug-26 | |
| Aug-24 | |
| Aug-21 | |
| Aug-12 |
