Kiniksa Crushes Estimates As ARCALYST Crosses $1 Billion Run-Rate, But Guidance Implies A Costlier, Slower Q4
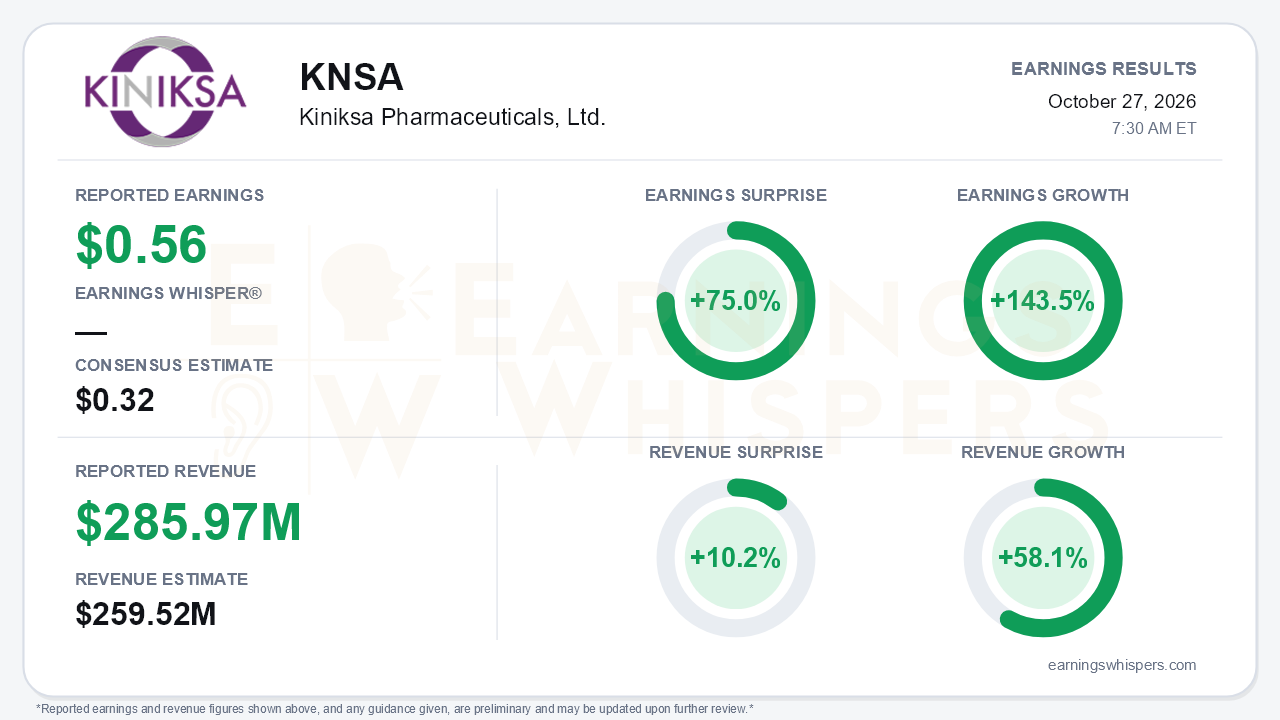
Kiniksa delivered its cleanest beat of the ARCALYST launch. Diluted GAAP earnings of $0.56 per share topped the $0.32 consensus by 75.0% and grew 143.5% year over year. Revenue of $285.97 million beat the $259.52 million consensus by 10.2% and rose 58.1%. The more important development is that growth is speeding up at a scale where it would normally slow. Year-over-year growth moved from 56% in Q1 to 55% in Q2 to 58% in Q3. The roughly $42.5 million sequential revenue gain exceeded Q2's ~$29 million, which management had previously called the largest since launch. Management raised 2026 ARCALYST guidance for the third consecutive time, to $1.045-$1.050 billion from $980-$995 million, which puts the drug past blockbuster status in its current year.
The quality of the beat holds up well. Operating income more than doubled to $54.2 million from $24.0 million a year ago and $27.2 million in Q2. Net income reached $47.3 million versus $18.4 million. Collaboration expenses, which reflect the profit share on ARCALYST, rose to $105.8 million. Collaboration profit climbed 67% year over year to $211.6 million, still outpacing sales growth. COGS grew far more slowly than revenue. SG&A and R&D grew 33% and 36%, respectively, which left substantial operating leverage even with heavier KPL-387 clinical spending. Cash rose to $568.8 million with no debt, up from $414.1 million at year-end.
The operating metrics show a franchise that is broadening rather than just deepening. Penetration of the roughly 14,000 annual multiple-recurrence patients reached about 23%, up from 21% in Q2 and 18% at year-end. Cumulative prescribers rose to about 5,450, an increase of roughly 450 in the quarter. Average therapy duration stands near three years, in line with the median duration of disease, which supports the durability of the revenue base. Management said the share of physicians supporting IL-1 therapy before corticosteroids has doubled to about 50%. The Hearts Home direct-to-consumer campaign, launched in April, produced a 12x lift in website traffic, and the company is expanding it. The tone on the call was noticeably more celebratory, underscored by Ross Moat's promotion to President and COO.
The guidance carries a less obvious message. Subtracting nine-month sales of $743.8 million from the new range implies Q4 ARCALYST revenue of roughly $301-$306 million. That would be a sequential gain of only about $15-$20 million, well below Q3's step-up. Management flagged the usual seasonal rise in Q4 gross-to-net deductions, so the implied figure may be cautious, but it is not an acceleration guide. Costs are moving the other way. The first explicit full-year opex guidance, R&D of $160-$170 million and SG&A of $270-$280 million, implies Q4 R&D of roughly $59-$69 million versus $32.8 million in Q3, and Q4 SG&A of about $80-$90 million versus $65.4 million. KPL-387 pre-commercial manufacturing and expanded commercial and DTC investment drive those increases. Bears also have some ammunition beyond spending. Quarterly net cash generation fell to about $43 million from about $58 million in Q2. Collaboration profit growth has eased steadily, from 83% in Q4 2025 to 67% now.
The pipeline gained clarity. Data from PASTORALE, the pivotal Phase 3 trial of once-monthly KPL-387, is now guided for the second half of 2027, with a targeted 2028/2029 launch. A Phase 1 trial of quarterly-dosed KPL-1161 remains on track to start by year-end. Both programs are lifecycle protection for the IL-1 franchise, but they also introduce a future question: how much a more convenient successor would cannibalize weekly ARCALYST. The PASTORALE readout is now the defining binary event for the next phase of the story.
Investor sentiment improved modestly ahead of the report, rising from 0.19 to 0.22, which is positive but hardly euphoric. The stock entered earnings at $72.98, up just 4.2% since the open after the July report. Shares sit 23.6% above the 200-day moving average but 13.2% below the 52-week high of $84.06 set on October 21. That sharp pre-report pullback suggests some of the anticipated strength had already been priced in and then partially unwound. Sequential-growth and momentum trend readings are positive, while AVWAP remains negative, consistent with recent buyers sitting on losses after the late-October fade.
The bottom line is that Kiniksa produced a high-quality beat-and-raise: accelerating revenue growth, doubling operating income and a blockbuster-level guide. The investment debate now shifts to how gracefully the business absorbs a heavier Q4 cost load and seasonal gross-to-net pressure, and whether KPL-387 can extend the franchise in 2027 without simply replacing it.
Read our earnings preview for Kiniksa Pharmaceuticals, Ltd.: https://www.earningswhispers.com/article/KNSA/21317
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 |
Dow Jones Futures Rise As SpaceX, Supermicro Revive AI Stocks; Tesla, Meta On Deck
KNSA
Investor's Business Daily
|
| Oct-14 | |
| Sep-04 | |
| Aug-07 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-23 | |
| Jun-23 |
Biotech Kiniksa Pushes Toward A Buy Zone With Blockbuster Drug Sales In View
KNSA
Investor's Business Daily
|
| Jun-23 |
Biotech Kiniska Pushes Toward A Buy Zone With Blockbuster Drug Sales In View
KNSA
Investor's Business Daily
|
| May-29 |
