Travel + Leisure Beats On Buyback-Boosted EPS And Raises Guidance A Third Time, But Weak Cash Flow, Higher Leverage, And A Shrinking Exchange Business Cloud The Picture
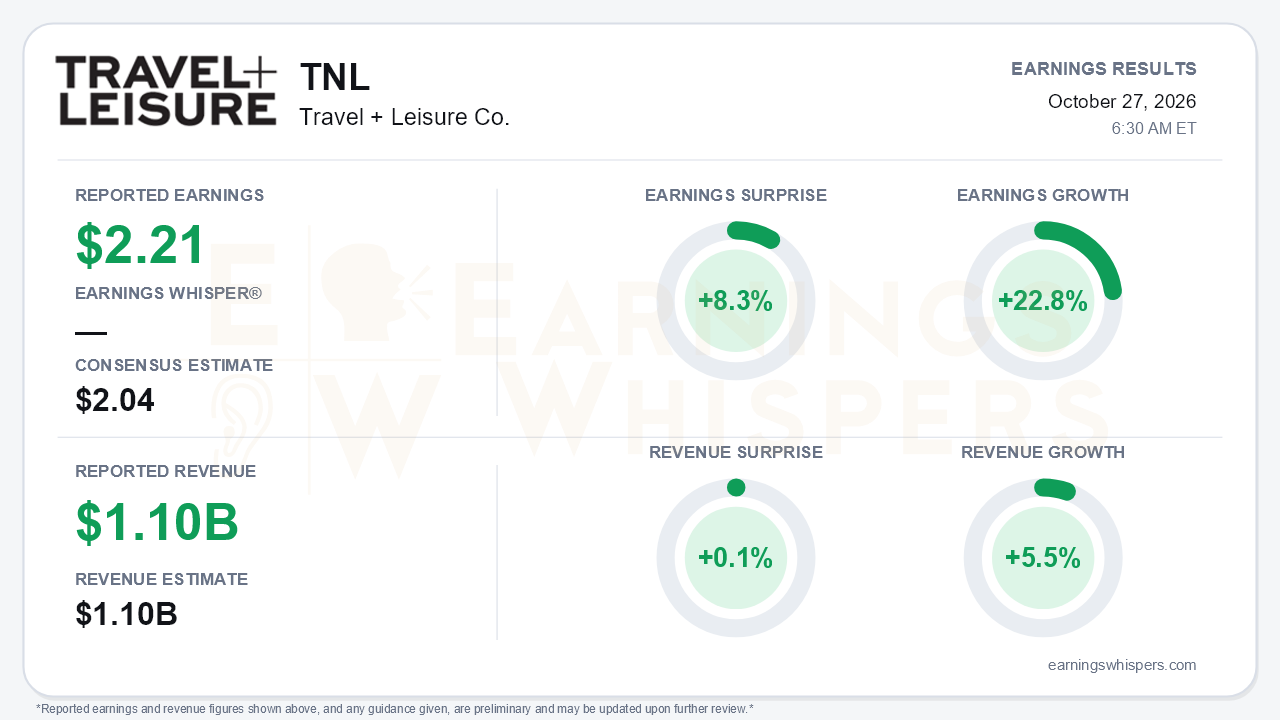
Travel + Leisure Co. (NYSE: TNL) delivered the earnings beat its guidance pointed toward. Adjusted EPS of $2.21 topped the $2.04 consensus by 8.3% and grew 22.8% year over year. Revenue of $1.101 billion rose 5.5% and was essentially in line with the $1.10 billion estimate. Adjusted EBITDA of $283 million rose 6%, landing at the top of the $275–285 million range management set in July. Full-year guidance moved higher for the third consecutive quarter. The central tension is that per-share earnings are growing about four times faster than revenue and EBITDA. Much of the gap comes from capital allocation and below-the-line items rather than operating acceleration.
The quality of the beat deserves scrutiny. Diluted share count fell to 62.6 million from 66.1 million, a reduction of roughly 5% that accounts for a large share of the EPS expansion. On a GAAP basis, the quarter was far less impressive:
- Net income slipped 3% to $108 million.
- Diluted EPS rose only 4% to $1.73.
- Operating income fell to $195 million from $214 million.
The gap between GAAP and adjusted results reflects $18 million of acquisition deal costs and $12 million of restructuring. Those charges are tied to the Yes& Vacations and Spinnaker deals and to cost cuts, so they are explainable. Cash generation, however, moved the wrong way. Nine-month operating cash flow fell to $388 million from $516 million, and adjusted free cash flow dropped to $254 million from $326 million. Marketing expense also jumped 15% in the quarter, outpacing the 7% gain in tours.
The core vacation ownership engine did strengthen:
- **Tours:** Up 7%, a sharp improvement from 1% growth in the second quarter, led by new-owner tours.
- **Gross VOI sales:** Up 6% against a demanding 13% prior-year comparison.
- **Net VOI sales:** Up 10%, helped by a lower loan-loss provision.
- **Credit:** The provision rate fell roughly 150 basis points year over year, its third straight decline. Early-stage delinquencies held at 5.1% from the second to the third quarter despite normal seasonal pressure, effectively erasing the first-quarter credit wobble. Management cut its full-year provision outlook to about 20% from roughly 21% and expects further improvement in 2027.
The soft spot was volume per guest (VPG). It slipped 1% to $3,286 and missed the company's own $3,300–3,350 quarterly guide. Management attributed the decline to dilution from acquisition mix and said organic VPG grew in the low single digits.
Travel and Membership remains the structural drag. Revenue fell 11% to $150 million and segment EBITDA dropped 12% to $51 million. Exchange transactions declined 16% because more members carry club affiliations and transact less often. Travel Club revenue per transaction also fell 17%. Management is responding with $16 million of annualized cost cuts covering roughly 300 employees, but those savings mostly benefit 2027. They offset the decline rather than reverse it.
The call preserved a credible growth narrative. Full-year guidance now stands at:
- Gross VOI sales of $2.625–2.675 billion.
- Adjusted EBITDA of $1.070–1.085 billion.
- EPS growth in the low-20s percent range.
Newer brands are gaining traction. Margaritaville's sales pace was raised to more than $175 million, Accor is nearing $50 million, and a second Eddie Bauer Adventure Club resort was announced. The Sports Illustrated concept will extend into Wyndham hotels, and Club Wyndham points sales begin at acquired Spinnaker and Yes& properties in November. Management reaffirmed its 2027 framework of 6–8% VOI growth and mid-single-digit EBITDA growth. It also identified about $150 million of incremental 2027 liquidity earmarked for buybacks.
Bears have legitimate ammunition, though. Leverage rose to 3.3x from below 3.2x, and liquidity fell to about $900 million from more than $1.2 billion after the acquisitions. Management flagged higher asset-backed funding costs and continued new-brand investment as modest 2027 margin headwinds. A competitor's weaker trends were raised on the call; management said it has seen no impact.
The market had already grown skeptical before the print. Investor sentiment fell from 0.40 at the prior report to 0.07, a substantial deterioration that leaves it only barely positive. The stock entered earnings at $65.62, down 12.1% from the $74.69 open after July's report and 6.9% below its 200-day moving average. Shares sat 17.4% below the August 5 high of $79.49 and 7.6% above the October 1 low of $60.98. The Earnings Whispers trend readings are mixed: price trend and AVWAP are negative, while momentum is positive. The market setup is more complicated than the surprise implies. Fundamentals have improved all year even as the stock has given back its post-July gains.
The bottom line is that Travel + Leisure produced a cleaner core timeshare quarter than its share price suggests, with accelerating tours, improving credit, and a third guidance raise. The headline EPS growth, however, leans heavily on buybacks and adjustments, while GAAP earnings, cash flow, and the exchange business tell a softer story. With leverage higher and liquidity lower after a $350 million acquisition push, the case now rests on proving that those deals restore organic VPG growth and generate the cash needed to keep the buyback engine running.
Read our earnings preview for Travel + Leisure Co.: https://www.earningswhispers.com/article/TNL/20730
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-23 | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-02 | |
| Sep-30 | |
| Sep-16 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 |
