Pentair Beats As Pool Destock Ends, But A Reset $4.70 Outlook Keeps The Rebuild Story Unproven
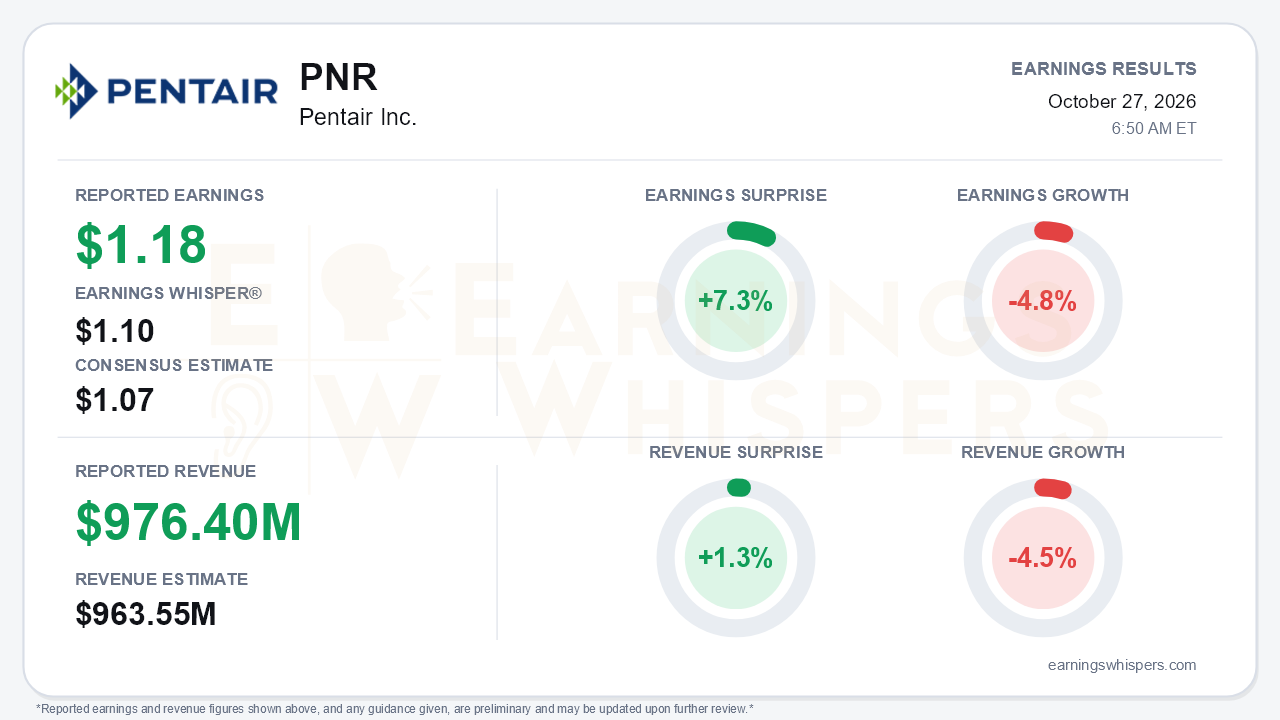
Pentair delivered the clean beat it needed after a bruising second quarter. Adjusted EPS of $1.18 topped the $1.07 consensus by 7.3%, cleared the $1.10 Earnings Whisper number, and beat management's own $1.05-$1.08 guide. Revenue of $976.4 million beat the $963.55 million consensus by 1.3%. Both lines still contracted, with earnings down 4.8% and revenue down 4.5% year over year. But that is a sharp improvement from the second quarter, when adjusted EPS fell to $1.14 from $1.39. The central takeaway is stabilization, not re-acceleration. The Pool channel destock is over, Taco has closed, and the full-year adjusted EPS target of roughly $4.70 has held. That target is still well below the $5.30-$5.40 management guided in the first quarter.
The quality of the beat deserves some scrutiny.
- **GAAP versus adjusted.** GAAP EPS fell 19% to $0.91. The gap to the adjusted figure came from $11.4 million of restructuring, $16.1 million of transformation costs, deal costs, and $4.9 million of bridge-financing fees.
- **One-time help.** Results included about $8 million of IEEPA tariff refunds.
- **Below-the-line support.** Diluted shares fell to 160.3 million from 165.1 million after $350 million of buybacks year to date. That cushioned per-share results.
- **Rising costs.** Net interest expense climbed to $21.7 million from $14.4 million. SG&A rose to 18.0% of sales from 15.9%.
- **Margins and cash.** Adjusted ROS slipped 90 basis points to 24.8%. Free cash flow of $153 million trailed last year's $179 million.
The beat was real, but it came from better-than-feared Pool volumes rather than broad operating leverage.
The segment detail tells a split story. Flow and Water Solutions kept expanding margins despite roughly 1% core growth. Flow ROS rose 250 basis points to 26.2%, and Water Solutions ROS rose 370 basis points to 28.7%. Pool sales fell 18%, better than the guided 23%-25% decline, but Pool ROS fell 820 basis points to 24.6% on volume deleverage and growth investment. On the call, management said the destock is complete: about $190 million in the second quarter and $90 million in the third. Sell-through returned to mid-single-digit growth. Management framed 2027 Pool sales at about $1.45 billion, roughly 14% growth at around 30% ROS, assuming no market recovery. If Pool sell-in simply matches sell-through, the 2027 math is unusually visible. That is the credible core of the bull narrative.
The guidance was genuinely mixed.
- **Raised or narrowed.** Full-year sales are now expected to be down about 3% including Taco, versus down 4%-7% previously. The Pool decline range narrowed to 18%-19%.
- **Cut.** Flow growth was trimmed to mid-single digits because of food and beverage spending delays. Water Solutions core was cut to roughly flat, as residential demand stays weak on housing starts and mortgage rates.
- **Fourth quarter.** Adjusted EPS guidance of about $1.15 sits below last year's $1.18, even with reported sales up 7%-9%. Core sales are still guided down 2%-3%.
- **Headwinds into 2027.** Tariff refunds totaled $43 million, at the low end of expectations, and will not recur. Pro forma leverage rises to about 2.5x after a $1.4 billion term loan at roughly 5.25%.
On the positive side, Taco is tracking ahead of deal-time expectations, with about $560 million of 2026 sales and EBITDA rising from roughly $90 million toward more than $105 million. Management expects it to be EPS-accretive in 2027. A new Pool chief executive, a dealer-focused plan, 3%-4% Pool price increases, and a new permanent CFO arriving November 1 round out the catalysts. Bears still have legitimate ammunition. Management has not quantified Pool share recovery, and some independent dealers alienated by prior 80-20 actions may be slow to return.
Investors came into the print skeptical. Earnings Whispers sentiment deteriorated meaningfully, from -0.18 to -0.31. As of the pre-report snapshot, shares were down 13.8% since the open after the July report, at $55.22, and sat 28.4% below the $77.08 200-day moving average. The stock set a 52-week low of $51.13 on October 8 and entered earnings only 8% above it, 22% below the August high of $70.97. The Earnings Whispers trend signals lean negative, with momentum and AVWAP both deteriorating while price trend is neutral. The market is pricing the guidance reset, not the 2027 recovery framework.
That creates a market setup more complicated than the surprise implies. Expectations were low enough that a beat plus a completed destock could matter. But the full-year number was held, not raised, and two of three segments saw growth outlooks trimmed. The strongest arguments rest on 2027 assertions rather than reported results.
The bottom line is that Pentair turned a crisis quarter into a stabilization quarter. It beat on both lines, ended the Pool destock, and closed Taco with momentum. The rebound is still from a reset base, with GAAP earnings sharply lower, core sales still shrinking, and refund tailwinds about to disappear. The 2027 Pool math is the story investors will now hold management to.
Read our earnings preview for Pentair Inc.: https://www.earningswhispers.com/article/PNR/20719
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| 10 hours | |
| 14 hours | |
| Oct-19 | |
| Oct-14 | |
| Oct-01 | |
| Sep-28 | |
| Sep-28 | |
| Sep-25 | |
| Sep-22 | |
| Sep-22 | |
| Sep-21 | |
| Sep-18 | |
| Sep-09 |
