Noble Misses Badly As The Earnings Trough Extends, But 2027 Contracting Momentum Builds
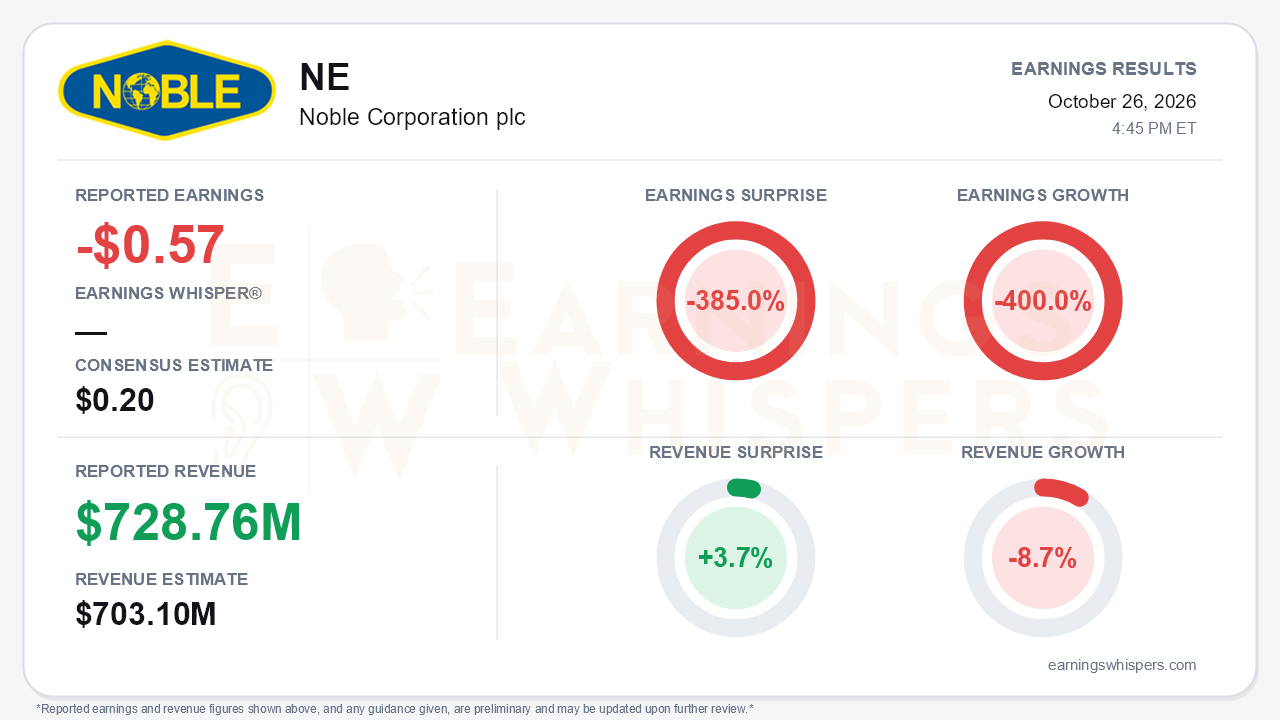
Noble Corporation plc (NYSE: NE) posted a sharp third-quarter earnings miss. It reported an adjusted loss of $0.57 per share against a consensus estimate of $0.20 in earnings, a -385.0% surprise. Adjusted EPS fell 400.0% from a $0.19 profit a year earlier. Revenue was the brighter spot: $728.76 million topped the $703.1 million consensus by 3.7%, though it was still down 8.7% year over year. That is the central tension. The current quarter is getting worse, while the 2027 contract book is getting better. Investors are being asked to look through a trough that management now expects to last longer.
The quality of the miss deserves scrutiny, because much of it sits below the operating line. Operating income rose to $60 million from $50 million a year ago, and pretax income was positive at $16 million. The problem was taxes. A $133 million tax provision produced a GAAP net loss of $117 million, or $0.73 per share. Even after adjustments, the adjusted tax provision was still $117 million, which is why adjusted EPS swung from a 1-cent profit in the second quarter to a 57-cent loss.
That said, operations offer no offset. Adjusted EBITDA slipped 5% sequentially to $201 million, down from $212 million in the second quarter and $277 million in the first. The adjusted EBITDA margin compressed to roughly 28% from 30% and 35% over the same span. Contract drilling costs rose to $469 million from $446 million as several rigs moved between contracts. Average floater dayrates also drifted down to about $403,000 from $413,000 in the prior quarter.
Utilization disclosures need care because they use different bases:
- The release text, which covers marketed rigs, shows marketed-rig utilization improving to 70% from 67%, and ultra-harsh jackups at 86% versus 80%.
- The operating table, which also includes cold-stacked rigs, shows jackup utilization falling to 79% from 83%, with jackup operating days down to 579 from 651.
Cash flow is the sharper issue. Free cash flow was -$48 million after -$59 million in the second quarter, as capex of $192 million outran $144 million of operating cash flow. Cash has fallen to $337 million from $471 million at year-end. Meanwhile, the $0.50 quarterly dividend was maintained, and dividends have consumed $243 million so far this year.
The forward picture is where the call earned its credibility.
- **New awards:** Noble booked roughly $560 million of new contracts, versus about $200 million in the second quarter. The awards spanned TotalEnergies in Nigeria, Tullow in Ghana, Occidental in Peru and a roughly 670-day ConocoPhillips plugging-and-abandonment program at Ekofisk.
- **2027 backlog:** Backlog scheduled to convert in 2027 rose to $2.6 billion from $2.3 billion.
- **2027 slope:** Contracted capacity in the second half of 2027 is about 20% above the first half. That reverses the pattern of the prior two years, when second halves trailed first halves.
- **Pricing:** Leading-edge Tier-1 drillship rates climbed to the mid-$400,000s to $500,000 per day, from the mid-$400,000s last quarter. Ultra-harsh jackup rates of $230,000 to $300,000 replaced last quarter's flat commentary.
- **Industry supply:** Contracted ultra-deepwater rigs reached 109 of 110 marketed units, and management floated the possibility of a fully sold-out high-end market within about a year.
Bears still have legitimate ammunition, starting with guidance.
- **EBITDA:** Full-year adjusted EBITDA guidance was narrowed to $850 million to $900 million, trimming the top end from $925 million. That follows a deeper cut last quarter tied to Brazil.
- **Near-term trajectory:** Fourth-quarter EBITDA is guided slightly below the third quarter, and the first quarter of 2027 is expected to be roughly similar.
- **Revenue:** The low end of revenue guidance was raised, but mainly on reimbursables rather than core dayrate revenue.
- **Capex:** Full-year capex guidance rose to $680 million to $705 million. Most of the increase is customer-reimbursable, but inflation is pushing normalized capex toward about $400 million.
- **Backlog:** Total backlog edged down to $6.7 billion from $6.8 billion, well off $7.5 billion earlier in the year.
- **Long-range targets:** Management did not explicitly reiterate its earlier second-half 2027 run-rate framework of $1.3 billion in EBITDA and $600 million in free cash flow.
- **Operating soft spots:** The U.S. Gulf remains weak, open 2027 capacity persists on several rigs, and the Voyager start slipped a few weeks.
The market had already leaned into the recovery narrative. Shares opened at $40.25 after the July report and now sit at $47.81, up 18.8%. That leaves the stock about 8.2% above its 200-day moving average of $44.18. Investor sentiment moved the other way, but only modestly: it eased to 0.016 from 0.035, still marginally positive and essentially neutral. The Earnings Whispers trend readings lean negative, with sequential growth and momentum deteriorating, although AVWAP remains positive. In practice, the stock has been priced for the 2027 inflection while near-term numbers keep sliding.
The bottom line is that Noble delivered an ugly, tax-amplified earnings miss and another step down in EBITDA and cash flow, but a genuinely stronger contracting quarter. Pricing and the shape of 2027 backlog improved in ways that support management's call for a meaningful inflection starting in the second half of 2027. The investment question is timing. With the trough now extending into early 2027, free cash flow negative and the dividend being funded from a shrinking cash balance, the 19% rally since July leaves little cushion if the second-half ramp slips.
Read our earnings preview for Noble Corporation plc: https://www.earningswhispers.com/article/NE/20660
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Sep-04 | |
| Aug-12 | |
| Jul-29 | |
| Jul-27 | |
| Jul-27 | |
| Jul-14 | |
| Jul-09 | |
| Jun-05 | |
| Jun-01 | |
| Jun-01 | |
| May-27 |
