Flexsteel's Demand Re-Accelerates, But An FX Hit, Freight Inflation And Buyback-Aided EPS Cloud The Quarter
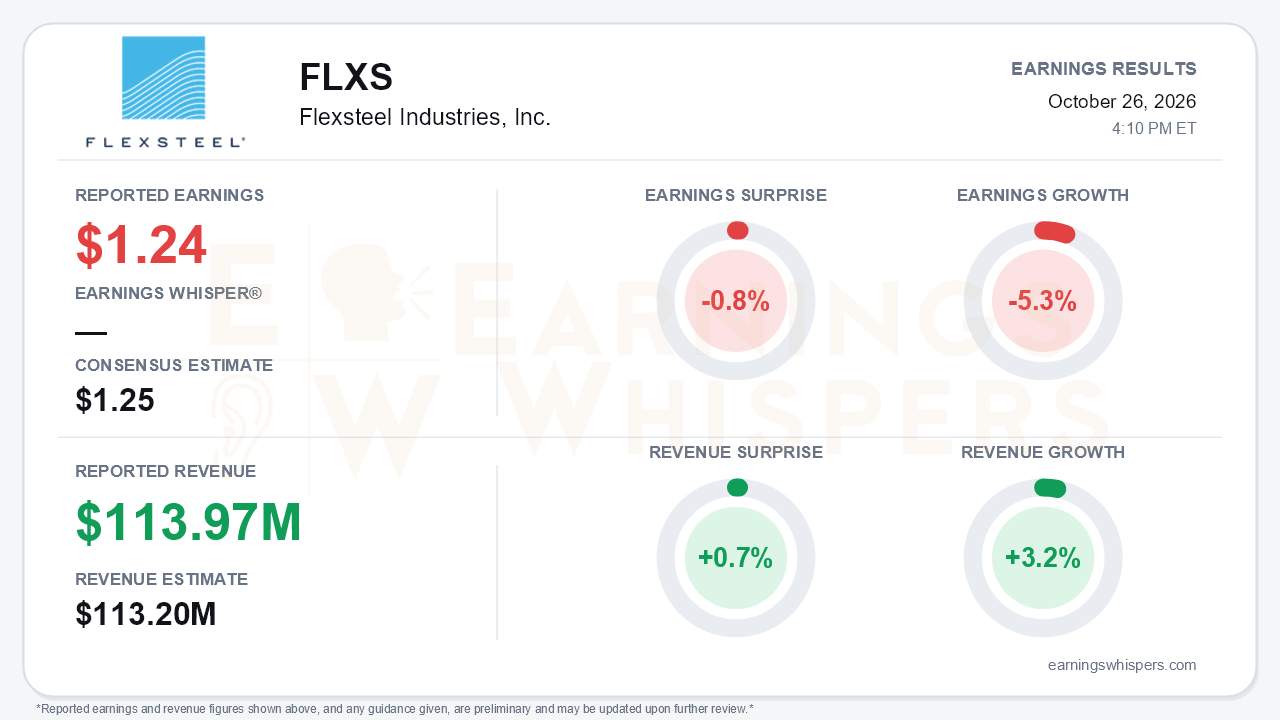
Flexsteel Industries (NASDAQ: FLXS) delivered a fiscal first quarter where demand and profits moved in opposite directions. Revenue of $113.97 million topped the $113.2 million consensus by 0.7% and grew 3.2% year over year, a clear acceleration from roughly 1% growth in fiscal Q3 and 0.7% in Q4. Earnings went the other way: GAAP EPS of $1.24 missed the $1.25 consensus by 0.8% and fell 5.3% from a year ago. The miss is small, but it hides a sharper decline in profitability. The top line is getting healthier while the margin structure is under real pressure, and that is the central tension.
The quality of the EPS figure deserves scrutiny. Net income fell to $5.4 million from $7.3 million, a much steeper drop than per-share earnings suggest. The gap closed only because diluted shares fell to 4.37 million from 5.60 million after the company's $62.6 million buyback. GAAP operating margin was 6.0%, compared with 8.1% a year earlier and below the 6.5% to 7.0% range management had guided for the quarter. Gross margin slid 150 basis points to 22.0%, and 130 basis points of that came from peso translation losses on Mexican assets and energy-driven inflation. SG&A climbed to 16.0% of sales from 15.4% as Flexsteel kept spending on consumer insights, product development and marketing. Management attributed about 70 basis points of the operating-margin shortfall, or $0.8 million, to FX and said margins were in line with plan excluding that item. The underlying pressure, however, did not come from currency alone.
The call is where the bullish argument got stronger. Orders rose about 5%, a decisive turn from a 2.4% decline in fiscal Q3. Backlog reached $77.7 million, up 8.2% year over year, after gains of 5.5% in Q4 and just 1.5% in Q3. Excluding the Homestyles ready-to-assemble business being exited, which fell 57.6%, the Flexsteel brand grew 5.1%. Pricing was up roughly 10%, and unlike the prior two quarters, management pointed to real unit growth in strategic accounts, health and wellness, and immersive sound rather than unit declines offsetting price. The tone shifted noticeably. Last quarter's guarded "limited visibility" language gave way to statements that the company is "not relying on a recovery" and is optimistic about accelerated growth.
The product pipeline from Fall High Point gives that optimism some substance:
- the 6000 series with sixth-generation SixFlex spring technology and the Comfort Choice program;
- wellness expansion into nursery, restorative and mobility-assist categories;
- a second-generation Pulse system billed as the first fully Dolby Atmos-certified integrated furniture soundbar, backed by an expanded Dan Patrick partnership.
The cost side is the problem. Ocean freight has nearly doubled in six months, and management expects $1.5 million to $2 million of incremental inflation per quarter to persist into Q2. The Section 232 upholstered furniture tariff steps up from 25% to 30% on January 1, 2027, which will likely require further pricing on top of a planned 2% to 3% increase. Rising mortgage rates and weak consumer confidence remain headwinds.
Guidance sets up a credibility test. Q2 sales are guided to $119.5 million to $123.0 million, up 1% to 4%, or 3.5% to 6.5% excluding Homestyles, and that range sits above Street expectations. The operating margin target of 6.5% to 7.0%, however, is the same range Flexsteel just missed, and it must now be hit with inflation still running. The balance sheet has also thinned considerably. Cash fell to $4.4 million from $16.7 million at year-end and $57.3 million in fiscal Q3, operating cash flow was negative $1.5 million, and the company paid $6.5 million in tax withholding on vested shares. Liquidity remains adequate, with $29.1 million of credit availability and $80.5 million of working capital, but the cushion for continued buybacks is now limited.
Investor sentiment cooled meaningfully heading into the report. It slipped from a modestly positive 0.18 to a slightly negative -0.04, suggesting enthusiasm had faded even as the order data improved. Shares have gone mostly sideways, up just 1.9% from the $81.00 open after the August report to $82.55. They still sit about 31% above the 200-day moving average, reflecting a substantial earlier rerating that has paused rather than reversed. The Earnings Whispers trend signals are largely neutral, with AVWAP the notable positive.
The bottom line is that Flexsteel's demand story improved materially this quarter, with accelerating sales, positive orders and a growing backlog, while its earnings story deteriorated. Margins are being squeezed by freight, energy, tariffs and FX, and a shrinking share count is flattering per-share results. Bulls have a credible growth narrative and a revenue outlook above estimates. Bears have legitimate ammunition in a missed margin guide, a reaffirmed margin target that now looks demanding, and a much leaner cash position.
Read our earnings preview for Flexsteel Industries, Inc.: https://www.earningswhispers.com/article/FLXS/20651
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Sep-25 | |
| Sep-15 | |
| Sep-11 | |
| Aug-24 | |
| Aug-19 | |
| Aug-17 | |
| Aug-17 | |
| Aug-03 | |
| Jun-10 | |
| May-20 | |
| May-18 |
