TPG RE Finance Trust Misses As A $13 Million REO Loss Overshadows Its Most Aggressive Growth Quarter
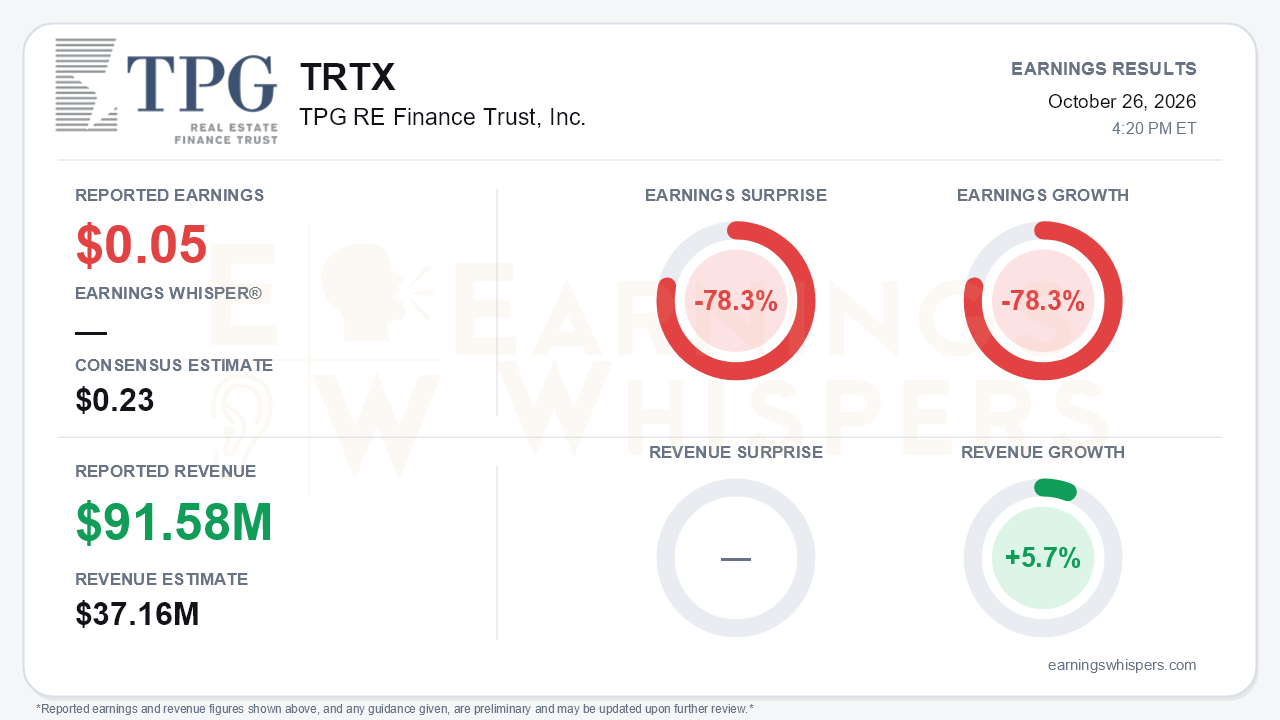
TPG RE Finance Trust (NYSE: TRTX) delivered a quarter of two very different stories, and the credit story won the headline. Earnings Whispers recorded EPS of $0.05 against a $0.23 consensus, a 78.3% miss, with earnings down 78.3% year over year. Revenue of $91.58 million beat the $37.16 million consensus by 146.4% and grew 5.7% from a year ago, although a gap that wide suggests the revenue figure and the consensus are measured on different bases, so the revenue beat says little about the quarter. The company's own figures differ from the normalized EPS: GAAP net income was $5.8 million, or $0.08 per share, and Distributable Earnings were $0.07. Every measure lands in the same place. A $13 million realized loss on a multifamily loan converted to real estate owned pushed reported earnings far below the $0.24 dividend.
The quality of the miss deserves a closer look rather than outright dismissal. Distributable Earnings before realized losses were $0.24 per share, which exactly covered the dividend. Net interest income rose 13% sequentially. The core lending engine is producing more income, not less. The problem is the trend in the bottom line: Distributable EPS fell from $0.25 in Q1 to $0.23 in Q2 and then to $0.07 in Q3, while GAAP net income dropped from $15.2 million to $9.4 million to $5.8 million. Book value per share has also declined steadily, from $11.07 at year-end to $10.85. The allowance for credit losses fell to 147 basis points of commitments from 179, but the call made clear this reflected the REO charge-off moving through the reserve, not improving credit. The loan was resolved at roughly a 27% discount to par.
On the growth side, management pressed hard. Originations reached $773 million, up from $466 million in Q2 and $148 million in Q1. The weighted average spread on new loans widened to 3.02% from 2.79% and 2.73%. Net earning assets grew $600 million to $4.9 billion, up 14% sequentially and 36% year over year. Late-quarter closings point to further gains in net interest income in Q4. New multifamily loan spreads are widening by 15 to 50 basis points while liability costs remain locked at tighter levels, which supports margins. That is the central tension. TRTX is putting capital to work at better spreads at the same moment its legacy multifamily book is producing realized losses.
The growth push also consumed most of the balance sheet's spare capacity. Leverage rose to 4.03x from 3.32x in Q2, above the 3.5x to 3.75x target management had repeated in earlier quarters. Management now describes future growth as "one-in, one-out." Near-term liquidity fell to $291.6 million from $488.2 million, and available financing capacity dropped to $1.2 billion from $1.8 billion. The post-quarter $1 billion FL8 CLO helps on several fronts:
- It lifts non-mark-to-market financing to about 85% from 78.8%.
- It adds a 30-month reinvestment period.
- It generated roughly $43 million of net cash.
However, CLO spreads have since widened by about 25 basis points. A second Sunbelt multifamily loan was modified after a vacancy spike. Management's macro tone has also cooled noticeably, from earlier descriptions of an "incredibly active" market to persistent inflation, higher-for-longer rates, falling acquisition activity and longer closing timelines. Bears have legitimate ammunition. The entire portfolio is still performing and the average risk rating is unchanged at 3.0, but the first realized loss of this cycle has arrived alongside a second modification.
Investors had already turned against the stock before the report. Earnings Whispers sentiment swung from mildly positive (0.067) to clearly negative (-0.255), a meaningful deterioration. Shares are at $6.25, down 25.1% from the $8.35 open after the July report and 22.4% below the 200-day moving average of $8.05. Price and AVWAP trend readings remain negative. One detail stands out: TRTX repurchased 1.2 million shares at an average of $8.00 during the quarter and then doubled its buyback authorization to $50 million. The stock now trades well below both that purchase price and the $10.85 book value, which gives the new authorization real potential to add to book value per share, provided liquidity allows it to be used.
The bottom line is that TRTX's miss came from one realized credit loss, not a broken earnings engine, and its core earnings still covered the dividend. The harder question is sustainability. Leverage is above target, liquidity is thinner, book value keeps edging lower, management's macro outlook has softened, and Sunbelt multifamily stress is spreading. The market has already priced in substantial skepticism. For the stock to recover, the next few quarters must show that higher-spread originations can outrun further legacy losses without stretching the balance sheet.
Read our earnings preview for TPG RE Finance Trust, Inc.: https://www.earningswhispers.com/article/TRTX/20669
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-14 | |
| Sep-17 | |
| Sep-15 | |
| Sep-08 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-15 | |
| Jun-12 | |
| Jun-08 |
