Itron Crushes EPS Guidance On Margin Gains, But Thin Organic Growth And A Trimmed Revenue Range Temper The Beat
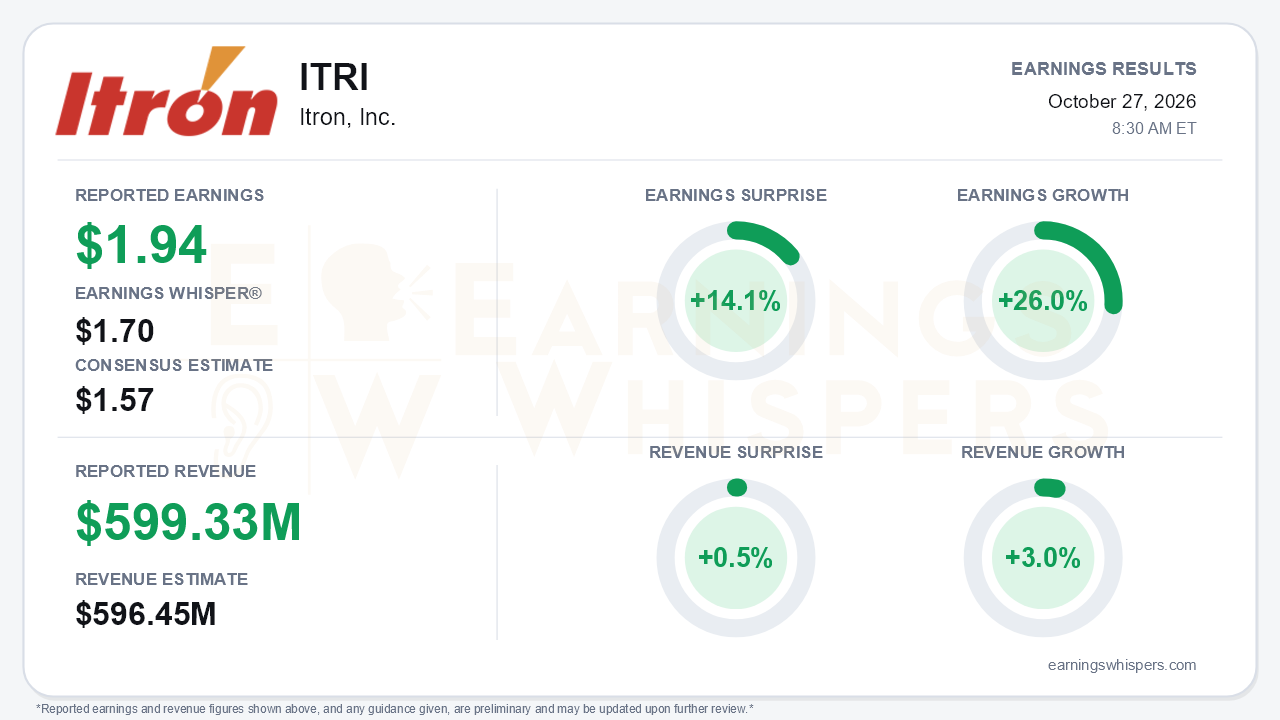
Itron delivered the kind of earnings beat that tends to change a conversation. Non-GAAP EPS of $1.94 cleared the $1.57 consensus by 14.1%, topped the $1.70 Earnings Whisper number, and blew through management's own $1.50 to $1.60 outlook. Earnings grew 26.0% year over year, while revenue of $599.33 million rose 3.0% and edged past the $596.45 million consensus by 0.5%. After declines in the first two quarters, that 3% gain marks the revenue inflection management had promised. The central tension is that this is still overwhelmingly a margin story. The top-line recovery is narrow and partly acquired, and the revenue outlook moved the wrong way even as EPS guidance rose for a second straight quarter.
The quality of the beat deserves scrutiny. Adjusted gross margin reached 41.3%, up 350 basis points from a year ago and close to the second quarter's record 41.4%, which management credited to customer and product mix and operational efficiencies. Non-GAAP operating income rose 20% on that 3% revenue gain, and adjusted EBITDA hit a record $115 million. Device Solutions stood out, with adjusted gross margin up roughly 450 basis points despite a 2% revenue decline.
The per-share growth, however, had help from outside operations:
- Diluted shares fell to 44.4 million from 46.7 million after $152 million of buybacks.
- The company cited lower non-GAAP taxes.
- Working against it, interest income roughly halved to $7.2 million as cash was spent on acquisitions.
GAAP EPS rose a more modest $0.20 to $1.61. Free cash flow also declined to $96 million from $113 million, reflecting working capital, higher cash taxes and lower interest income.
The revenue picture beneath the headline is softer than "returning to growth" implies. Resiliency Solutions, built from the Urbint and Locusview acquisitions, contributed $16 million, which is essentially the entire year-over-year increase. Excluding that contribution, revenue was roughly flat:
- Device Solutions fell 1% in constant currency on lower legacy gas product sales.
- Networked Solutions slipped 1% on deployment timing.
- Outcomes grew 9%, extending a deceleration from 20% in the first quarter and 13% in the second.
- Resiliency revenue has been flat at about $16 million per quarter.
ARR is the more encouraging recurring-revenue signal, with growth accelerating to roughly 25% from 21% to reach $423 million.
Forward indicators are mixed. Bookings of $482 million rose 27% year over year, and management said October gave a strong start to the seasonally largest bookings quarter. New wins include an expanded PG&E wildfire-detection deployment, a Pepco distributed-energy program in the constrained PJM region, and several Resiliency cross-sells. Management also described a gas endpoint award pipeline at multiples of its normal run rate over the next two to three years, though none of it is yet in bookings or the P&L.
Bears still have legitimate ammunition on the forward picture:
- Backlog has drifted from $4.5 billion at the end of 2025 to $4.3 billion.
- The full-year revenue range narrowed to $2.37 to $2.385 billion, trimming the midpoint by about $12 million.
- Full-year EPS guidance rose to $6.72 to $6.82 from $6.30 to $6.50. The roughly $0.37 midpoint increase essentially reflects the third-quarter outperformance rather than a stronger fourth-quarter view.
- Fourth-quarter EPS guidance of $1.70 to $1.80 sits below the third-quarter result. Management flagged that low third-quarter opex was partly timing and should step up.
Earnings Whispers characterizes the outlook as below estimates, which fits most naturally with the softer revenue range and that implied sequential EPS dip. The fourth-quarter revenue guide does imply about 10% growth, so execution on Caribbean, Southeast and Northeast deployments now carries real weight.
The market setup is more complicated than the surprise implies. The stock spiked to $108.20 on the day of the July report and then gave back all of it, sliding to an inter-earnings low of $81.16 on October 19. At $87.73 heading into this report, shares were 4.4% below the open following the prior release, 18.9% under the quarter's high and 3.6% below the 200-day moving average. Investor sentiment improved from -0.29 to -0.14, a meaningful move toward neutral but still on the negative side. The Earnings Whispers trend signals lean negative, with price and AVWAP readings weak while momentum and sequential growth are neutral. Taken together, the market has been skeptical that margin gains can substitute for organic growth.
The bottom line is that Itron proved again that its operating model can generate outsized earnings on modest revenue, and management's talk of a structurally "higher floor" is backed by a third consecutive quarter of 41%-plus gross margins. What the quarter did not resolve is the organic growth question. Revenue growth was essentially acquired, backlog keeps easing, Outcomes is decelerating, and the revenue range tilted lower. Until bookings strength and the gas pipeline translate into backlog and fourth-quarter deployments, investors are likely to keep weighing a credible earnings story against an unproven top line.
Read our earnings preview for Itron, Inc.: https://www.earningswhispers.com/article/ITRI/20706
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-22 |
