Welltower Raises Guidance Again As Seniors Housing Pricing Power Carries A Narrow Beat Through A Darker Macro Backdrop
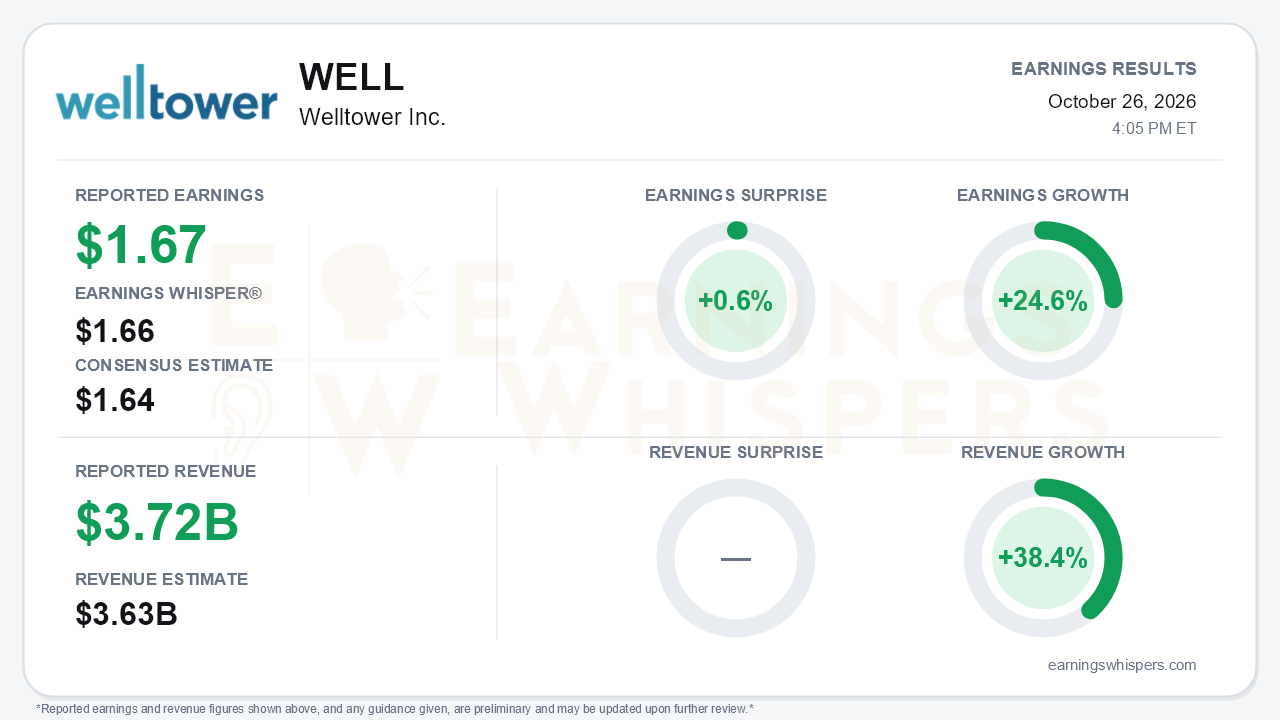
Welltower delivered another quarter in which operations outran expectations, though by a thinner margin than the guidance raise might suggest. Normalized FFO of $1.67 per share topped the $1.64 consensus by 0.6% and edged past the $1.66 Earnings Whisper number. That marked 24.6% year-over-year growth and continued the sequential climb from $1.47 in the first quarter and $1.60 in the second. Revenue of $3.716 billion beat the $3.63 billion consensus by 2.4% and rose 38.4%, driven by a resident-fee line that jumped to $3.12 billion from $2.06 billion. Management lifted the full-year normalized FFO range to $6.47-$6.53 from $6.36-$6.44, the third consecutive raise. The midpoint has now moved from $6.17 at the start of the year to $6.50. The central tension is that this machine keeps compounding even as the macro environment management described has deteriorated sharply.
The quality of the beat deserves some scrutiny. Net normalizing items rose to $0.25 per share from $0.14 a year ago. The main driver was $124.7 million of other expenses, chiefly transaction costs and legal fees tied in part to the HC-One restructuring. NAREIT FFO was a less flattering $1.42, versus $1.20 last year. The full-year NAREIT FFO outlook actually fell to $6.07-$6.13 from $6.21-$6.29, even as normalized guidance rose. GAAP net income guidance rose to $3.31-$3.37, but that increase leans on larger expected disposition gains. For a serial acquirer, excluding deal costs is defensible. Still, the gap between normalized and NAREIT figures is widening as deal volume accelerates. Dilution is also real: diluted shares rose roughly 10% year over year, which is why normalized FFO dollars grew faster than per-share results.
Beneath the headline, the operating story remains genuinely strong, and its mix is shifting. Seniors Housing Operating same-store NOI grew 21.0% and total portfolio SSNOI grew 15.8%, up from 15.5% in the second quarter but still below the first quarter's 16.4% peak. The more important change is the handoff from occupancy to rate. Year-over-year occupancy gains have eased from 370 basis points to 330 to 320. Meanwhile, RevPOR growth accelerated from 5.0% to 5.2% to 5.3%, topping 6% in communities above 90% occupancy. Management called this the best pricing environment in 11 years. Expense discipline amplified the effect. ExPOR rose just 0.8%, full-year ExPOR guidance fell to about 0.6% from roughly 1%, and incremental flow-through reached a post-COVID high of 66%. SHO margin expanded 310 basis points to 31.7%. Management narrowed SHO SSNOI guidance upward to 20.25%-21.75%. The softer spots were seniors housing triple-net, where SSNOI growth slowed to 4.2% from 5.2%, and a non-same-store pool that lags on occupancy and margin because of low-occupancy acquisitions and operator transitions.
The forward catalyst is capital deployment. Year-to-date investments closed or under contract reached $21.0 billion, up from about $15.5 billion at the second-quarter call, with $7.7 billion pending across 50 deals. More than half of the pending deals involve sellers taking operating partnership units, which reduces reliance on public equity issuance. Management framed the $10-$12 billion annual seniors housing debt maturity wall in 2027-28 as a source of forced sellers. Other developments included full repayment of the $130 million Genesis term loan and roughly $850 million of off-market skilled nursing purchases. Bears have legitimate ammunition, however. Management cited a September Fed hike, 3.7% inflation, a 5.36% 10-year yield and oil above $100, alongside private credit defaults near 6% and CMBS delinquencies above 8%. Net debt to adjusted EBITDA has drifted up from 2.73x to 3.02x. Cash has fallen to $2.3 billion from $6.8 billion a year ago, with $1.04 billion now drawn on the credit facility and commercial paper. Higher G&A also partly offset the guidance raise.
Investor sentiment improved meaningfully but from a low base. It rose from essentially neutral at 0.0081 to a modestly positive 0.1398. The stock has not rewarded the fundamentals since the last report: at $240.61, shares were 4.3% below the $251.40 open following the July release. They still sit 10.6% above the 200-day moving average of $217.47. That suggests consolidation within a longer uptrend rather than a breakdown, plausibly reflecting rate pressure on REIT valuations more than doubts about operations. The Earnings Whispers trend readings are mostly positive, with sequential growth and momentum constructive while the price trend is neutral.
The bottom line is that Welltower's quarter reinforced a credible compounding story built on accelerating pricing, record flow-through and a deepening acquisition pipeline, with a dividend raised to $0.85 at a 51% payout. The narrow EPS beat, rising normalizing items, slightly higher leverage and a hostile rate backdrop mean the setup is more complicated than another guidance raise implies. Investors should watch whether rate growth keeps offsetting moderating occupancy gains and whether $7.7 billion of pending deals closes on accretive terms.
Read our earnings preview for Welltower Inc.: https://www.earningswhispers.com/article/WELL/20671
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 8 hours | |
| 8 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-25 | |
| Oct-14 | |
| Oct-07 | |
| Oct-05 |
