Polaris Crushes Q3 And Raises Guidance A Third Time, But A Q4 Pull-Forward And Commodity Costs Cloud 2027
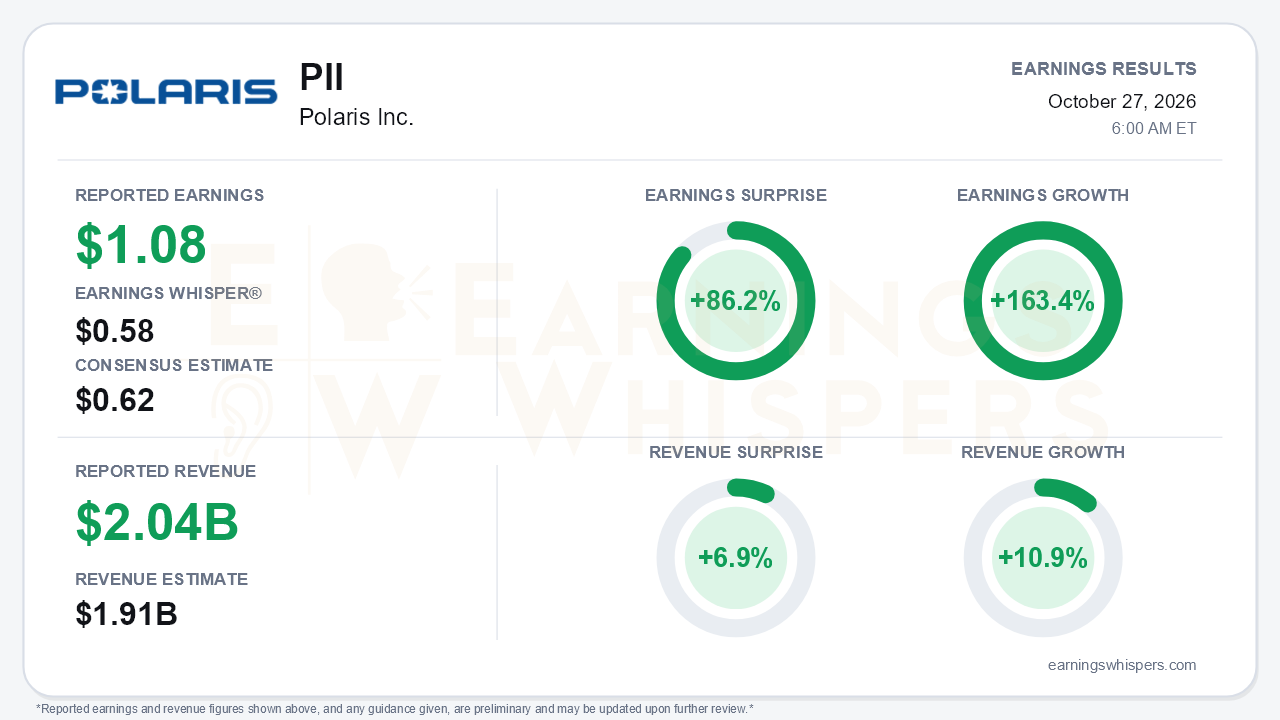
Polaris delivered one of the cleanest headline beats of the season. It reported third-quarter earnings of $1.08 per share, well above the $0.62 consensus and the $0.58 Earnings Whisper number, an 86.2% surprise. Earnings grew 163.4% from a year ago. Revenue of $2.043 billion rose 10.9% and topped the $1.91 billion consensus by 6.9%. Management also raised full-year guidance for the third consecutive quarter. Yet the call made clear that part of the quarter's strength was borrowed from the fourth quarter, and management went out of its way to warn that 2027 expectations look too high. That is the central tension: 2026 keeps getting better while the runway into next year is getting shorter.
The quality of the beat deserves scrutiny. On management's operational basis, adjusted EPS was $0.95, up from $0.41 a year ago and well above plan. That figure is below the $1.08 headline, and the gap carries into guidance. The reported adjusted EPS outlook rose to $3.50-$3.60 from $3.00-$3.10. The operational outlook moved to $2.40-$2.50 from $2.05-$2.15, a long way from the $1.50-$1.60 Polaris guided to in January. Management also noted that roughly $0.30 of EPS shifted from the fourth quarter into the third. Full-year guidance implies fourth-quarter operational EPS of only $0.32-$0.42 on roughly flat organic sales. Investors who extrapolate the third-quarter print risk overestimating the run rate.
The underlying operating story is still genuinely better. Sales rose 11%, or 17% excluding Indian. Operational EBITDA margin expanded 85 basis points, and reported EBITDA margin reached 8.8%, up 118 basis points. Several areas carried the quarter:
- Off-road vehicle share gains extended to six straight quarters.
- Parts, garments and accessories grew 12%.
- Commercial demand tied to data centers was strong.
- Government and defense business benefited from U.S., Canadian and NATO spending.
- The Huntsville lean RANGER line ramped faster than expected.
Full-year sales guidance rose to $7.55-$7.60 billion, about 11% organic, from $7.3-$7.5 billion. The industry retail outlook moved from flattish to low-single-digit growth. Balance-sheet progress was arguably the most durable improvement. Polaris generated $382 million in operating cash flow and repaid more than $320 million of debt. Net leverage fell to 2.0x from 2.6x last quarter and 3.6x in the first quarter, with a target below 2x by year-end.
Beneath the surface, however, several trends moved the wrong way:
- **Margins:** Gross margin from operations slipped 19 basis points, reversing an 82-basis-point expansion in the second quarter, as commodities, logistics and tariffs created a 190-basis-point headwind.
- **Retail:** North American off-road retail slowed to +2% from +5%, partly on a tougher comparison, and total company retail was flat.
- **Dealer inventory:** It rose 3% year over year after falling 8% last quarter, reflecting recreational channel fill. That is not alarming on its own, but it means shipments ran ahead of retail.
- **Weak spots:** Pontoon retail fell by low double digits, Europe was weak, and Ex-Im and Goupil sales dropped 12%.
- **Costs ahead:** Management expects a roughly $70 million commodity and logistics headwind in the first half of 2027 alone, driven by steel, aluminum, diesel and trucking.
- **Policy:** An open Section 301 excess-capacity investigation and USMCA uncertainty add to the risk.
Management also suggested Street 2027 models have not backed out IEEPA tariff refunds.
Forward catalysts include three new fourth-quarter products: the RZR Pro R Boost, XPEDITION with pneumatics, and Sportsman 500. China cost-of-goods exposure has fallen to 9% from 14%. A February 2027 investor day and dealer meeting will lay out a path to mid-teens EBITDA margins. Against that, management flagged an interest rate hike and weakening consumer confidence.
The market had already turned skeptical heading into the report. Shares were $55.15 the day before earnings, down 28.0% from the $76.58 open after the July report. That July session also marked the inter-earnings and 52-week high of $77.98. The stock sat 12.2% below its 200-day moving average and just 9.7% above its October 14 low of $50.26. Investor sentiment weakened notably, from 0.34 to 0.09, and remains only marginally positive. Price trend and AVWAP readings are negative, while momentum is positive. The setup is a stock priced for disappointment colliding with a quarter that beat on nearly every headline measure, but whose details give bears legitimate ammunition about 2027.
The bottom line is that Polaris executed exceptionally well in 2026. It delivered rising margins, share gains, rapid deleveraging and a third guidance raise. But the third-quarter print was flattered by a pull-forward, gross margin from operations is under commodity pressure, and management itself is tempering next year's expectations. The February investor day will matter more than this beat in determining whether the selloff overshot.
Read our earnings preview for Polaris Inc.: https://www.earningswhispers.com/article/PII/20718
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 10 hours | |
| 10 hours | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-13 | |
| Oct-06 | |
| Sep-17 | |
| Sep-15 | |
| Sep-10 | |
| Aug-18 | |
| Aug-03 | |
| Jul-30 | |
| Jul-28 |
