Piedmont Matches Consensus But Misses The Whisper As A Third Straight Guidance Raise Collides With Leasing And Occupancy Soft Spots
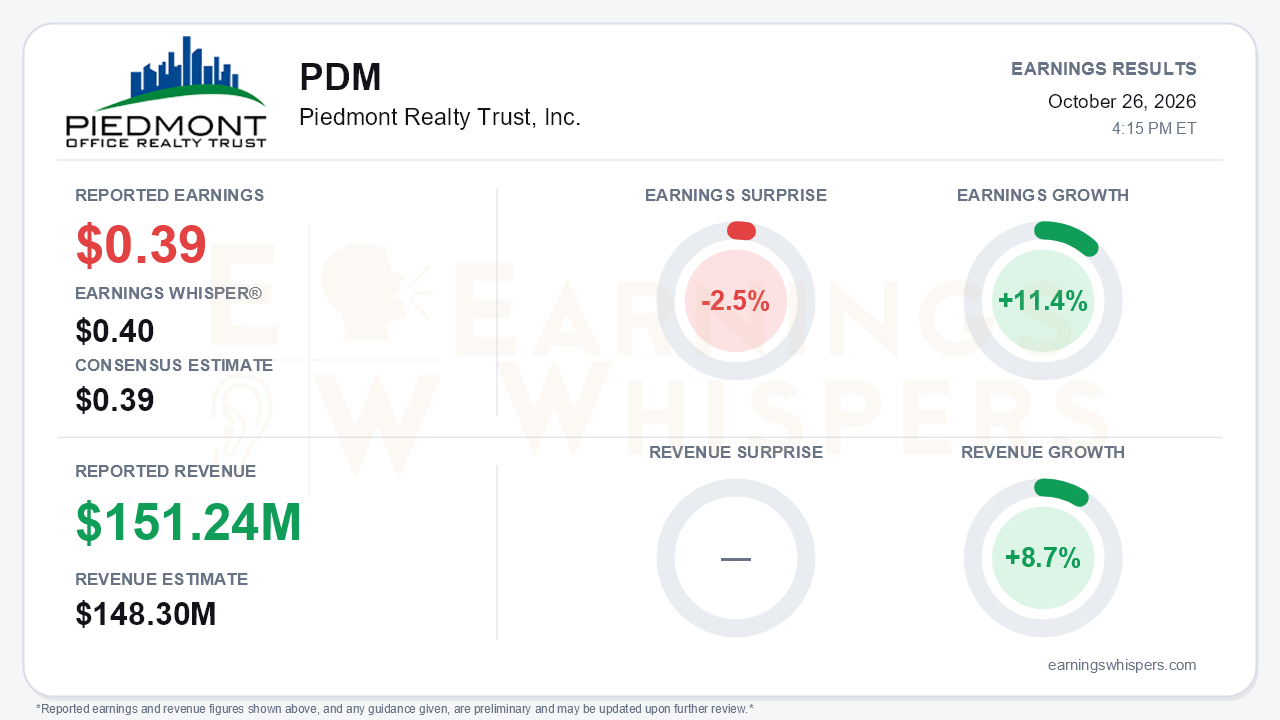
Piedmont Realty Trust reported third-quarter Core FFO of $0.39 per share on revenue of $151.24 million. The headline is less clean than the guidance story that came with it. Earnings matched the $0.39 consensus but fell short of the $0.40 Earnings Whisper number, a 2.5% miss against the higher bar investors were watching. Revenue beat the $148.3 million consensus by 2.0% and grew 8.7% year over year, while earnings grew 11.4%. Management then raised 2026 Core FFO guidance for the third consecutive quarter, to $1.55-$1.57 from $1.50-$1.55, a range that sits above estimates. That is the central tension. The underlying economics of Piedmont's Sunbelt-heavy office portfolio are improving at an accelerating pace, but the quarter offered no upside surprise on the line most investors trade, and several volume and occupancy indicators softened.
The quality of the improvement is the strongest part of the report. Quarterly Core FFO has climbed steadily from $0.35 in the fourth quarter to $0.36, $0.38 and now $0.39. Same-store cash NOI rose about 8% in the quarter. Full-year cash NOI guidance moved to 7.5%-8.5%, a range that started the year at 3%-6% and has been lifted at every update since. Pricing is doing most of the work. Net effective rent jumped to a record $29.31 per square foot, up from $25.56 in the second quarter and roughly $21 at year-end. Cash and accrual leasing spreads widened to 26% and 35%, the second-highest in company history. Management pointed to early renewals of 2028-2030 expirations at record rents with minimal concessions, including a 43% cash roll-up at Galleria Towers. It also cited reduced free rent and asking rents roughly 40% below replacement cost. Expansions outpaced contractions for a 10th straight quarter, and the call's tone was noticeably more confident than earlier in the year.
The balance sheet took a meaningful step forward. Piedmont issued $230 million of 2.875% exchangeable notes due 2031 and used the proceeds to retire its remaining 9.25% 2028 bonds. That cut the weighted average cost of debt to 4.8% from 5.5% last quarter and leaves no maturities until October 2028. Capital recycling also turned active:
- It acquired 4075 Wilson Blvd in Arlington for about $52 million, or roughly $280 per square foot, at an approximately 10% going-in yield, with about 12% targeted on lease-up.
- It sold the Royal Lane land parcel for $12 million, booking a gain of about $9 million.
- It has Enclave Place in Houston under contract for $81.75 million, with proceeds earmarked for the credit line.
- It is marketing DC and suburban Boston assets for 2027 dispositions.
Piedmont also made its first ATM issuance, selling 4.1 million shares at $9.72 while buying back 5.4 million shares at $9.20. Management treated the stock as a funding currency and as a value opportunity in the same quarter.
Bears have legitimate ammunition, however. Year-end leased-percentage guidance was cut to 87.5%-88.5% from 89.5%-90.5%. Management attributed the reduction largely to redevelopment space re-entering the portfolio, the Wilson acquisition and the Enclave sale rather than to tenant losses. Still, it is a lower occupancy number. Other indicators also moved the wrong way:
- Quarterly leasing volume slipped to about 400,000 square feet, from 460,000 in the second quarter and 679,000 in the fourth.
- The proposal pipeline eased to about 2.0 million square feet from 2.4 million.
- The signed-not-commenced backlog shrank to $29 million, or 410 basis points, from $39 million as leases commenced, which removes some embedded future growth.
- The upper end of same-store accrual NOI guidance was trimmed to 5%-6%.
- The 60 Broad lease in New York slipped again, now to the first quarter of 2027.
Management also cited U.S. Bank's downsizing in Minneapolis, lagging DC and Boston markets, Broadcom and Fiserv expirations at Central Perimeter in the third quarter of 2027, AI-related corporate layoffs and higher rates slowing acquisitions. It indicated a dividend reinstatement is not imminent in 2027.
Investors appear unconvinced. Earnings Whispers sentiment, already negative ahead of the report, deteriorated meaningfully from -0.27 to -0.44. The stock is essentially flat since the open following the July report, at $9.61 versus $9.65, despite a quarter of rising guidance. Shares do trade about 11.9% above their 200-day moving average of $8.59, so the longer-term recovery remains intact even as near-term progress has stalled. The Earnings Whispers trend readings lean constructive, with momentum and AVWAP positive while price trend is neutral. The current price also sits between Piedmont's recent buyback price and its ATM issuance price.
The bottom line is that Piedmont delivered a fundamentally stronger quarter than its in-line headline suggests. It posted record rents, widening spreads, sharply lower debt costs and a third guidance raise. A miss against the whisper, softer leasing volume, a lower occupancy target and another delay at 60 Broad gave skeptics enough to keep sentiment sour. Whether rent growth can offset the occupancy and leasing-volume softness is the question the next several quarters will need to answer.
Read our earnings preview for Piedmont Realty Trust, Inc.: https://www.earningswhispers.com/article/PDM/20663
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Sep-14 | |
| Sep-14 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-02 | |
| Jun-01 | |
| May-02 | |
| Apr-30 |
