IQVIA Tops Every Line And Raises Guidance Again As Clinical Bookings Surge, But Commercial Slowdown And Backlog Cleanup Temper The Beat
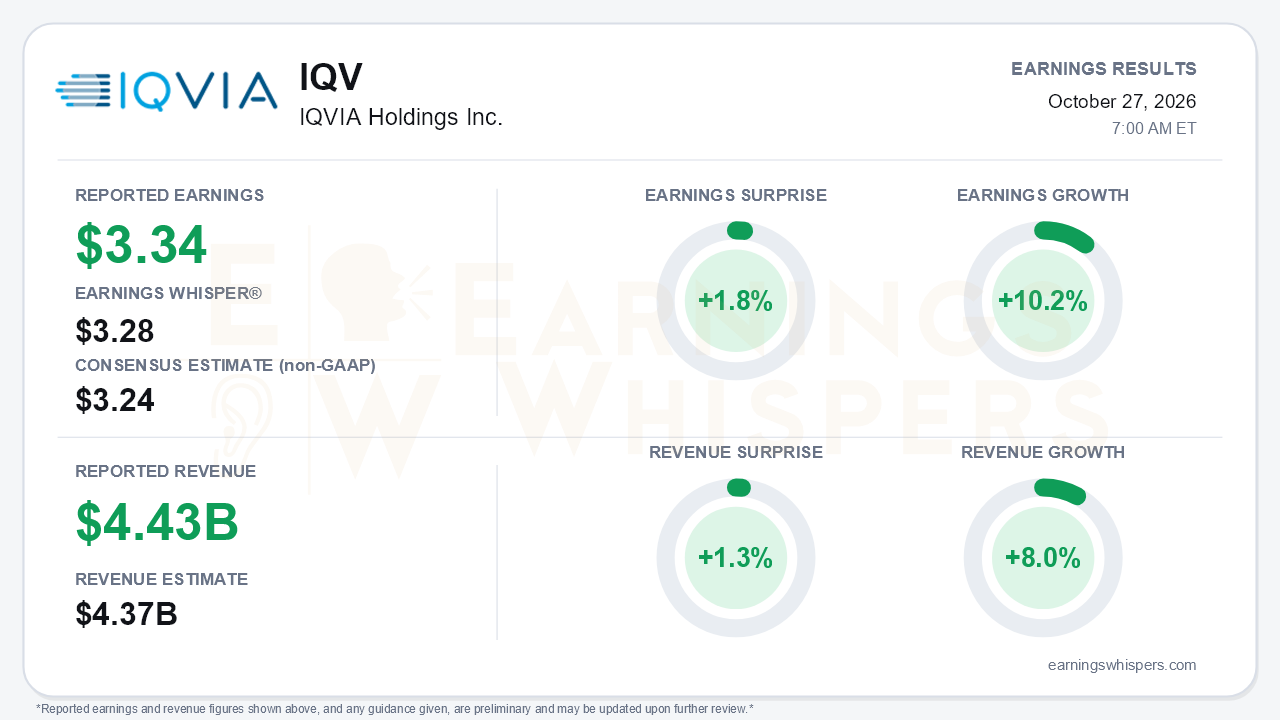
IQVIA delivered a clean but measured beat in the third quarter. Adjusted EPS of $3.34 topped the $3.24 consensus by 1.8% and cleared the $3.28 Earnings Whisper number. Revenue of $4.428 billion beat the $4.37 billion consensus by 1.3%. On Earnings Whispers' normalized basis, earnings grew 10.2% and revenue rose 8.0% year over year. The company measures adjusted EPS growth at 11.3% against its own $3.00 prior-year figure. Results landed above the top of management's own guidance on every line, and full-year targets were raised for a third straight quarter. The central story is a clinical business gaining real momentum while the rest of the picture is less uniformly strong. Commercial growth cooled, the backlog was cut, and part of the guidance raise is bought rather than built.
The quality of the beat deserves some scrutiny. Adjusted EBITDA rose 8.7% to $1.032 billion, and margin expanded 20 basis points. That compares with 10 basis points in Q2 and a 60-basis-point contraction in Q1, so operating leverage is improving. Below that line, results were thinner. GAAP operating income increased only modestly, from $553 million to $572 million, as restructuring costs nearly doubled to $36 million. GAAP EPS of $2.10 versus $1.93 was helped by $42 million of equity earnings from unconsolidated affiliates. Stock-based compensation, which is excluded from adjusted results, jumped to $83 million from $55 million. A diluted share count roughly 2.7% lower also did meaningful work at the per-share level. Free cash flow of $667 million was 120% of adjusted net income and nearly double Q2's $360 million, though it was below the $772 million posted a year ago.
The clinical side carried the quarter. R&D Solutions revenue grew 8.7%, with organic growth holding near 7% after just 3% in Q1. Net new bookings reached $3.2 billion, up 15%, for a 1.2x book-to-bill. That was the strongest clinical bookings quarter since 2022 and followed $3.15 billion in Q2. Trailing-twelve-month bookings rose for a fifth straight quarter to $11.7 billion. Next-twelve-month revenue expected from backlog climbed to $9.4 billion, up 10% versus 7.5% growth last quarter, which is perhaps the most forward-relevant figure in the report. Management pointed to emerging biopharma funding of $90 billion year to date, up 85%, along with win rates up two to three points and new drug launches up more than 40%.
Bears still have legitimate ammunition. Commercial Solutions organic growth slipped to about 4% from about 5% in the first half. Reported segment growth fell to 6.9% from 8.6% in Q2, which management attributed to European seasonality. RFP flow growth moderated to high single digits from strong double digits. The $2.1 billion removal of inactive trials cut contracted backlog to $32.6 billion from $34.2 billion. The adjustment was flagged in advance and does not affect guidance or forward revenue estimates, but it is a reminder that headline backlog had been overstated. The revenue guide of $17.35-$17.50 billion now assumes roughly 250 basis points of acquisition contribution, up from about 200. Full-year margin guidance stayed flat near 23.2%, held back by a roughly 70-basis-point drag from pass-through-heavy full-service wins. Q4 also faces difficult comparisons and a roughly 70-basis-point currency headwind.
The market setup is more complicated than the modest surprise implies. Investor sentiment swung from slightly negative (-0.03) to solidly positive (0.42) ahead of the report, a substantial shift in expectations. Shares had climbed 16.4% since the open after the July report to $273.60. That leaves the stock about 31% above its 200-day moving average and 3.3% below the 52-week high of $282.98 set on October 22. The stock entered earnings near the top of an inter-earnings range that began at an early-August low of $227.15. The Earnings Whispers trend readings are mostly positive, with price, momentum, and AVWAP constructive while sequential growth is neutral.
That positioning raises the bar. A 1.8% EPS beat and an incremental guidance raise are solid. Investors who bid the stock up into the print were likely paying for the bookings acceleration, which the report did deliver. Management's tone stayed highly confident but was not incrementally more bullish than Q2. With the December 1 investor day set to frame 2027, the near-term debate shifts toward whether clinical strength can offset softer commercial growth and slower RFP momentum.
The bottom line is that IQVIA's clinical engine is clearly strengthening, with record-level bookings and accelerating backlog conversion supporting a credible growth narrative. Commercial deceleration, the backlog reset, an M&A-assisted guidance raise, and an unchanged margin outlook keep the quarter short of an unqualified win. Expectations had already moved sharply higher before the report.
Read our earnings preview for IQVIA Holdings Inc.: https://www.earningswhispers.com/article/IQV/20705
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| 11 hours | |
| 11 hours | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Sep-29 | |
| Sep-24 | |
| Sep-09 | |
| Sep-09 | |
| Sep-03 | |
| Sep-02 | |
| Aug-27 |
