Hilton Beats On Accelerating RevPAR, But Muted Flow-Through And A Softer Q4 Guide Temper The Raise
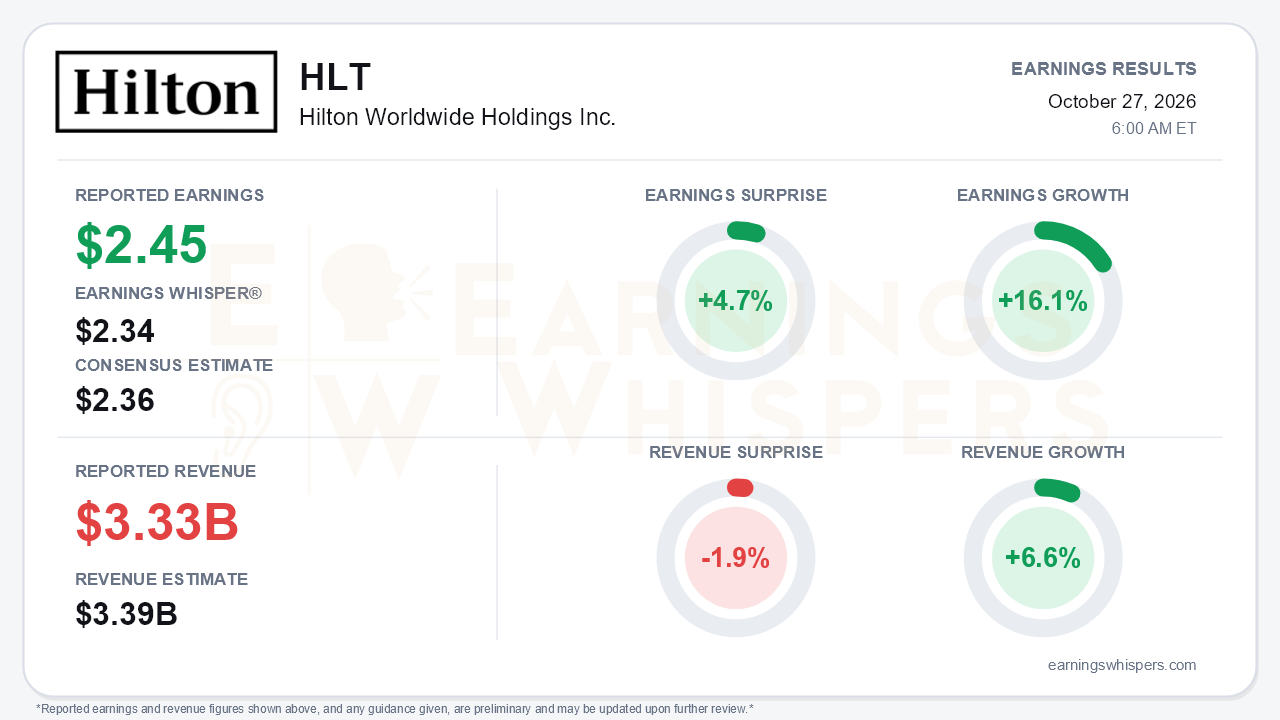
Hilton delivered the kind of top-line acceleration that hotel bulls have been waiting for, but the conversion of that demand into profit was less impressive than the headline suggests. Adjusted EPS of $2.45 beat the $2.36 consensus by 4.7% and cleared the $2.34 Earnings Whisper number, with earnings up 16.1% year over year. Revenue of $3.325 billion rose 6.6% but missed the $3.39 billion consensus by 1.9%. The forward outlook also landed below Street estimates. System-wide comparable RevPAR jumped 5.8%, the strongest quarter of the year, and management raised full-year RevPAR guidance for the third straight quarter. That is the central tension: demand is clearly accelerating, but EBITDA guidance barely moved.
The quality of the beat deserves scrutiny. The core fee engine was excellent. Franchise and licensing fees climbed to $815 million from $739 million, total management and franchise fees grew 9.5% versus 6.4% in the second quarter, and Adjusted EBITDA margin expanded to 77.0% from 75.2%. However, adjusted net income rose to $556 million from $498 million, a slower pace than per-share earnings. A diluted share count of 226 million, down from 237 million, did meaningful work for EPS. Buybacks are being funded partly with leverage. Net debt rose to $12.6 billion from $11.5 billion at year-end, and interest expense climbed to $184 million from $159 million. Ownership revenue also slipped to $304 million from $322 million. On a GAAP basis, diluted EPS rose to $2.37 from $1.78, helped by much smaller special items than a year ago.
The call made a credible case that the demand recovery is broadening rather than fading. Quarterly RevPAR has progressed from +0.5% in the fourth quarter of 2025 to +3.6%, +3.9% and now +5.8%. Business transient swung from a 2.1% decline to an 8.3% gain over that span, and group RevPAR accelerated to +8.2% from +3.7%. U.S. RevPAR rose 7.0%, and Europe gained 6.5%. Full-year RevPAR guidance now stands at 4.0%-4.5%, versus 1%-2% in February. Management lifted its view of the underlying run rate to roughly 3.5% globally and about 4% in the U.S., up from 2%-2.5% last quarter. It also offered an initial 2027 RevPAR framework of 3%-4%, supported by U.S. group pace running up mid-single digits.
The weak spots are concentrated but real. The one-point RevPAR raise lifted the full-year Adjusted EBITDA midpoint by only about $10 million, to $4.07 billion, against roughly $30 million implied. Middle East weakness and underperforming Hilton Grand Vacations license fees each absorbed about $10 million. Middle East & Africa RevPAR fell 5.6% in the quarter, and that region's full-year outlook has deteriorated from mid-single-digit growth to a low-double-digit decline. China RevPAR dropped 5.4%, ownership renovations are a $20 million-plus drag this year, and fourth-quarter RevPAR guidance of 3.0%-3.5% marks a clear step down. Management attributed part of the third-quarter strength to the World Cup and favorable calendar shifts. It expects the fourth quarter to be affected by midterm elections and a greater Middle East impact.
Development remains the most durable part of the story. Hilton posted record organic openings of roughly 27,000 rooms, and its pipeline reached a record 543,100 rooms, nearly half of them under construction. Construction starts rose more than 40%, and more than 80% of 2027 net unit growth is already under construction. Management guided 2026 net unit growth to the midpoint of its 6%-7% range. A Scandic deal opens the Nordics, while the Rise 2 owner cost program and a new lifestyle brand are slated for early 2027.
The market setup is more complicated than the surprise implies. Shares entered the report at $351.89, up 9.8% since the opening after the July report and about 10% above the 200-day moving average. They sat just 3.5% below a 52-week high of $364.50 set on October 21. Investor sentiment improved modestly, rising to 0.48 from 0.44. With the stock near its highs and expectations firmer, a below-consensus outlook and muted flow-through give bears legitimate ammunition. Most Earnings Whispers trend readings remain positive, although the sequential-growth signal has turned negative.
The bottom line is that Hilton's quarter strengthened the demand narrative, with accelerating RevPAR, rising fee growth and a record pipeline, while exposing friction in converting that strength into earnings. Buybacks, the Middle East, timeshare fees and a decelerating fourth quarter now matter more to the earnings path than the headline beat. That leaves a stock priced near its highs with less room for imperfect execution.
Read our earnings preview for Hilton Worldwide Holdings Inc.: https://www.earningswhispers.com/article/HLT/20699
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 41 min | |
| 1 hour | |
| 5 hours | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 |
