Hartford Beats On Investment Income And Lower Costs, But Middle-Market Underwriting And Benefits Margins Keep Slipping
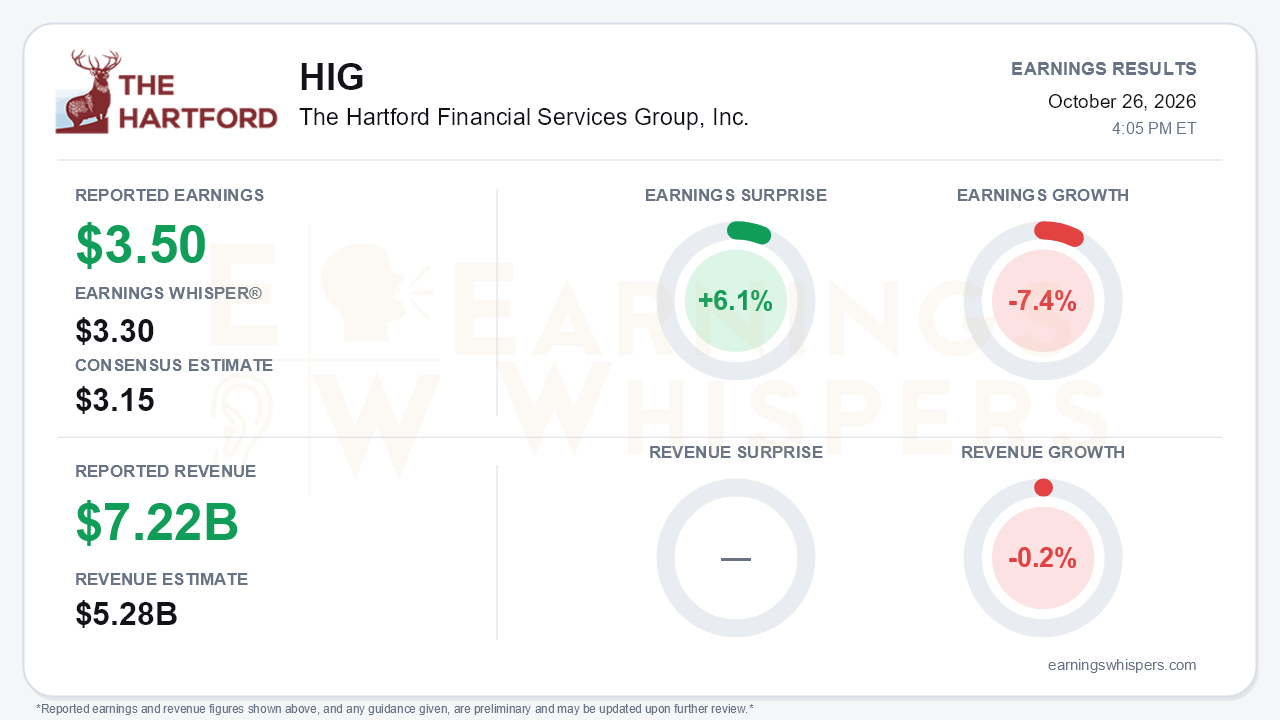
The Hartford reported third-quarter core earnings of $3.50 per share, ahead of the $3.15 consensus and the $3.30 Earnings Whisper number, a 6.1% surprise. Revenue of $7.22 billion beat the $5.28 billion consensus by 36.7%. The beat is real, but it does not reverse the trend: earnings fell 7.4% year over year, and revenue slipped 0.2% on Earnings Whispers' normalized basis. Core EPS has risen sequentially, from $3.09 in the first quarter to $3.42 in the second and $3.50 now. Underneath that progression, the underwriting engine that justified Hartford's premium returns is weakening in specific places. That is the central tension: investment income, expense cuts and capital return are carrying a quarter in which core commercial and benefits margins moved the wrong way.
The quality of the beat deserves scrutiny.
- **Investment income:** Net investment income rose 13% to $850 million. Much of that came from limited partnership income of $156 million versus $91 million a year ago, an annualized LP yield of 10.2%. Excluding LPs, investment income grew a steadier 5% and the yield was flat at 4.6%. Alternative returns of that size are not a dependable run rate.
- **GAAP net income:** Net income available to common jumped 23% to $4.82 per share, but that figure is flattered by a $497 million pre-tax gain from commuting the asbestos and environmental adverse development cover. Hartford properly excludes that gain from core earnings.
- **Catastrophes and reserves:** Catastrophe losses rose to $198 million from $70 million. Core favorable reserve development was flat at $97 million, so reserve releases did not prop up the quarter.
The call showed where the business is changing.
- **Middle & Large Business:** The underlying combined ratio deteriorated to 99.5, from 95.3 in the second quarter and 91.4 a year ago. That undercuts management's earlier hope for second-half improvement in the line.
- **Workers' compensation:** Management raised loss picks after a broad-based uptick in claim frequency, which it linked to healthcare costs and the expiration of ACA subsidies. The change cost Business Insurance roughly a point in the quarter. That is a notable shift from earlier commentary that the book was behaving well.
- **Business Insurance overall:** The segment's underlying combined ratio drifted to 90.1 from 89.3 in the second quarter and 89.2 in the first.
- **Small Business:** This remains the standout, with an underlying combined ratio of 85.2 and straight-through processing at a record 78%. However, new business turned non-positive for the first time in more than 20 quarters as competition intensified.
- **Employee Benefits:** Group disability's loss ratio rose 5.7 points to 76.3, and the core margin fell to 6.4% from 7.4% in the second quarter and 8.3% a year ago.
There are offsets.
- Business Insurance written premiums grew 6%, with Global Specialty accelerating to 7%.
- The segment's expense ratio improved 1.1 points to 30.0, tracking toward a sub-30 target.
- Personal Insurance's underlying combined ratio improved 2.9 points to 87.1, as earned pricing outpaced loss trends.
Growth in personal lines is the cost of that discipline. Segment written premiums fell 4%, and personal auto fell 9% in a fiercely competitive market. Trailing core ROE has slid to 17.9% from 20.3% in the first quarter, although it remains above the year-ago level.
The catalyst list is busy:
- The quarterly dividend rises 12% to $0.67.
- Buybacks stepped up to $475 million in the quarter.
- The Equitable employee benefits acquisition closed, adding roughly $500 million of annual premium. Management said it will be modestly dilutive to benefits core earnings in 2027, with about $30 million of annual amortization and $30 to $40 million of integration costs.
- The Hartford Funds sale to Wellington could close as early as December 1.
- The commutation brought in $1.12 billion of cash.
- Mo Tooker succeeds Chris Swift as CEO on March 1, with strategy described as unchanged.
These items support book value and capital return. Book value per share excluding AOCI is up 12% year to date to $82.47. None of them fixes workers' comp frequency or disability incidence.
Investor sentiment remains negative but improved modestly, moving from -0.095 to -0.060. Expectations were cautious going in, which helps explain why a clean headline beat did not meet a skeptical crowd. The stock has gone nowhere: shares are down 0.7% since the open after the July report and sit just 0.4% above the 200-day moving average of $135.44. Earnings Whispers trend signals are mixed, with price trend negative while AVWAP remains positive. The market has been unwilling to pay up for capital return while underwriting margins erode.
The bottom line is that Hartford delivered a quarter that looks better on the scoreboard than in the underwriting ledger. The beat leaned on alternative investment income, expense discipline and buybacks. Bears have legitimate ammunition in Middle & Large loss trends, rising workers' comp frequency, slipping benefits margins and fading small-business new business. Unless underlying commercial margins stabilize, capital return alone is unlikely to change how investors value the stock.
Read our earnings preview for The Hartford Financial Services Group, Inc.: https://www.earningswhispers.com/article/HIG/20656
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Sep-30 | |
| Sep-16 | |
| Aug-25 | |
| Aug-19 | |
| Aug-11 | |
| Aug-04 | |
| Jul-24 | |
| Jul-23 | |
| Jul-22 | |
| Jul-15 | |
| Jul-15 |
