Norwood Financial Posts Record Quarter And Beats Estimates, But One-Time Credit Recovery And A Plateauing Margin Temper The Beat
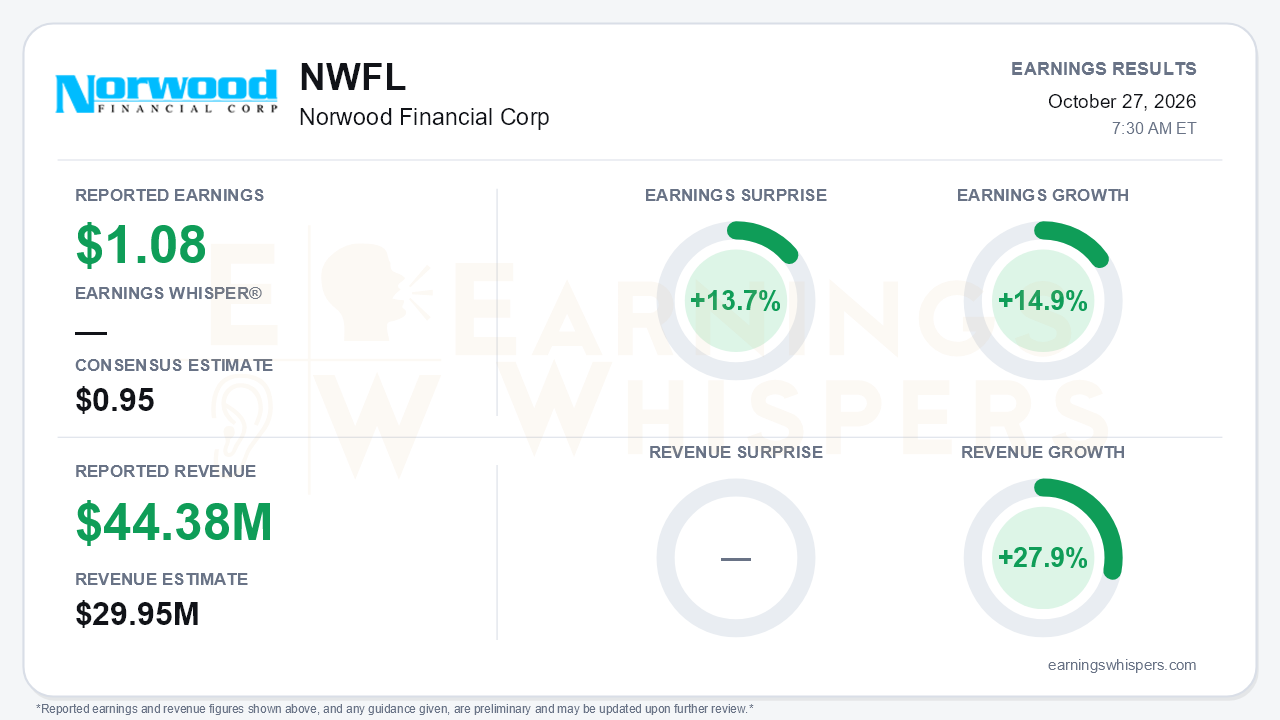
Norwood Financial Corp delivered its second straight record quarter, earning $1.08 per share and beating the $0.95 consensus by 13.7%. Earnings grew 14.9% year over year. Revenue of $44.38 million topped the $29.95 million consensus by 48.2% and grew 27.9%. Sequentially, the trajectory is steep. GAAP EPS has climbed from $0.35 in the first quarter, which was weighed down by roughly $4.9 million of Presence Bank merger costs, to $0.86 in the second quarter and $1.08 now. With merger expenses at zero, this was the first fully clean post-acquisition quarter. Return on average assets reached 1.60% and return on tangible equity 18.51%. The central tension is that the quarter's best numbers were flattered by a favorable credit resolution, while management simultaneously signaled that margin expansion, the engine of the past three quarters, is close to running its course.
The quality of the beat deserves scrutiny. Net interest income rose to $28.0 million from $26.8 million in the second quarter and $20.5 million a year earlier. Net interest margin expanded 11 basis points sequentially to 4.01%. However, the call attributed roughly $400 thousand of interest income to one-time items: past-due interest and debtor-in-possession fees collected when the bankrupt borrower's business was sold. The same event pulled the loan off non-accrual, helping cut the provision to $0.1 million from $1.9 million in the second quarter. That provision swing alone accounts for a large share of the sequential improvement in pre-tax income. Pre-provision net revenue of $15.4 million, up from $13.6 million, is the cleaner read. It still shows genuine progress, as does an efficiency ratio of 50.28% versus 56.33% a year ago.
Beneath the one-timers, the call preserved a credible core story. Management said the underlying margin trend remains positive. Certificate-of-deposit costs are drifting lower, with time-deposit rates at 3.41% versus 3.46% last quarter and 3.72% a year ago, and new loans are pricing above the portfolio, which yielded 6.43%. Fee income is also gaining traction. Brokerage revenue rose 41% after the move to the Cetera platform, and service charges climbed to $2.0 million from $1.7 million. Management described fee income as sustainable and expandable. The tone was notably more confident, and the loan pipeline was called strong. Leadership additions in commercial lending and a broadening AI roadmap round out the operational narrative.
Bears have legitimate ammunition, however. Management walked back its first-quarter expectation of 3 to 5 basis points of quarterly NIM expansion and now says not to expect much further widening in a rising-rate environment. Organic growth is thin. Loans grew only to $2.29 billion from $2.26 billion because paydowns again offset production, deposits were flat at $2.51 billion, and borrowings rose to $118.9 million from $65.5 million. The 20.9% year-over-year loan growth is largely acquisition-driven. Tangible book value per share slipped to $22.35 from $22.96 as rising rates widened the AOCI loss to $40.0 million. Credit improved sequentially, with nonperforming loans falling to 0.73% of loans from 1.21%, but that is still double the 0.36% of a year ago. About $7.1 million of the troubled relationship remains, with a slower real estate workout ahead. Competition on larger loans and a lack of urgency among M&A sellers limit other growth avenues. One discrepancy is worth noting: the call referenced total assets surpassing $3 billion, while the period-end balance sheet shows $2.95 billion.
The market setup is more complicated than the surprise implies. Shares closed at $34.88 ahead of the report, up 14.8% from the open after the July release. That left the stock 10.9% above its 200-day moving average and just 1.7% below the $35.48 52-week high set in early September, near the top of its inter-earnings range. Investor sentiment moved the other way, falling from a mildly positive 0.19 to a mildly negative -0.12. That is a meaningful cooling of expectations even as the price advanced. Earnings Whispers trend signals are mostly positive, with sequential growth, momentum and AVWAP readings constructive while the price trend is neutral.
The bottom line is that Norwood produced a genuinely strong, clean quarter with improving profitability, and it largely de-risked the second-quarter credit scare. But the headline overstates the run rate. A portion of the margin gain and most of the provision relief were one-time in nature, and management is now guiding toward a margin plateau with only modest organic loan growth. With the stock trading near its highs, the next leg likely depends on fee income and loan production rather than further margin expansion.
Read our earnings preview for Norwood Financial Corp: https://www.earningswhispers.com/article/NWFL/20716
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 10 hours | |
| Sep-24 | |
| Sep-16 | |
| Aug-28 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jun-30 | |
| Jun-18 | |
| Apr-28 | |
| Apr-27 | |
| Apr-24 | |
| Apr-08 | |
| Mar-17 |
