Nucor Matches The Whisper As Steel Pricing Drives A Three-Year Earnings High, But A Flat Q4 Guide Signals The Climb Is Leveling Off
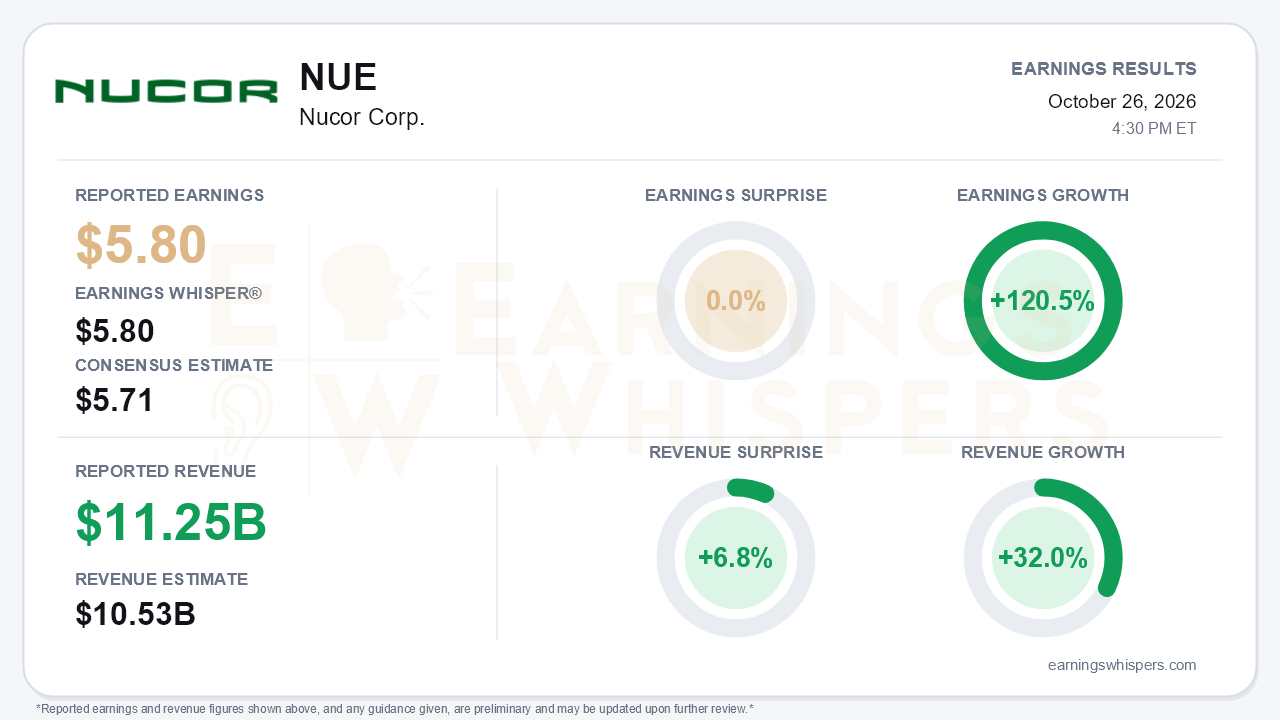
Nucor (NYSE: NUE) earned $5.80 per share in the third quarter, matching the $5.80 Earnings Whisper and topping the $5.71 consensus. Revenue of $11.249 billion beat estimates by 6.8%. Earnings grew 120.5% year over year and revenue rose 32.0%, more than doubling the $2.63 earned a year ago. By most measures this was Nucor's best quarter in more than three years. EBITDA reached $2.28 billion, and management said consolidated EBITDA margin topped 20%. The central tension is that a large revenue beat produced only an in-line EPS result, and the fourth-quarter outlook implies the steep sequential climb is flattening. EPS rose from $1.73 in the fourth quarter of 2025 to $3.23, then $4.84 adjusted, and now $5.80. The guide calls for Q4 earnings only "generally in-line with or modestly higher" than Q3.
The quality of the quarter is better than the in-line label suggests. Q3 was a clean GAAP print. Second-quarter GAAP EPS of $5.04 included a $0.20 non-cash Helion valuation gain, so the true sequential comparison is $5.80 against $4.84. Q3 also absorbed $124 million of pre-operating and start-up costs ($0.42 per share) and $17 million of impairments. Q3 had to overcome two items as well: the $130 million raw-material refund that flattered Q2 steel mill costs did not recur. Even so, steel mills pre-tax earnings rose to $1.79 billion from $1.56 billion. External steel mill pricing climbed 8% sequentially to $1,233 per ton while scrap costs held flat at $421, a meaningful widening of metal spreads.
The revenue beat largely failed to reach the bottom line because of costs. Management acknowledged that conversion costs for freight, energy, consumables and overtime crept higher as mills ran hard, leaving steel mill margins slightly lighter than pricing alone would imply. A further modest uptick is expected in Q4. Raw materials earnings fell to $105 million from $146 million on weaker pricing and a 23% drop in external tons. Steel products was the standout: pre-tax earnings jumped to $465 million from $353 million, and segment EBITDA margin widened roughly 200 basis points as downstream pricing caught up with input costs. Steel mill shipments set a record for a third straight quarter at 7.23 million tons. Management reaffirmed 2026 shipment growth at the high end of 5-10%.
The call added more to the long-term story than the quarter did. Nucor won an entire General Motors platform for exposed automotive sheet, which management described as the first such award for an electric-arc-furnace producer, with work shifting to the new West Virginia mill. That mill poured its first heat in September and shipped its first pickle-line coils in October, with the hot mill, cold mill and galvanizing lines targeted by December. Berkeley's automotive-grade galvanizing line is now producing. Nucor also raised its long-term towers and structures EBITDA target to about $200 million from $150 million, backed by a $165 million capacity expansion. CEO Leon Topalian called this the strongest demand environment of his 31-year career and said he expects 2027 earnings to exceed 2026.
Bears still have legitimate ammunition. Imports have been rising in recent months, including a surge from South Korea despite Section 232 tariffs, though volumes remain down 13% year over year. West Virginia start-up costs are expected to be as high or higher in 2027. Q4 brings roughly a 7% seasonal shipment decline and heavier outage schedules. The offset is cash generation. Free cash flow hit $1.6 billion in Q3, up from $829 million in Q2, and reached $2.66 billion year to date. 2026 capex is tracking at or below $2.5 billion and is expected to fall further in 2027, which supports continued buybacks. Nucor repurchased 2.03 million shares at an average of $247.04.
Investors have not been chasing the story. Earnings Whispers sentiment remained positive but weakened considerably, falling to 0.19 from 0.40 at the prior report. The stock has also gone nowhere: at $257.35, shares are up just 1.3% from the $254 open after the July report, even as quarterly EPS rose about 20% on an adjusted basis. The longer trend is intact, with the stock sitting about 16% above its 200-day moving average, and momentum and AVWAP readings remain positive. Still, the market appears to have priced much of this pricing cycle before the quarter arrived.
The bottom line is that Nucor delivered a high-quality, cash-rich quarter and a stronger multiyear narrative, led by the GM award, West Virginia ramp and higher downstream targets. Yet it printed only to the whisper and guided Q4 to a plateau. With costs creeping up, imports building and sentiment cooling, the near-term debate has shifted from how fast earnings are rising to how long peak-level spreads can hold. Management's confidence in a stronger 2027 is the claim investors will need to see validated.
Read our earnings preview for Nucor Corp.: https://www.earningswhispers.com/article/NUE/20661
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
Nucor Earnings Due As Steel Prices Hit 4-Year High; NUE Near Buy Point
NUE
Investor's Business Daily
|
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 |
