TransUnion Tops Consensus But Misses The Whisper As Its EPS Raise Leans On Buybacks While Organic Growth And Margin Targets Soften
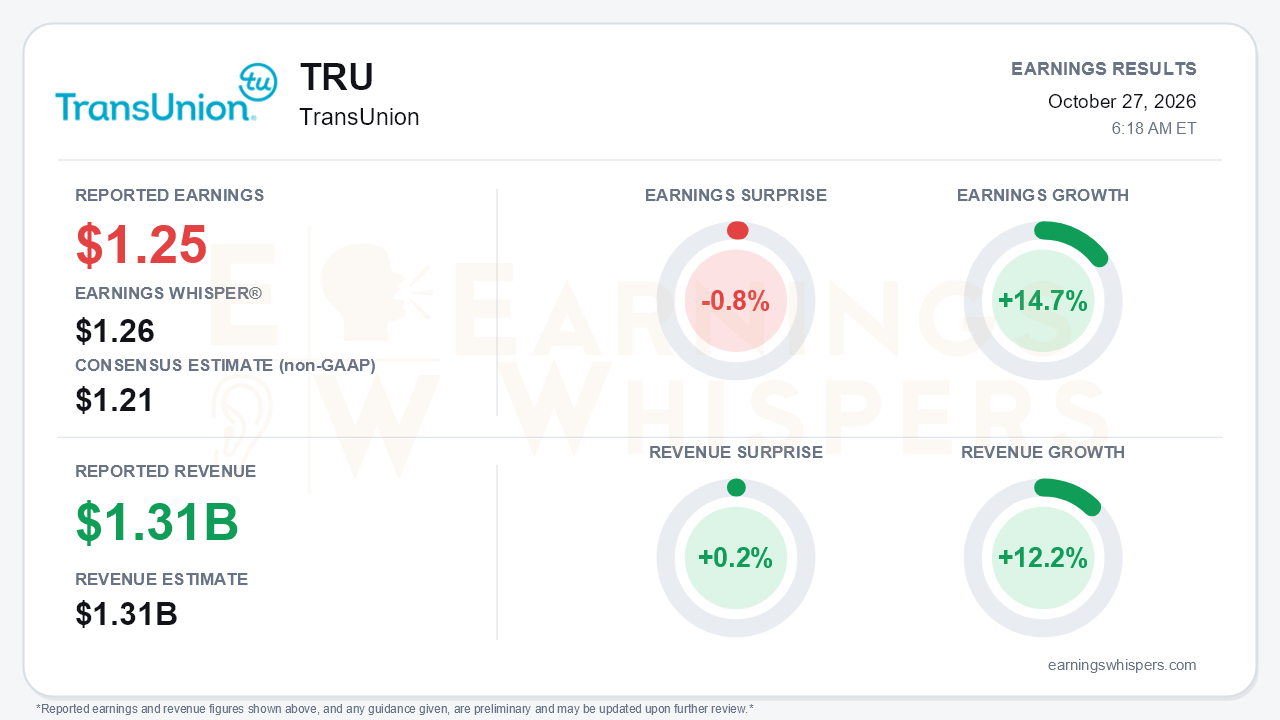
TransUnion (NYSE: TRU) earned $1.25 per share in the third quarter on revenue of $1.313 billion. That cleared the $1.21 consensus but fell short of the $1.26 Earnings Whisper number, a 0.8% miss against the expectation that mattered. Revenue edged past the $1.31 billion consensus by 0.2%. Earnings grew 14.7% year over year and revenue rose 12.2%, and management lifted its full-year adjusted EPS outlook. Beneath that, the business is decelerating. The EPS raise relies on capital-structure mechanics, while organic growth in the core U.S. credit franchise is slowing and the underlying margin expansion target was largely abandoned. That is the central tension.
The quality of the beat deserves scrutiny. Reported revenue growth of 12% included roughly 5 points from acquisitions, led by Trans Union de Mexico, leaving 8% organic constant-currency growth. That figure is below the 9.5% organic pace for the first nine months. Adjusted EBITDA rose 9%, but only 5% organically, and adjusted EBITDA margin contracted to 35.4% from 36.3%. The weakness was concentrated at home. U.S. Markets adjusted EBITDA grew just 1% on 7% revenue growth, as segment margin fell to 36.2% from 38.4%. Per-share earnings outran operating profit for three reasons:
- the diluted share count fell to 192.6 million from 197.2 million;
- the adjusted tax rate dropped to 25.7% from 27.1%;
- GAAP EPS jumped to $0.81 from $0.49, flattered by a lower effective tax rate and the absence of last year's $22 million technology-transformation and $11.5 million restructuring charges.
The call laid out where momentum is fading. Non-mortgage U.S. Financial Services growth slowed to 5% from 8% in the second quarter. Card and banking cooled to 3% from 6%, and consumer lending to 5% from 8%. Mortgage excluding FICO royalty pass-through decelerated sharply to 5% from 15% as inquiries fell 16%. With the 10-year Treasury near 5%, management now assumes mortgage inquiries fall about 10% for the year and more than 20% in the fourth quarter. Tenant/employment and media also softened, and Consumer Interactive declined 3%. Fourth-quarter guidance calls for revenue of $1.264 billion to $1.294 billion, and the guidance note flags that the outlook sits below estimates. That implies only 3% to 6% organic growth versus 8% in the third quarter. Full-year revenue and EBITDA guidance moved up only at the low end. Expected underlying margin expansion was cut to flat-to-20 basis points from 50-70 basis points, reflecting technology reinvestment and higher FCRA litigation costs.
The call still preserved a credible growth story outside U.S. credit. International organic growth accelerated to 10% from 6% in the second quarter and flat in the first. India re-accelerated to 18% and Latin America grew 18% organically. Insurance delivered a ninth straight double-digit quarter, with roughly $60 million of signed wins still to ramp. VantageScore now appears in about 35% of mortgage pulls, up from roughly 30% last quarter and under 5% at the start of the year. Capital return stepped up meaningfully:
- the buyback authorization was raised by $1 billion to $2 billion;
- 2026 repurchases are targeted at about $500 million, versus $243 million so far;
- the dividend rises to 13.5 cents;
- leverage stands at 2.5x.
Bears have legitimate ammunition for 2027, however. Swap replacement adds roughly $60 million of net interest expense, about a 5-point EPS headwind. Management disclosed about $33 million of revenue, or $0.15 per share, exposed to a potential FHFA bi-merge shift. FICO's pricing initiatives could slow Vantage adoption, and the CFO is departing.
The market setup is more complicated than the consensus beat implies. Earnings Whispers investor sentiment turned modestly negative, slipping to -0.06 from +0.02, a mild cooling rather than a capitulation. Price action was far more volatile. Shares peaked at $86.49 on the morning after the July report, then slid to a 52-week low of $60.96 on October 1. They rallied about 31% from that low to $79.62 heading into this release. That leaves the stock 3.5% above its post-July opening price, 7.1% above its 200-day moving average and roughly 8% below the inter-earnings high. Much of the rebound came just before a print that delivered a whisper miss and a softer fourth-quarter organic outlook.
The bottom line is that TransUnion delivered a respectable quarter wrapped in a cautious forward picture. The adjusted EPS raise is real, but it rests mainly on buybacks, lower interest expense and tax. Organic growth is set to roughly halve in the fourth quarter, and U.S. margins are compressing. International, insurance and VantageScore traction offer genuine offsets, but investors now have to weigh them against rate-driven mortgage weakness and a heavier 2027 interest burden.
Read our earnings preview for TransUnion: https://www.earningswhispers.com/article/TRU/20731
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 11 hours | |
| 11 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 |
