Nautilus Beats On A Narrower-Than-Expected Loss, But Rising Spending And A Looming Raise Shadow Strong Proteoform Data
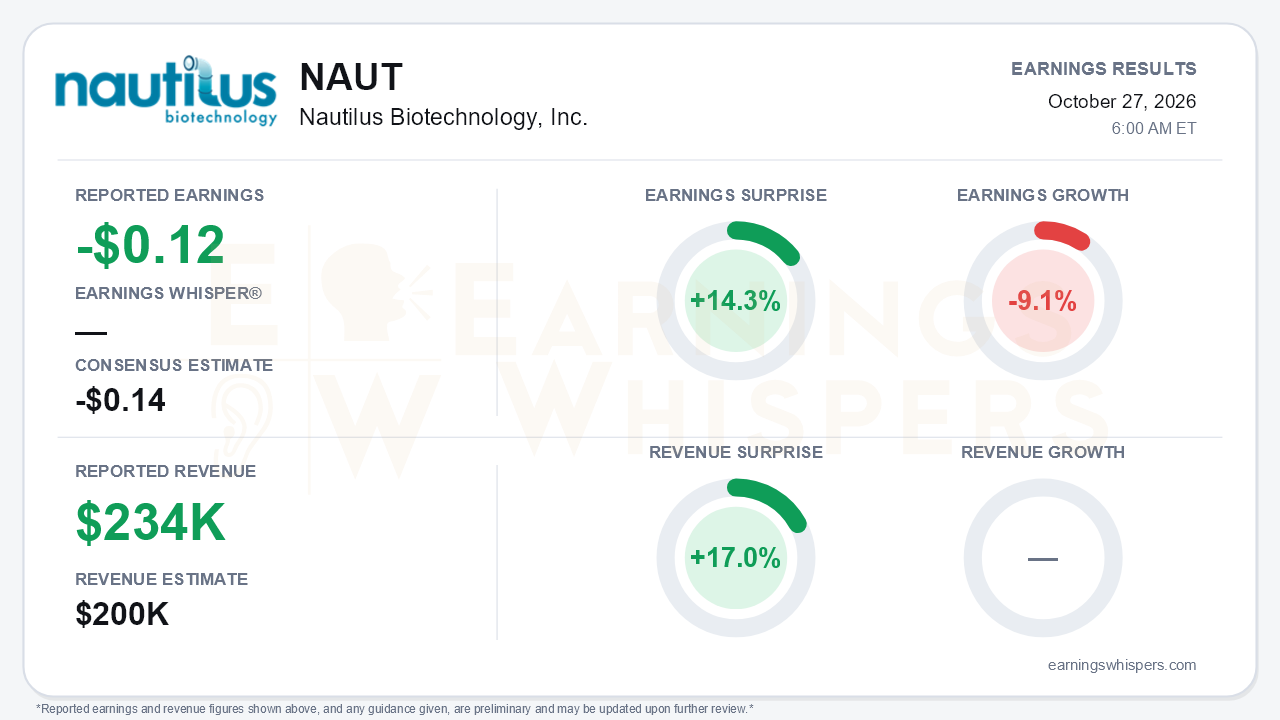
Nautilus Biotechnology reported a third-quarter loss of $0.12 per share, beating the consensus estimate of a $0.14 loss by 14.3%. Revenue of $0.23 million topped the $0.2 million consensus by 17.0%. The beat is real but should be read in context. The loss still widened from $0.11 a year ago, which works out to a 9.1% year-over-year earnings decline. Revenue is small enough that a few thousand dollars of grant timing can produce a double-digit surprise. The more meaningful story is a company pairing its best scientific validation to date with a cost base that has started growing again. That is the central tension: the platform narrative is strengthening while the financial clock keeps running.
The quality of the quarter deserves scrutiny.
- **Spending:** Operating expenses rose 10% year over year to $16.9 million. That reverses Q2's 7% decline and Q1's 14% decline. SG&A climbed roughly 15%, and R&D rose about 6%.
- **Net loss:** It widened to $15.6 million from $13.6 million.
- **Interest income:** Part of that $2 million deterioration came from interest income falling to $1.2 million from $1.9 million. That is a direct consequence of a shrinking cash pile.
- **Revenue mix:** Revenue consisted of $208,000 in grant revenue tied to the Michael J. Fox Foundation award and just $26,000 in service revenue from the Iterative Mapping Early Access Program. Neither is yet evidence of a commercial engine.
- **Cash:** Cash and investments ended at $114.3 million. That compares with $129.2 million in Q2 and $156.1 million at the end of 2025, and Q3 burn ticked up to $14.9 million from $14.2 million.
The call nonetheless preserved a credible, and arguably improving, growth story. Management said full-year 2026 revenue should now exceed the roughly $0.5 million outlook it reaffirmed in Q1 and Q2. It also guided Q4 revenue to grow sequentially from Q3 even before any SEEDS contribution, pointing to early-access activity.
The scientific progress was the quarter's highlight. Tau proteoform work was published in Nature Methods. First oncology assay data showed median coefficients of variation of 8.8% for AKT1, 3.6% for EGFR and 6.6% for P53. Those figures compare with a 10% target, an industry norm near 25% and tau's 5.5%. Crucially, the oncology assays reached that level after about a year of development, versus roughly five years for tau. Repeatability is the entire premise of the plan to deliver 20 assays by mid-2028, so this is the data point that matters most.
CEO Sujal Patel said he has "never been more confident." Management framed 2027 as the foundation year and 2028 as the scaling year.
The forward catalysts are tangible:
- **ARPA-H funding:** Selection to the ARPA-H-funded SEEDS consortium brings up to $6 million over four years. The work covers tau and EWS-FLI1 in Ewing's sarcoma, the company's first pediatric cancer program.
- **Product roadmap:** AKT1 early access is slated for late 2026, with pre-orders in early 2027. Mid-2027 shipments are planned with tau, AKT1 and a second oncology kit.
- **Market framing:** Management also pitched proteoform data as AI training material and highlighted pharma custom-assay opportunities.
Bears have legitimate ammunition, however:
- **Timeline slippage:** Commercialization has slipped versus the plan laid out after Q4 2025. Pre-orders moved from late 2026 to early 2027, and shipments from early to mid-2027. Broad-scale proteome analysis was deprioritized in Q2 with no new timeline.
- **Thin commercial footprint:** The sales team is three people.
- **Funding environment:** Management flagged uncertainty around NIH and S10 instrument grants, which could affect 2028 placements.
- **Runway:** It remains "into Q1 2028," and management continues to signal a capital raise before mid-2027 to fund the assay portfolio and commercial build-out. That now carries an explicit growth rationale, but it still implies dilution.
- **Opex guidance:** The full-year operating expense growth outlook has been trimmed from 15-20% at the start of the year to single digits. That helps, but it does not change the financing math.
The market setup is more complicated than the surprise implies. Shares entering the report at $2.44 were up 52.5% from the $1.60 open after the July report. That gain masks a violent round trip. The stock hit a 52-week low of $0.84 on August 7, then rallied to $3.26 on October 23. It entered earnings 25.2% below that peak but still 16.3% above its $2.10 200-day moving average. A move of that size means the oncology data and SEEDS news are at least partly priced in. Investor sentiment stood at a modestly positive 0.267, which is constructive but hardly euphoric. The Earnings Whispers trend readings lean positive on price and AVWAP, while sequential growth remains negative, consistent with a stock driven by scientific milestones rather than financial improvement.
The bottom line is that Nautilus delivered a clean beat and its most convincing evidence yet that Voyager's assay performance is repeatable and faster to replicate. It also nudged revenue expectations higher and added non-dilutive grant funding. Against that, spending has turned back up, losses are widening, the commercial timeline has drifted later than the plan from a year ago, and an equity raise appears likely before the first instruments ship. With the stock already well off its lows, the next leg depends on hitting the 2027 milestones and financing on acceptable terms.
Read our earnings preview for Nautilus Biotechnology, Inc.: https://www.earningswhispers.com/article/NAUT/20714
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 12 hours | |
| 12 hours | |
| Oct-15 | |
| Sep-04 | |
| Jul-28 | |
| Jul-28 | |
| Jul-08 | |
| Apr-29 | |
| Apr-28 | |
| Apr-09 | |
| Mar-24 | |
| Mar-18 | |
| Mar-02 | |
| Feb-26 |
