Esquire's First Post-Signature Quarter Beats Handily, Lifts Margin Outlook And Sets A ~$9 2027 EPS Target, But Skeptical Sentiment Shows The Integration Still Has To Prove Itself
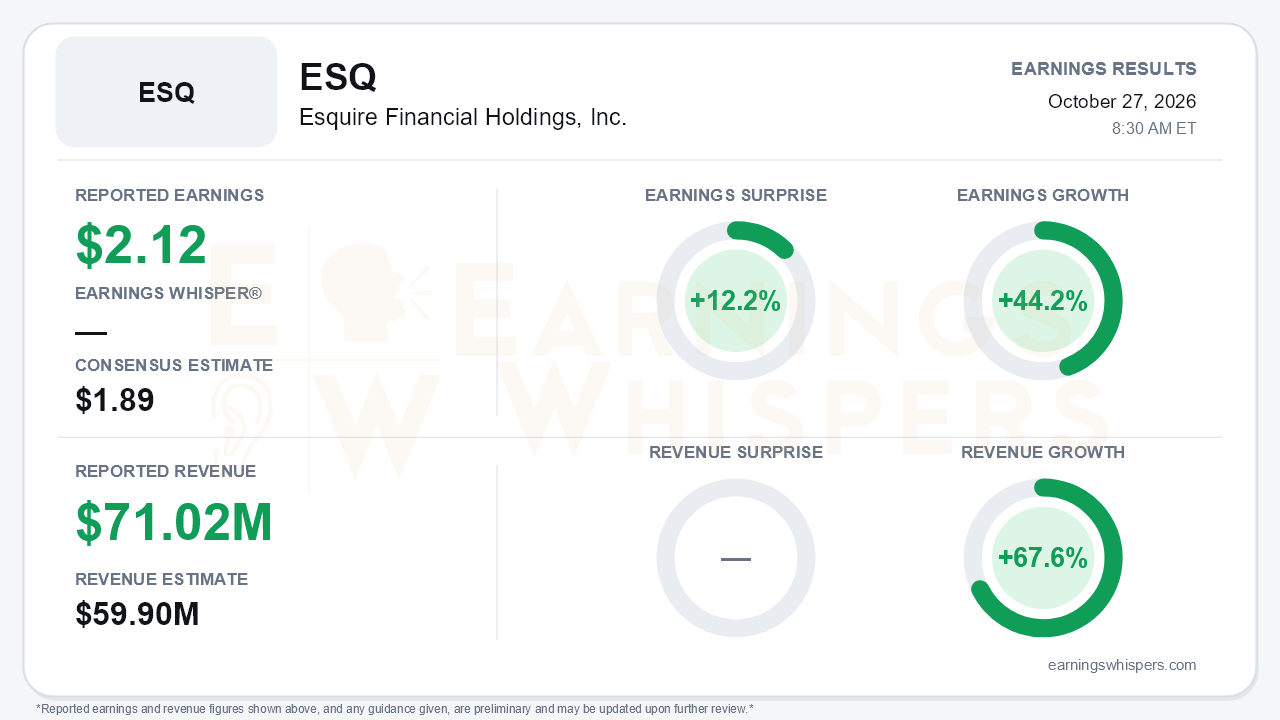
Esquire Financial Holdings delivered a clean beat in its first quarter as a combined company with Signature Bancorporation. Adjusted EPS of $2.12 topped the $1.89 consensus by 12.2% and rose 44.2% year over year. Revenue of $71.02 million beat the $59.9 million estimate by 18.6% and grew 67.6%. The more important development came on the call: management introduced an explicit fiscal 2027 outlook of roughly $9 per share and raised its combined net interest margin guide to 5.70-5.75%, well above the roughly 5.45% day-one figure it offered last quarter. Management said the deal is now tracking ahead of the earnings expectations it set when the merger was announced in March. That is the central takeaway. The acquisition is so far producing more earnings power than promised, not less.
The quality of the beat deserves scrutiny, because GAAP and adjusted results diverge sharply.
- **GAAP results:** EPS was $1.57, below the $1.62 earned a year ago. GAAP return on equity fell to 11.11% from 20.83%, weighed down by $8.9 million of pretax merger expenses and $1.8 million of core deposit intangible amortization.
- **Adjusted results:** ROA improved to 2.34% from 2.25% in the second quarter. Adjusted return on tangible equity jumped to 23.1% from 18.3%.
- **Efficiency:** The adjusted efficiency ratio dropped to 41.1% from 47.6%.
Some of that flattery is mechanical. The quarter carried only two months of Signature's roughly $5.1 million in operating costs. Day-one purchase-accounting marks also added about 6 basis points to the margin. Still, the sequential path of adjusted EPS is genuinely accelerating: $1.58 in the first quarter, $1.60 in the second and $2.12 now.
Beneath the merger math, the legacy engine strengthened. Organic litigation-related loan growth reached $160 million, a 49% annualized pace, up from $72.6 million in the second quarter and $44 million in the first. Year over year, organic loans grew 32% and organic deposits grew 24%. The merger also changed the bank's risk profile:
- Litigation loans fell to about 42% of the book from 67%.
- Litigation deposits fell to about 54% of deposits from 79%.
- Credit remained clean, with nonperforming loans at 0.25% of total loans.
- Tangible book value per share rose to $40.48 from $33.86 at year-end, consistent with the deal being about 10% accretive on day one.
The reported margin of 5.74%, or about 5.68% normalized, still fell from 5.96% in the second quarter and 6.04% in the first. Management said roughly 13-14 basis points of loan-mark accretion is embedded in the margin and runs off over about three years.
Bears have legitimate ammunition on several fronts:
- **Integration risk:** The core systems conversion from Jack Henry to Fiserv, targeted for April 2027, is the major execution test. Origination platforms and cultures also have to be integrated.
- **Rate sensitivity:** Variable-rate loans now make up about 60% of the book, down from roughly 85-90%. That reduces the upside if rates rise. Management also flagged possible pressure on IOLTA deposit costs if the Fed hikes again.
- **Loan growth framing:** The 2027 guide of about 14-15%, or roughly $500 million, is slightly below the 15-17% standalone range discussed earlier. It depends on deposit growth keeping pace.
- **Payments:** Payments remain a soft spot. Volume was essentially flat sequentially at $10.5 billion, and fee growth was described as muted because of merchant-mix changes.
- **Credit and liquidity:** Nonperforming assets rose to roughly $9.6-9.7 million on acquired credits. Off-balance-sheet sweep funds declined to $776 million from about $1 billion.
The ~$9 target also needs context. The third quarter included only two months of Signature and a weighted diluted share count of 11.1 million, below the 12.2 million shares now outstanding. Simply annualizing $2.12 therefore understates neither the coming revenue nor the coming dilution. Management's framework calls for:
- $33-34 million in fees;
- $138-140 million in expenses;
- a 28.5% tax rate.
The market setup is more complicated than the surprise implies. Investor sentiment entered the report negative and deteriorated from -0.20 to -0.39 over the quarter. That is a meaningful slide that suggests integration and dilution worries were building ahead of the print. Shares have nonetheless held up:
- At $123.84, the stock is up 5.1% since the open after the July report.
- It sits 8.7% above its 200-day moving average of $113.95.
- It is about 8% below the August 13 inter-earnings high of $134.65, after a pullback to $110.28 on September 1 that has since been largely recovered.
The Earnings Whispers trend readings are mostly positive, with sequential growth, momentum and AVWAP all constructive while price trend is neutral. A raised margin guide and a concrete EPS target are the kind of evidence that sentiment this cautious was not positioned for.
The bottom line is that Esquire's first combined quarter answered the biggest near-term question. The Signature deal is accretive, margin-resilient and, by management's account, ahead of plan, while organic litigation lending is accelerating rather than being distracted by integration. The adjusted numbers flatter the quarter somewhat, and GAAP returns will stay diluted by goodwill and intangibles. The April 2027 conversion, lower asset sensitivity and fading accretion are real tests still ahead. For now, the fundamental story improved more than investor sentiment did.
Read our earnings preview for Esquire Financial Holdings, Inc.: https://www.earningswhispers.com/article/ESQ/20694
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-08 | |
| Sep-02 | |
| Aug-25 | |
| Aug-03 | |
| Jul-30 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-14 | |
| Jun-24 | |
| Jun-23 | |
| Jun-09 | |
| May-18 |
