CMS Energy's 54.8% Adjusted EPS Jump Beats Estimates, But NorthStar Charges, Timing Help And Regulatory Haircuts Keep Guidance Flat
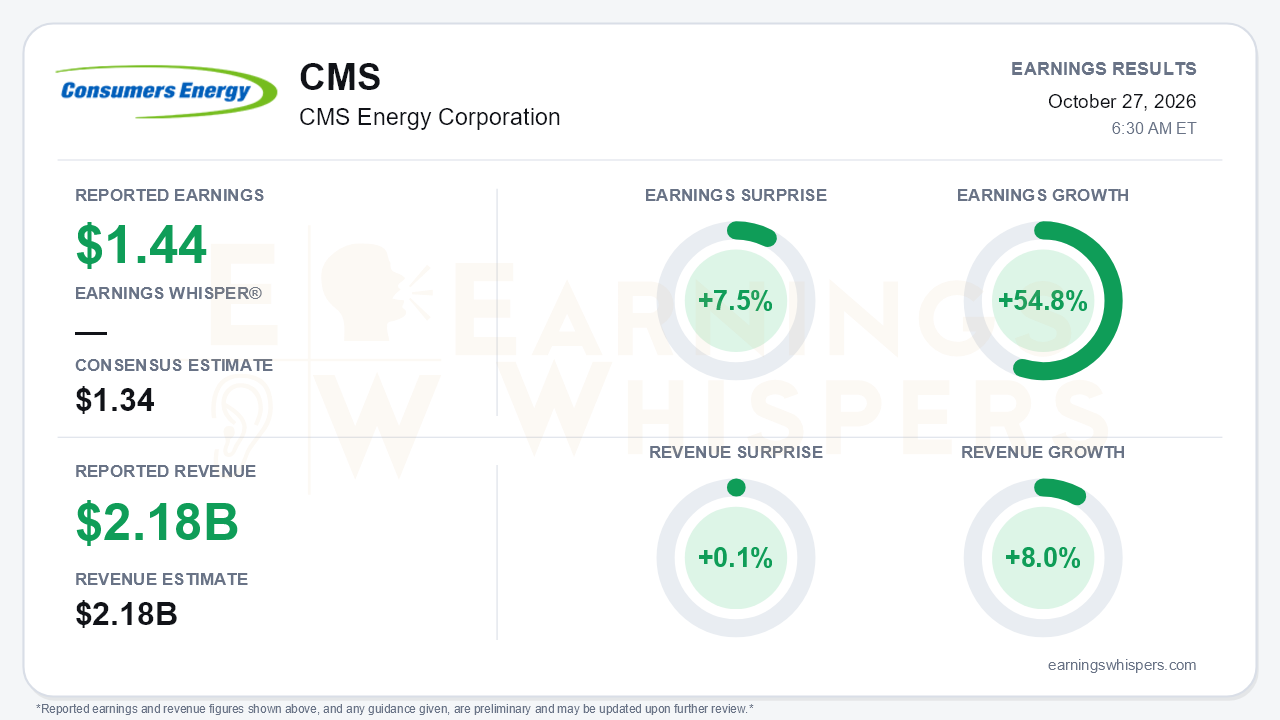
CMS Energy delivered a clean beat on its preferred measure. Adjusted earnings were $1.44 per share, 7.5% above the $1.34 consensus and up 54.8% from $0.93 a year ago. Revenue of $2.183 billion rose 8.0% and matched expectations almost exactly, a 0.1% beat. GAAP results told a very different story. Reported EPS fell to $0.39 from $0.92, and the quarter showed a consolidated net loss of $91 million before noncontrolling interests. The gap came from $456 million of pre-tax asset impairment and restructuring charges tied to NorthStar Clean Energy, worth $1.08 per share net of tax and other items. The central tension is that a powerful adjusted-earnings quarter arrived alongside unchanged guidance. Management reaffirmed 2026 adjusted EPS of $3.83 to $3.90, 2027 guidance of $4.08 to $4.17, and long-term growth of 6% to 8%, with "continued confidence toward the high end."
The quality of the beat deserves scrutiny. On the call, management credited roughly $0.08 of favorable weather versus plan. NorthStar has contributed $0.62 year to date against a full-year guide of $0.25 to $0.30, and part of that outperformance reflects tax timing that management expects to reverse in the fourth quarter. Even so, the year-to-date trajectory has clearly improved. Adjusted EPS through nine months stands at $2.95, $0.29 ahead of last year. At the end of the second quarter, the company was running $0.23 behind. Guidance implies a fourth-quarter adjusted range of about $0.88 to $0.95, which helps explain why management did not raise the full-year outlook despite the third-quarter surge. The balance sheet reflects the cost of the build-out:
- Debt excluding securitization rose to $19.7 billion from $18.3 billion at year-end.
- Quarterly interest charges climbed to $214 million from $203 million.
- Diluted shares increased to 313.2 million from 300.4 million, so per-share growth is being earned against meaningful dilution.
The call did more to change the long-term story than the quarter itself. Contracted new non-data-center load jumped to 745 MW, with about 450 MW energized, compared with roughly 110 MW at the first quarter and 135 MW at the second. The September integrated resource plan outlines roughly $27 billion of capital opportunity in clean energy, storage and gas generation, including replacement of the Karn 3 and 4 peakers. That opportunity sits beyond the current $24 billion five-year plan and its reaffirmed 10.5% rate base growth rate. Management also sharply expanded its quantified financial compensation mechanism (FCM) earnings on power purchase agreements. It now expects about $125 million by 2031, rising to about $195 million by 2040, compared with roughly $50 million by decade-end cited a year ago. More than 70% of the 2031 contracts are already signed or online. On the NorthStar sale, more than 35% of assets are signed or closed, and management said it would be "disappointed" if the funding benefit does not exceed $500 million, up from "at least $500 million" last quarter.
Bears have legitimate ammunition on the regulatory front. The gas rate order granted $139 million, about 60% of the revised $232 million request, at a 9.8% ROE and a 50% equity ratio. In the electric case, which CMS trimmed to $443 million from $456 million, staff recommends $265 million at a 9.85% ROE and a 50% equity ratio versus the 51.75% requested. That equity-ratio question matters because Moody's has a negative outlook on the utility. The Michigan Public Service Commission (MPSC) has also signaled interest in refining the FCM, which is now a much larger piece of the long-term earnings case, and post-election Michigan energy policy adds uncertainty. Separately:
- The large data center agreement remains outside the capital plan, with zoning moratoriums stalling multiple sites until after the elections.
- Analysts questioned the removal of the pipeline funnel and rate base slides from the presentation.
The market setup is more complicated than the surprise implies. Heading into the report, shares were at $69.59, down 7.1% since the open following the July report. That left the stock about 4.1% below its 200-day moving average of $72.58 and 8.9% below the inter-earnings high set on the day of the last report. The stock fell to a 52-week low of $62.29 on September 29, coinciding with the period of regulatory and data center uncertainty, before recovering 11.7% from that trough. Investor sentiment remained negative but improved modestly, moving from -0.2251 to -0.1372. That reading suggests skepticism was easing rather than giving way to optimism. Aside from a negative price trend, the Earnings Whispers trend signals lean positive, with sequential growth and momentum improving.
The bottom line is that CMS produced a strong adjusted quarter and a materially larger long-term investment runway, but weather and NorthStar tax timing flattered the beat, and guidance held rather than rose. The investment case now depends less on near-term earnings and more on regulators. Electric rate case outcomes, the equity ratio, the durability of the FCM and data center timing will determine whether the $27 billion opportunity becomes earnings growth toward the high end of the 6% to 8% target.
Read our earnings preview for CMS Energy Corporation: https://www.earningswhispers.com/article/CMS/20686
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 59 min | |
| 1 hour | |
| 6 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-19 | |
| Oct-08 | |
| Oct-06 | |
| Sep-22 | |
| Sep-03 | |
| Sep-01 | |
| Aug-24 | |
| Aug-20 | |
| Aug-12 | |
| Aug-10 |
