Central Bancompany Misses EPS By A Penny As Rising Rates Widen The Margin While Loan Growth Cools
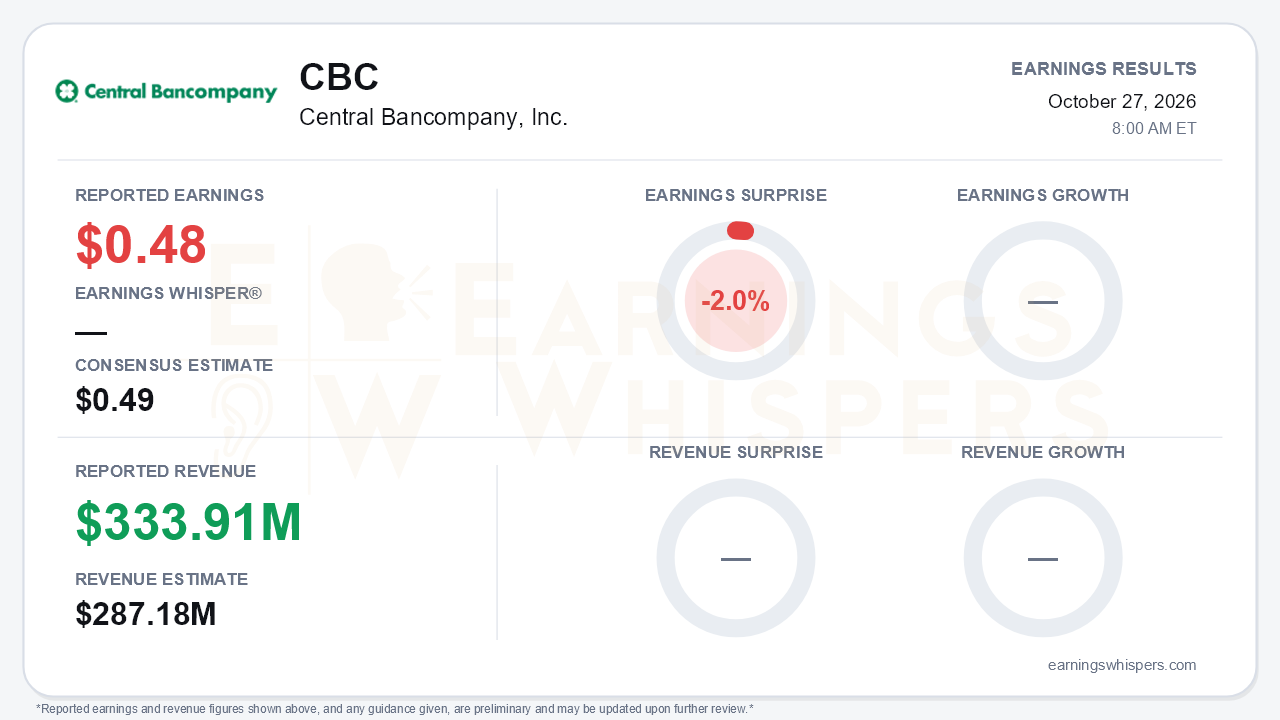
Central Bancompany (NASDAQ: CBC) earned $0.48 per share in the third quarter, a penny below the $0.49 consensus, a 2.0% miss. Revenue of $333.91 million beat the $287.18 million consensus by 16.3%. Read them together and the headline numbers send mixed signals. Read the release, and the story is clear: CBC's asset-sensitive balance sheet is doing exactly what it was built to do now that the rate cycle has turned from cuts to hikes. Net interest margin expanded to 4.48% (4.51% FTE) from 4.40% in the prior quarter. Net income rose for a fourth straight quarter, to $116.2 million from $113.8 million in Q2, $111.1 million in Q1 and $107.6 million in Q4'25. The miss says more about how tightly the estimate was set than about any break in the earnings engine.
The quality of the quarter deserves some scrutiny on both lines. On revenue, the company's own net revenue measure, net interest income plus noninterest income, was $285.7 million. The supplied $333.91 million figure lines up with gross interest income plus fee income, so the size of the beat partly reflects how revenue is defined rather than pure outperformance. On earnings, GAAP net income jumped 19.7% year over year. Diluted EPS rose only to $0.48 from $0.44, however, because the weighted share count is nearly 9% higher than a year ago. On an adjusted basis, which strips out last year's securities losses, EPS edged up just to $0.48 from $0.47. The operating leverage is still genuine. Net interest income grew 10.0% while expenses rose 3.2%, and the FTE efficiency ratio improved to 45.4% from 46.1% in Q2 and 47.7% a year ago. Wealth management revenue grew 16.7% on 13.8% growth in assets under advice. Mortgage banking fell 14.3%, which held adjusted fee growth to 4%.
The call sharpened the central tension: margin is accelerating while balance-sheet growth is decelerating. Net interest income rose about $20 million year over year, up from a $17.7 million increase in Q2. Management also widened its repricing narrative:
- $700 million of fixed-rate loans reprice in Q4, and $2.2 billion reprice in 2027, at roughly 6% with about a 100-basis-point reinvestment pickup.
- A newly significant securities repricing opportunity has emerged, after management said last quarter there was little.
Loan growth, however, slowed to roughly 3% annualized (about 4% excluding the deliberately shrinking other-consumer book), from 6.5% in Q2 and about 6% in Q1. Management cited moderation in certain markets because of higher rates, though it said pipelines remain as strong as last quarter. Period-end loans finished $54 million above the quarterly average, which gives Q4 a modest head start.
Credit is not a problem, but it is drifting the wrong way, and bears have legitimate ammunition here.
- Nonperforming commercial loans rose to $32.8 million, up 15% sequentially and 79% year over year. That marks a second straight quarterly increase, which management described as situational.
- Net charge-offs ticked up to 12 basis points from 10.
- Delinquencies rose to 24 basis points from 21 a year ago.
The absolute levels remain benign, with nonperforming assets at 33 basis points and reserve coverage held at 1.29%. Still, the direction bears watching as rates climb. Management also flagged uncertainty about deposit betas and added a cash flow hedge to temper asset sensitivity. That is a prudent move, but it caps some of the upside from further hikes.
Capital deployment remains the unresolved question. Excess CET1 capital grew to $2.0 billion, or $8.28 per share, against a 13.5% target. Buybacks were minimal, constrained by a $100 million authorization and limited float, and there was again no M&A update. The idle capital is diluting returns: ROE has been stuck at 11.9% and adjusted ROTCE slipped to 13.1% from 14.2% a year ago. Rising rates also widened the accumulated other comprehensive loss to $177 million from $66 million in Q2, so book value per share dipped to $16.04 and core tangible book fell to $6.30. Investors should also expect Q4 GAAP results to be inflated by an expected ~$27 million pre-tax pension termination gain that will not recur.
The market setup is more complicated than the small miss implies. Shares entered the report at $34.83, up 8.1% since the open after the August report, 22.6% above the 200-day moving average, and within 0.8% of a 52-week high of $35.12 set the day before. Investor sentiment moved the other way. It remained negative and weakened modestly, from -0.22 to -0.31, suggesting skepticism is building even as the price climbs. Momentum and AVWAP trend readings are positive, while sequential growth is neutral, consistent with a stock riding margin momentum rather than broad acceleration.
The bottom line is that CBC delivered a fundamentally solid quarter dressed up as a narrow miss. Rate-driven margin expansion and a lengthening repricing runway are real tailwinds. Slowing loans, creeping commercial credit stress, deposit-beta uncertainty and $2 billion of underused capital keep the story from being clean. With shares pressed against their highs, the stock needs the repricing thesis to keep showing up in earnings.
Read our earnings preview for Central Bancompany, Inc.: https://www.earningswhispers.com/article/CBC/20684
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Sep-30 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| May-21 | |
| Apr-29 | |
| Apr-28 | |
| Apr-28 | |
| Apr-06 | |
| Jan-27 | |
| Jan-27 | |
| Jan-09 |
