Armstrong World Misses On EPS As Freight And Mix Pressure Force Its First Profit-Guidance Cut, Overshadowing Record Specialties Growth
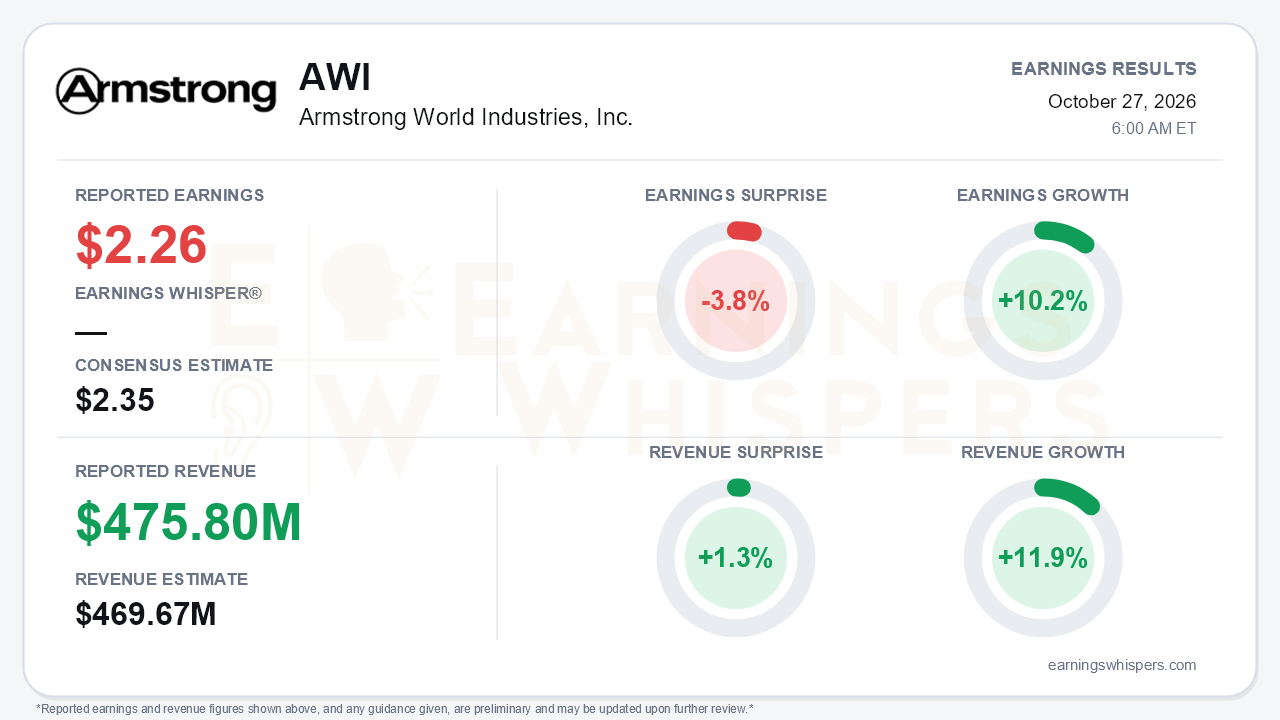
Armstrong World Industries delivered record third-quarter sales but fell short where it matters most for the stock. Adjusted EPS of $2.26 missed the $2.35 consensus by 3.8%, while revenue of $475.8 million beat expectations by 1.3%. Earnings grew 10.2% year over year and revenue rose 11.9%, so growth was healthy. The central tension is that top-line momentum is accelerating while profit conversion is weakening. Management raised its sales outlook and cut every major profit and cash-flow metric in the same release, the first profit-guidance reduction of the year after midpoints were raised in the second quarter.
The quality of the quarter deserves scrutiny. Volume added $35 million to sales and favorable AUV added $16 million, yet gross profit rose only to $190.7 million from $178.5 million. Manufacturing costs increased $10 million, driven mainly by freight and raw-material inflation. Two items cushioned operating income:
- a $4 million increase in WAVE joint-venture equity earnings;
- a $3 million decline in Mineral Fiber SG&A, which reflected higher incentive compensation in the prior-year period.
Consolidated operating margin was flat at 27.6%, and adjusted EBITDA margin slipped 30 basis points to 34.5%. Both segments expanded margins, but the faster-growing, lower-margin Architectural Specialties business made up more of the sales mix. Below the operating line, the effective tax rate jumped to 26% from 21%. That helps explain why GAAP net earnings rose only 6.5%, even though pre-tax earnings grew faster. A lower diluted share count, 42.3 million versus 43.6 million, supported the per-share figure.
On the call, the growth story was strong. Architectural Specialties posted record organic growth of 16%, up from 9% in the second quarter and 7% in the first. Segment sales rose 21.5%, and segment EBITDA climbed 25.5%. Order intake stayed at double-digit growth, and data-center ceiling and Dynamax structural grid sales have already exceeded full-year plans. Management lifted segment sales guidance to 18-19% from 15-17%, with organic growth now expected in the low teens.
Mineral Fiber is where the outlook deteriorated. The segment posted a third straight quarter of volume growth, but the volume gain was only $2 million and came largely from timing-related Canadian demand tied to tariffs. Management warned that this pull-forward may reverse in the fourth quarter. Other Mineral Fiber changes:
- the AUV outlook fell to about 5.5% from about 6%, reflecting mix from lower-AUV channels and slightly softer U.S. commercial demand;
- the full-year margin is now expected to be roughly flat at about 43.5%, rather than expanding toward 44%.
Freight inflation has reached roughly 20%, up from mid-teens in the second quarter and flat at the start of the year. Total input inflation is now at the high end of the mid-single digits.
The revised full-year guidance reflects that squeeze:
- adjusted EBITDA growth of 8-10%, down from 9-12%;
- adjusted EPS of $8.30 to $8.40, or 12-13% growth, down from 12-15%;
- adjusted free cash flow growth of 10-13%, down from 10-14%;
- total sales growth of 10-11%, nudged up from 9-11%.
The EPS range implies a fourth quarter of roughly $1.99 to $2.09 against the $6.31 earned through nine months. Cash flow also softened. Year-to-date adjusted free cash flow is down 2%, compared with up 9% at midyear, and third-quarter adjusted free cash flow fell to $106 million from $123 million.
Other risks raised on the call:
- the Parallel acquisition is ramping more slowly than expected, and acquisitions are roughly a $2 million EBITDA drag;
- custom Specialties projects face pricing lag on metals;
- industry sentiment is more cautious, with higher rates and some lengthening of bid-to-award cycles, though bidding remains stable.
On the offensive side, management is relying on November price increases in Mineral Fiber and WAVE. It also cited a multi-million-dollar, roughly 500,000-square-foot advanced-manufacturing win for the new SkyLo walkable ceiling, along with a 10% dividend increase.
The market setup is more complicated than the modest miss implies. Investor sentiment became meaningfully more positive heading into the report, rising to 0.37 from 0.19, so expectations had firmed just as profit guidance was about to be trimmed. Price action had been less generous. Shares closed at $164.82 before the release, 3.2% below the opening price after the July report and 3.2% below the 200-day moving average. The stock peaked at $188.59 on the day of the prior report and has since given back that entire spike. It fell to a $156.91 low in mid-September and sat only 5% above that level entering earnings. The company bought back $75 million of stock during the quarter at an average of $174.36, above where shares now trade.
The bottom line is that Armstrong's demand story improved while its earnings story got harder. Architectural Specialties is growing at a record pace and gives the call a credible growth narrative. However, bears have legitimate ammunition:
- an EPS miss;
- a cut to profit guidance;
- Mineral Fiber margins that are no longer expanding;
- cash flow that is slipping.
With the stock already below its 200-day average and sentiment having climbed into the print, near-term direction likely depends on whether the November price increases can catch up to freight inflation before the Canadian pull-forward unwinds.
Read our earnings preview for Armstrong World Industries, Inc.: https://www.earningswhispers.com/article/AWI/20680
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-06 | |
| Sep-17 | |
| Jul-30 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-21 | |
| Jul-08 | |
| Jul-07 | |
| May-27 |
